


3 Australian Dividend Stocks To Own In October 2026
With Australian inflation at 4% and interest rates at their highest level since 2011, cash in the bank can feel like it is going backwards. Reliable dividend payers offering yields above 5% suddenly look less like a niche and more like a lifeline. This article breaks down three long running Australian dividend stocks that combine steady payout records with income levels many term deposits struggle to match.
The three dividend stocks covered next are just a sample of what income focused investors might consider, and the full screen surfaced 0 more companies with similarly compelling stories that are not covered here. To go wider than this short list, head straight into the Dividend Aristocrats screener to identify, filter and analyze the highest conviction dividend plays that fit your income goals.
Vita Life Sciences (ASX:VLS)
Vita Life Sciences is a A$149 million healthcare group that formulates and sells branded vitamins and supplements such as Herbs of Gold, VitaHealth and VitaScience through pharmacies and health food outlets. The group generates around A$43 million from Australia, A$46 million from Malaysia and Singapore, and A$6 million from China and Vietnam.
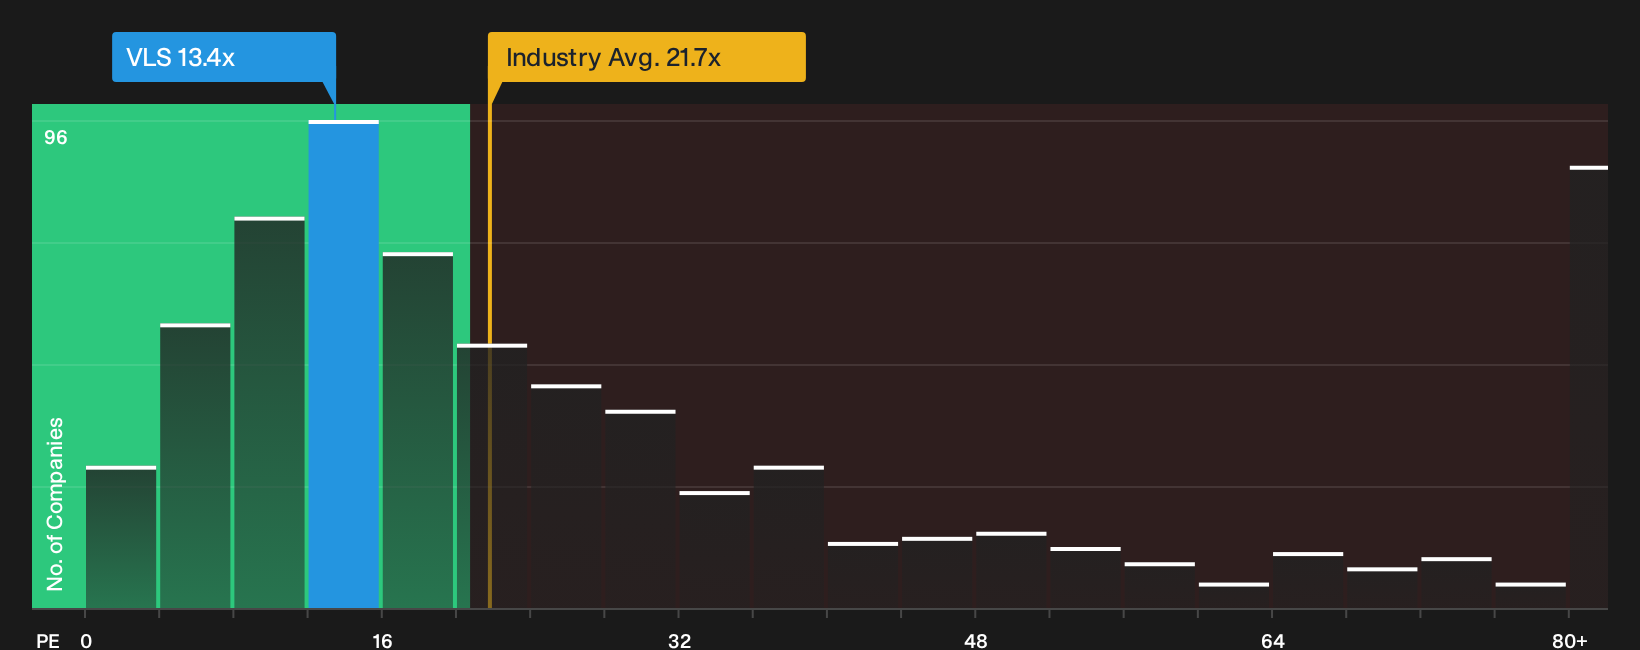
For income investors seeking stable yields above 5%, Vita Life Sciences combines recurring pharmacy shelf space with a 5.07% dividend yield and a P/E of 13.4 that is below many global peers. However, the appeal of those cash payouts ultimately depends on how one currently unseen funding pressure develops.
To see how that funding pressure interacts with valuation, income and balance sheet strength, start with the 3 key rewards and 1 important warning sign for the next layer of detail.
Peet (ASX:PPC)
Peet is a Perth based residential land developer with a A$744 million market cap, earning A$305 million from Development, A$95 million from Funds Management and A$33 million from Joint Arrangements. That funds platform pools long term income producing land and JV projects that support higher yielding dividends.
For income hunters, Peet links a traditional land development pipeline with a Funds Management arm that throws off recurring cash flow, plus A$103.4 million of net income on A$419.13 million of revenue in 2026 and a fully franked interim dividend of A$0.065. The appeal of that blend of yield and stability still hinges on how one future ownership shift reshapes distribution policy.
That potential shift in who controls the cash calls the shots on future payouts, so drill into the 2 key rewards and 1 important warning sign to see how Peet's yield story could evolve.

Sandfire Resources (ASX:SFR)
Sandfire Resources is a copper focused miner that earns most of its income from producing copper concentrates, which is what supports its role in a high yield Dividend Aristocrats screen. The Motheo Copper Project generated about US$745 million and MATSA about US$910 million in sales, backing a market value near A$10.3 billion.
Income investors looking for dividends that feel more repeatable than a lucky strike often end up studying copper producers like Sandfire Resources, where long life assets and multi year mine plans can underpin payout decisions across different parts of the cycle.
"The global acceleration of energy transition (EVs, renewables, grid upgrades) continues to underpin structural demand for copper, directly supporting Sandfire's core product pricing and offering a favorable backdrop for group sales volumes and future earnings expansion."
What could really tilt the income story now is how one less visible pressure shapes the balance between rich yields and future cash coverage.
That pressure point is exactly what sits at the heart of the full narrative for Sandfire Resources, where accelerating copper demand meets the less obvious risks shaping Sandfire Resources' income story.

Seeking Alternatives Before The Crowd Moves
Fresh ideas gain momentum fast. Breakout stories rarely stay under the radar for long before prices start flying and opportunities get caught by late money. Scan the next wave and get in early.
- Jump on future trend leaders by screening for 5 high quality undervalued stocks that still sit in the sweet spot between quality fundamentals and attractive entry prices.
- Target resilient income ideas by scanning the 3 dividend fortresses that combine strong balance sheets with yields designed to keep cash flow coming while it matters.
- Track the next infrastructure tailwinds by reviewing the 40 power grid technology and infrastructure stocks before demand stories are fully priced in and early momentum starts dropping.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com