


Could Home Compute Partnership Change The Bull Case For Sunrun (RUN)?
- Sunrun reported that its expanded partnership with SPAN will use Sunrun home solar and multi-battery storage systems to power SPAN's XFRA distributed compute nodes through prepaid leases that include whole-home backup and compensation for host customers.
- The arrangement ties Sunrun's residential energy platform directly to AI compute demand, linking its home battery fleet, grid services programs, and distributed data center capacity into a single operating model.
- We will now look at how this Sunrun partnership, which ties residential batteries to distributed AI compute, could reshape the investment narrative.
Scan beyond Sunrun and this AI powered home energy theme by reviewing the hand picked 90 AI infrastructure stocks that could benefit from similar demand for distributed compute capacity.
Sunrun Investment Narrative Recap
To own Sunrun, you need to believe residential solar, storage and grid services can support a durable, cash generative energy services platform, even as tax incentives roll off and policy shifts keep the industry on edge. The SPAN partnership connects Sunrun to AI compute demand, but the near term swing factor still appears closer to execution on storage attach rates and grid services monetisation.
The main operational risk remains capital intensity and reliance on external funding, with interest payments not yet well covered by earnings and the share price down sharply over 1 and 5 years. If residential demand softens as tax credits change or safe harbored equipment proves mismatched to actual sign ups, that pressure could increase, regardless of how quickly XFRA nodes roll out.
The SPAN deal arrives in the context of Sunrun already pushing hard into batteries and grid services, with around 200,000 batteries enrolled and an internal target of 10 GWh of dispatchable energy by 2029. XFRA nodes provide another outlet for that stored power and another way to keep the virtual power plant fleet active.
For you as an investor, the key question is how consistently Sunrun can turn that capacity into recurring revenue without overstretching the balance sheet. The firm reports P/E based valuation metrics that some analysts view as attractive, while interest coverage and reliance on higher risk funding sources remain important considerations. The XFRA partnership shifts the story more toward services and less toward one off installs, but the critical factors are execution volume, uptime and contract economics over the next few years.
Sunrun's current analyst narrative points to revenue of US$3.6b and earnings of US$570.8m by 2029, based on an assumed 1.3% yearly revenue growth rate and a move from earnings today of US$400.7m. This implies an earnings increase of roughly US$170m by the same forecast year.
Uncover why Sunrun's fair value indicates a 107% potential upside to its current price before momentum in Sunrun closes that valuation gap.
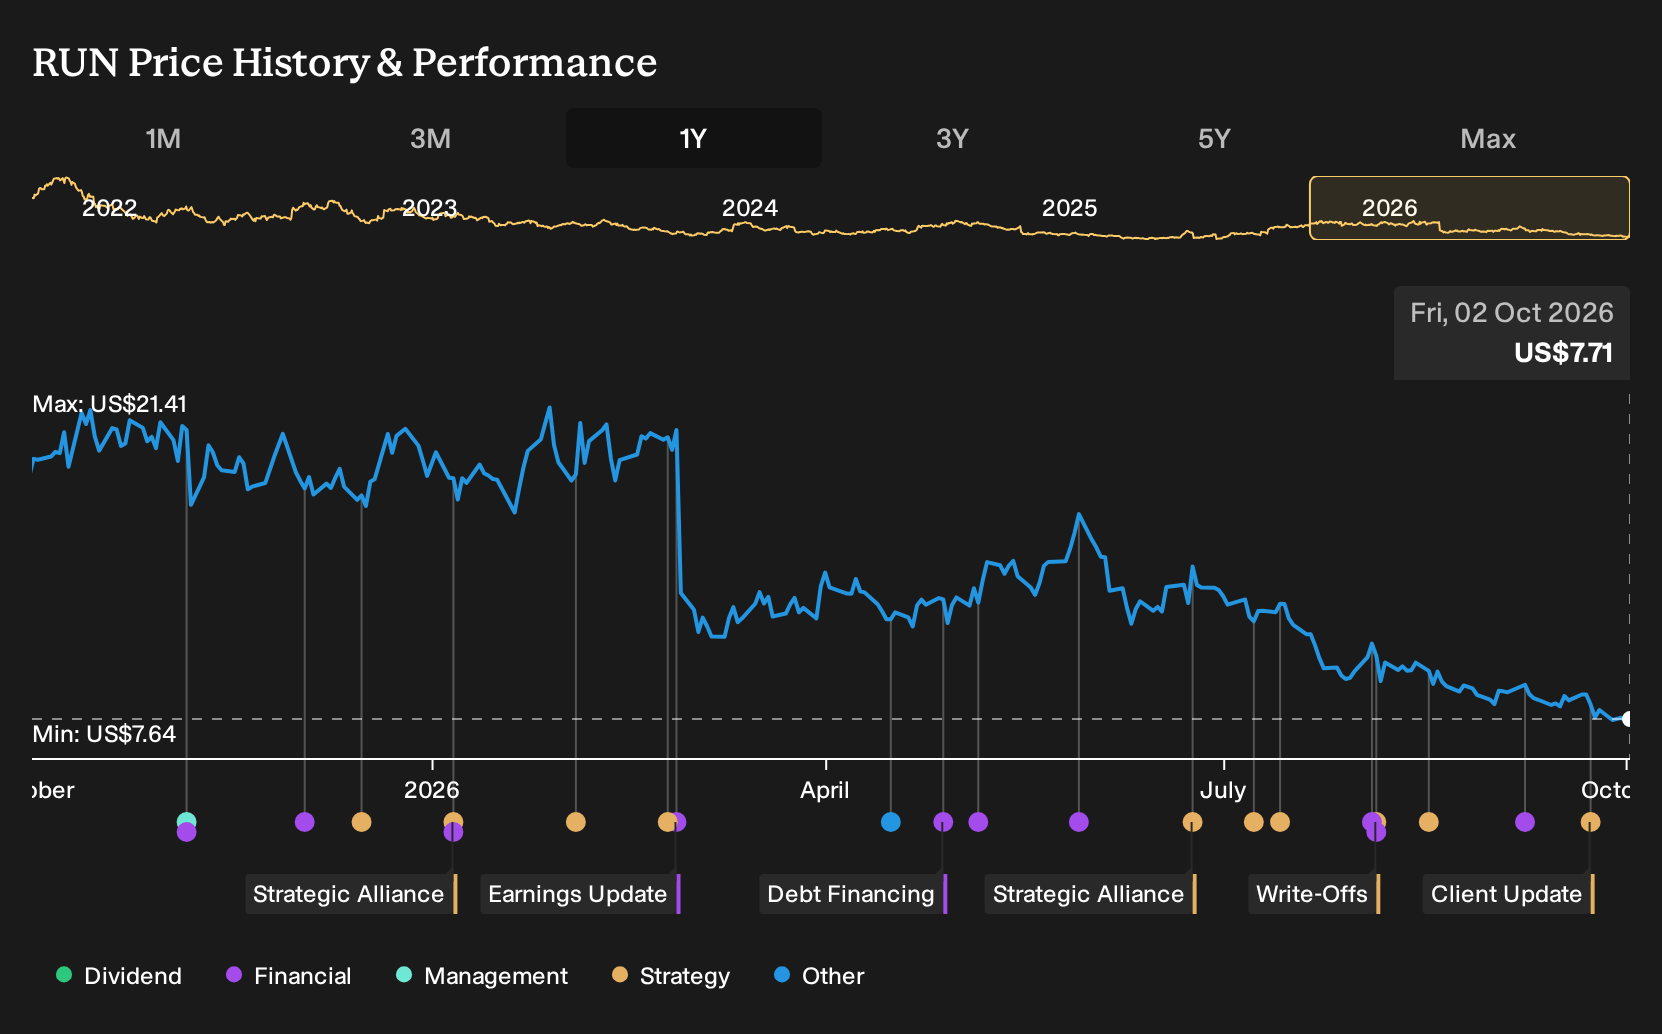
Exploring Other Perspectives
You might see the Sunrun and SPAN AI partnership as a fresh demand source, yet the most bearish analysts focus on tightening credit instead. They were modeling revenue of about US$2.7b by 2029 and earnings of roughly US$299.6m before this news, which shows how sharply opinions can diverge. It is worth exploring those different views yourself, since both sets of forecasts were built before AI compute entered the story in this way.
Explore 4 other Sunrun fair value estimates, including one that suggests it could be worth just $15.87!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sunrun research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sunrun. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sunrun's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sunrun?
If this Sunrun story has sharpened your interest in how different businesses balance risk, cash flow, and future opportunity, it can help to line it up against a wider watchlist. Use the Simply Wall St Screener to compare this stock with others that match the kind of balance sheet strength, valuation profile, or income potential you want to focus on next.
- For investors who want potential upside without ignoring fundamentals, scan the 19 high quality undiscovered gems that combine quality metrics with less crowded ownership.
- If capital preservation sits high on your priority list, narrow your search to a 31 resilient stocks with low risk scores that filters for steadier balance sheets and lower risk scores.
- Income focused readers can zero in on a 7 dividend fortresses that highlights companies offering yields above 5% while aiming for durability in payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com