


Does Dividend Increase Change The Bull Case For American Financial Group Stock?
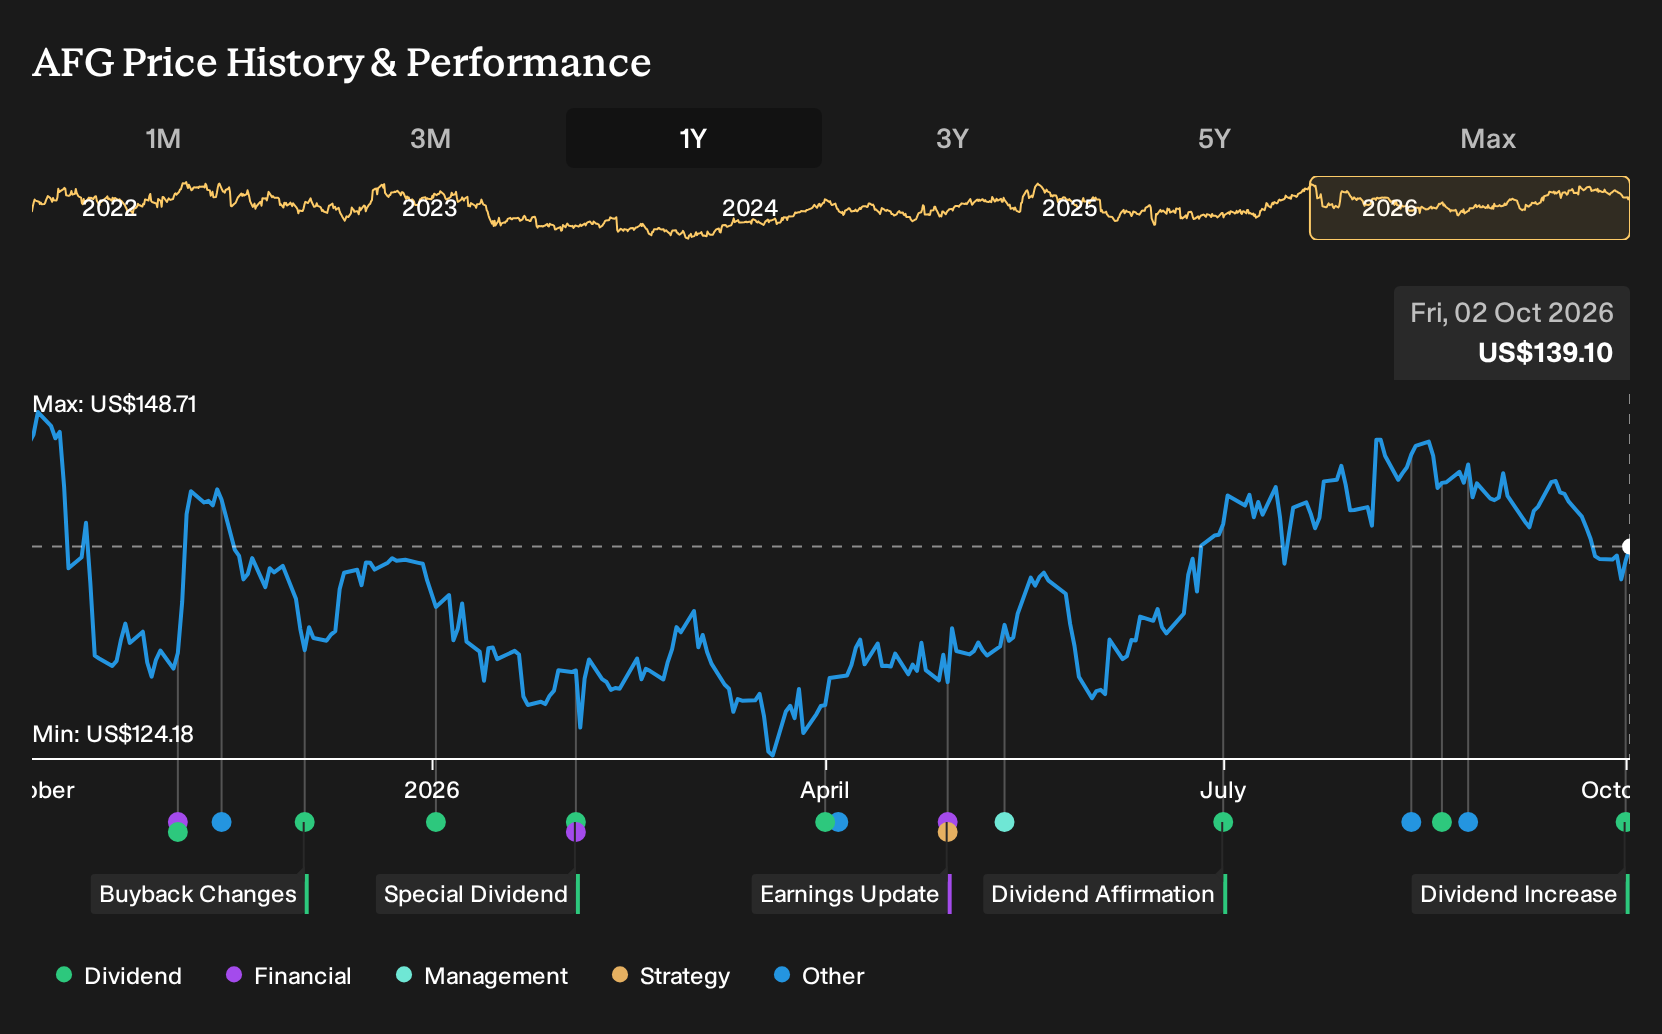
- American Financial Group has declared a regular dividend of $0.97 per share, payable on October 23, 2026, to shareholders of record on October 15, 2026. This reflects a previously announced 10.2% uplift over the annual rate in place since late 2025.
- The larger regular payout highlights how American Financial Group is using excess capital from its specialty P&C insurance operations and investment portfolio to return more cash to shareholders while maintaining its core underwriting focus.
- We will look at how American Financial Group's investment narrative is shaped by this 10.2% regular dividend increase announcement.
American Financial Group Investment Narrative Recap
To own American Financial Group, you need to be comfortable tying your thesis to specialty P&C underwriting, disciplined pricing and steady investment income rather than fast premium expansion. The 10.2% uplift to the regular dividend signals confidence in cash generation, but on its own it does not change the near term swing factors around underwriting profit and investment returns.
The biggest near term catalyst is how effectively American Financial Group keeps rate increases and remediation efforts ahead of social inflation in casualty, commercial auto and workers' compensation lines. The key risk is that loss severity or alternative investment volatility undercuts those efforts and chips away at margins and capital flexibility.
The regular dividend of US$0.97 per share, reflecting that 10.2% increase over the annual rate in place since late 2025, ties directly into the existing narrative about capital returns. Management has already been returning substantial cash through regular and special dividends alongside buybacks, and this new payout fits into that pattern of using excess capital.
For you as an investor, the interest lies in how sustainable that dividend stream looks against slower net premium growth, social inflation pressure and a more volatile alternatives portfolio. If American Financial Group can keep combined ratios in check and reinvest its fixed income book at around mid single digit yields, it may have more room to keep balancing shareholder distributions with the need to support underwriting and reserves.
American Financial Group Dividend Story Against Analyst Expectations
American Financial Group's dividend move sits next to a consensus model that points to relatively steady top line assumptions and a bigger focus on earnings quality. Analysts are working with fairly flat revenue expectations over the next few years, and they are building in margin expansion from 11.8% today to 13.1% in three years as underwriting and investment income do more of the heavy lifting.
On the earnings line, current profit of US$953.0 million is expected to reach US$1.0b by about 2029. That implies an earnings increase of roughly US$47 million over the forecast window, helped by both higher margins and a modest decline in the share count of about 0.58% per year. For dividend focused investors, that setup links directly to the question of whether per share earnings can keep compounding enough to support a rising regular payout alongside specials and buybacks.
Valuation work in the consensus suite brings these assumptions together. Analysts frame their view around 2029 revenues of US$7.9b and earnings of US$1.0b, with the stock trading on a P/E multiple of 15.1x on those profits, compared with 12.3x today and an industry level of 11.1x. The current average price target sits at US$155.83 against a share price of US$141.24 as of late 2026. The spread between the most optimistic US$175.0 view and the more cautious US$136.0 highlights that the market does not fully agree on how dependable those profit and capital return streams will be.
American Financial Group's narrative projects US$7.9b revenue and US$1.0b earnings by 2029. This implies fairly flat yearly revenue growth and an earnings increase of about US$47 million from US$953.0 million today.
Uncover why American Financial Group's fair value indicates a 12% potential upside to its current price, a valuation gap that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span a wide band, from US$122 at the low end to more than US$300 at the top. This highlights very different views on American Financial Group. Some members still flag underwriting volatility and social inflation as key swing factors, while others focus on bond reinvestment yields and ongoing capital returns. Investor opinions clearly vary, so it is worth exploring several of these community viewpoints before leaning too heavily on a single narrative.
Explore 2 other American Financial Group fair value estimates, including one that suggests as much as 116% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American Financial Group research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Financial Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Financial Group's overall financial health at a glance.
Looking for more investment ideas beyond American Financial Group?
If the American Financial Group story has sharpened your focus on income, quality and risk, it can help to line it up against other businesses with similar traits. The Simply Wall St Screener gives you a way to filter for fundamentals first, then compare how different stocks approach dividends, balance sheet strength and capital returns.
- For investors who care most about resilient balance sheets and sturdy fundamentals, scan a curated list of solid balance sheet and fundamentals (26 results) that can help you stress test your income positions against financial strength.
- If you want to cast a wider net for companies that may trade below their estimated worth, run through a hand picked 31 high quality undervalued stocks that focuses on quality first and valuation second.
- Income seekers who like the American Financial Group dividend profile can line it up against a focused 9 elite penny stocks with strong financials that highlights stocks prioritizing regular cash returns alongside fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com