


Should TV Return To Canada Require Action From Panasonic (TSE:6752) Investors?
- Panasonic Holdings, through its partner SKYWORTH USA, has already reintroduced Panasonic TV products to Canada with a 2026 lineup centered on Z85C OLED and W90C QD-Mini LED models in 55 inch and 65 inch sizes for home cinema, sports, streaming and gaming use.
- The focused two series range suggests Panasonic Holdings is concentrating resources on a premium, feature rich Canadian TV offering, which could influence product mix, marketing spend and manufacturing priorities across its broader lifestyle electronics operations.
- We will look at how Panasonic Holdings' investment narrative is affected by this focused Canadian return built around OLED and QD Mini LED.
Scan beyond Panasonic Holdings and see how other premium home-entertainment players are positioned by running the curated 90 robotics and automation stocks that capture similar hardware driven consumer demand.
Panasonic Holdings Investment Narrative Recap
To own Panasonic Holdings, you need to believe that its mix of Energy, HVAC and Smart Life products can steadily turn forecast earnings growth into cleaner margins and better cash generation, despite pressure in EV batteries and consumer electronics. The Canadian TV relaunch fits into that Lifestyle story but looks modest next to the much larger Energy and automotive operations.
The key near term swing factor still sits in execution on North American battery capacity and cost control, not TVs. The biggest risk remains weaker EV demand and policy shifts that could blunt factory utilization and delay margin repair, while consumer electronics faces fierce price competition that can keep profitability thin.
The Canada TV announcement matters most as a small proof point for the Smart Life segment. A tight Panasonic Holdings lineup focused on Z85C OLED and W90C QD Mini LED keeps R&D and marketing concentrated in higher value products, which can support mix quality if units scale sensibly and discounting is controlled.
For catalysts, investors are still primarily watching industrial energy storage demand and earnings growth that external forecasts currently estimate at about 21.9% a year. The TV relaunch sits alongside that as an incremental test of whether Panasonic can keep its Lifestyle portfolio positioned at the premium end of the market while managing restructuring, one off items in recent results, and exposure to fast moving consumer tech cycles.
Panasonic Holdings' current revenue outlook points to yearly top line growth of 3.9%, with analyst models calling for ¥9,165.1b of sales and ¥735.4b of earnings by 2029. That compares with earnings today of ¥253.2b, implying an increase of about ¥482.2b to reach the 2029 consensus figure.
Uncover why Panasonic Holdings' fair value indicates a 9% potential upside to its current price, which could narrow quickly.
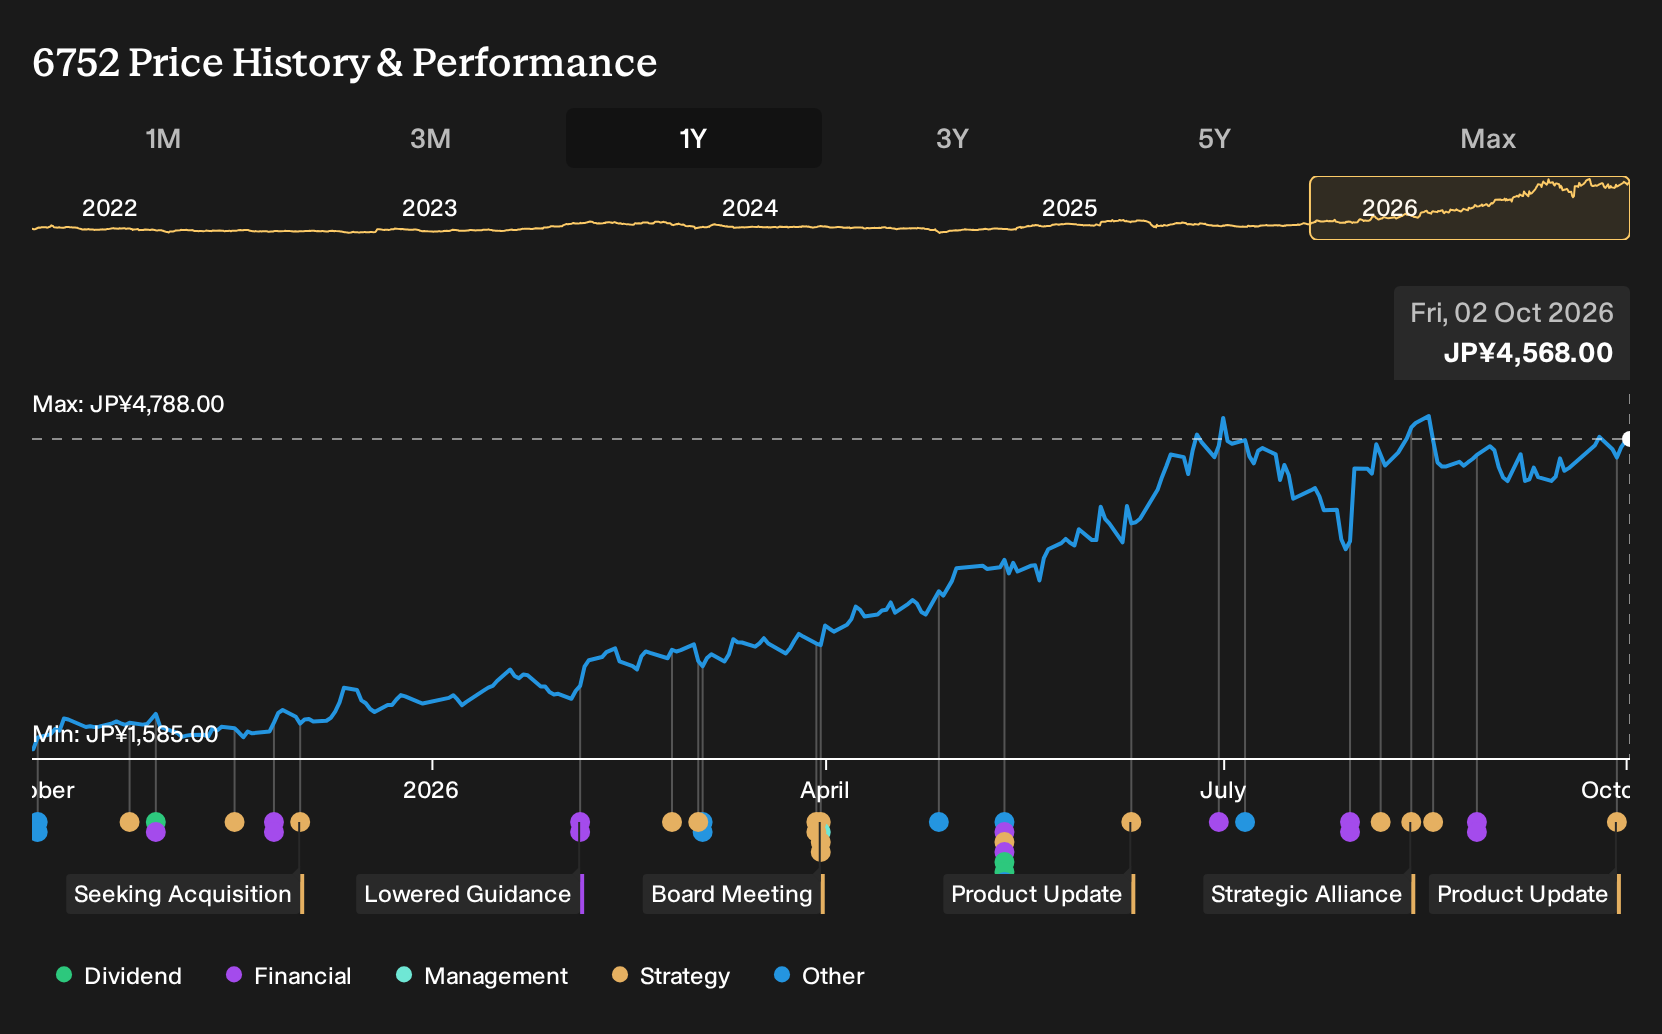
Exploring Other Perspectives
Some of the most optimistic analysts anchor their story to Panasonic Holdings’ battery and data center opportunity, not its TVs. Before this Canada relaunch, the bullish camp was already modeling revenue of ¥10,033.6b and earnings of ¥1,005.0b by 2029. You can now ask whether a tighter premium TV push nudges those expectations even higher or forces a rethink.
Explore 3 other Panasonic Holdings fair value estimates, including one that suggests as much as 38% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Panasonic Holdings research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Panasonic Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Panasonic Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Panasonic Holdings?
If this Panasonic Holdings story has you thinking about where else capital could work harder for you, it might be time to widen the lens with a few targeted screens on Simply Wall St.
- If you want potential value paired with quality fundamentals, scan a curated set of 75 high quality undiscovered gems that the market may not be paying close attention to yet.
- For readers who care most about capital protection and steadier profiles, filter the market through a 23 resilient stocks with low risk scores that focuses on businesses with more resilient characteristics.
- When financial strength and cleaner balance sheets are non negotiable, run a list of solid balance sheet and fundamentals (23 results) to focus on companies built on sturdier foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com