


How Investors Are Reacting To Rexel (ENXTPA:RXL) Follow On Share Sale
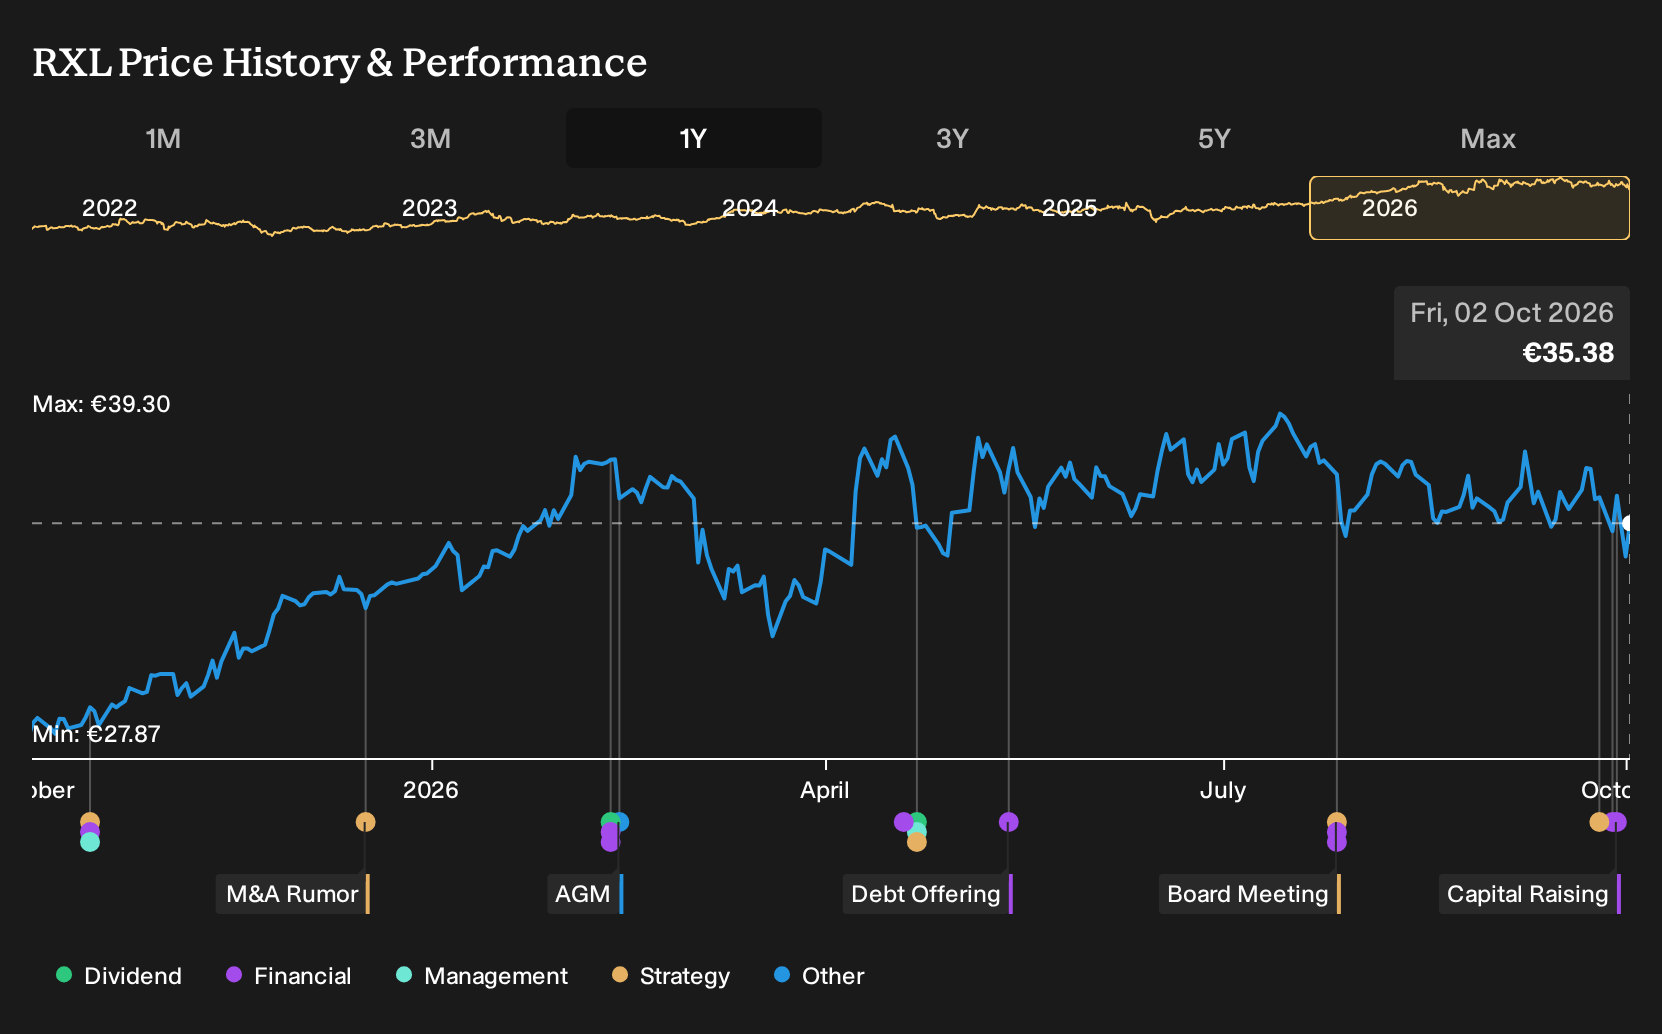
- Rexel S.A. recently completed a follow on equity offering of about €500 million, issuing 14,388,490 ordinary shares at €34.75 each.
- The fresh equity funding reshapes Rexel's balance sheet flexibility, which can influence how management approaches acquisitions, digital investment, and service expansion.
- We will now look at how Rexel's investment narrative could be reshaped by the completed €500 million follow on equity raise.
Compare how Rexel is reshaping its capital structure with other businesses tightening up their finances after fresh funding by scanning our hand picked list of solid balance sheet and fundamentals (208 results).
Rexel Investment Narrative Recap
To own Rexel, you need to believe the electrical distribution market keeps rewarding scale, reliable logistics, and deeper service around electrification and digital infrastructure. The business is leaning on data centers, broadband and energy transition projects, plus growing digital channels, to keep volumes healthy and protect margins, even if headline revenue growth expectations remain single digit.
Right now, the key near term swing factor is how well Rexel offsets weaker regions like parts of Europe and China with stronger demand in North America and value added services. The €500 million share issue mainly affects balance sheet mix, so it does not fundamentally change those operating catalysts or the core risk around soft end markets.
The completed follow on equity offering of about €500 million is the announcement that most directly matters here. Fresh equity can reduce reliance on debt funding in a business that already carries a meaningful leverage load, and potentially leaves more room to keep investing in logistics, digital platforms and acquisitions without stretching the balance sheet as much.
For shareholders, the focus is on what Rexel does with that extra flexibility. If management channels it into digital sales, value added services and exposure to sectors like data centers and broadband, it may support the existing growth and margin narrative. If demand in Europe or APAC weakens further, the raised capital could mainly serve as a buffer rather than an accelerator for those catalysts.
Rexel Earnings And Revenue Assumptions After The Equity Raise
Analysts now frame Rexel's long term story around a mix of steady top line expansion and firmer profitability targets. Consensus assumes revenue grows by 5.6% a year over the next three years, while profit margins are expected to shift from 3.4% today to 4.2% by year three.
On earnings, the group is modeled to move from €668.8 million today to €973.0 million by 2029, which is roughly a €304 million step up in profit. That central view sits inside a wide range, with the most optimistic forecasts at €1.1b and the most cautious at €867.7 million, so this is not a tightly clustered set of expectations.
Rexel's narrative projects €23.1b revenue and €973.0 million earnings by 2029. This implies 5.6% yearly revenue growth and an earnings increase of about €304 million from €668.8 million today.
To line that earnings path up with current share prices, analysts plug in a 16.2x P/E multiple on those 2029 profits, compared with about 15.6x today and 15.8x for the broader GB Trade Distributors group. The analysts also work with a 9.0% discount rate and assume the share count edges higher by about 0.11% per year over the next three years. In other words, most of the per share story in these models still hinges on earnings progression rather than heavy financial engineering.
Uncover why Rexel's fair value indicates a 16% potential upside to its current price, and why this gap could narrow quickly.
Exploring Other Perspectives
One alternate view says the real risk for Rexel is digital disintermediation. The most cautious analysts were already assuming only 4.9% annual revenue growth and earnings of about €863.7 million by 2029 before this €500 million equity raise. That is a much colder outlook than consensus. Use this funding news as a trigger to compare those very different narratives.
Explore 3 other Rexel fair value estimates, including one that suggests as much as 9% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rexel research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rexel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rexel's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rexel?
If Rexel's equity raise has you rethinking portfolio balance, it can help to line it up against other businesses with different risk and income profiles. You can do that quickly by scanning a few focused stock lists built from the same Simply Wall St data engine.
- For investors who care most about financial resilience, start with companies that pair strong balance sheets with solid fundamentals through this curated list of solid balance sheet and fundamentals (208 results).
- If value is your main filter, compare Rexel with companies that combine quality fundamentals and discounted valuations by reviewing this hand picked 196 high quality undervalued stocks.
- When income is a priority, you might prefer businesses that target higher yields and sturdier payouts, which you can find in this focused 169 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com