


How Investors May Respond To Universal Music Group (ENXTAM:UMG) AI And Brand Hires
- Universal Music Group has appointed Libby Bush as President of Global Brands and Commercial Partnerships and Òscar Celma as Senior Vice President of Applied AI and Machine Learning, creating new leadership roles focused on brand deals and data centric technology.
- These hires bring deep experience from CAA, Spotify, Pandora and other media groups, signaling a push to connect UMG's catalog with advertisers and to apply AI across music discovery and internal operations.
- This development raises questions about how Universal Music Group's broader investment narrative may be influenced by this new AI leadership role and the push into brand partnerships.
Scan how Universal Music Group's new AI and brand push compares with peers by reviewing the hand picked 37 profitable AI stocks that aren't just burning cash shaping the next phase of tech enabled media.
Universal Music Group Investment Narrative Recap
To own Universal Music Group, you need to believe its catalog, artist relationships and licensing reach can convert streaming, short form and brand usage into healthier earnings over time. The key near term swing factor is whether management can turn forecast earnings growth and planned cost savings into better margins, given current 2.5% profitability and a high P/E.
The biggest operational risk remains pressure on monetizing short form content and reliance on a handful of major artists, layered on top of high debt and a dividend that is not well covered by earnings. The new AI and brand hires look directionally helpful but do not materially change those near term risks today.
Òscar Celma’s appointment as Senior Vice President of Applied AI and Machine Learning is the clearest link to the existing catalyst around tech investment and Streaming 2.0 deals. Having a dedicated leader for recommendation and data science can support product teams as they work with platforms on premium tiers, personalization and potentially better ARPU.
For you as a shareholder, the execution test is whether Universal Music Group can use this AI capability to improve discovery for its roster, protect catalog value from generative AI disruption and support the targeted €250m in cost savings by 2026 or 2027. If those efforts stall or fail to offset weak short form monetization and artist cost inflation, the earnings growth story becomes harder to defend.
Universal Music Group's narrative projects €15.6b revenue and €1.8b earnings by 2029. This assumes 6.9% yearly revenue growth and an earnings increase of about €1.5b from €323.0m today.
Uncover why Universal Music Group's fair value indicates a 54% potential upside to its current price that could narrow quickly.
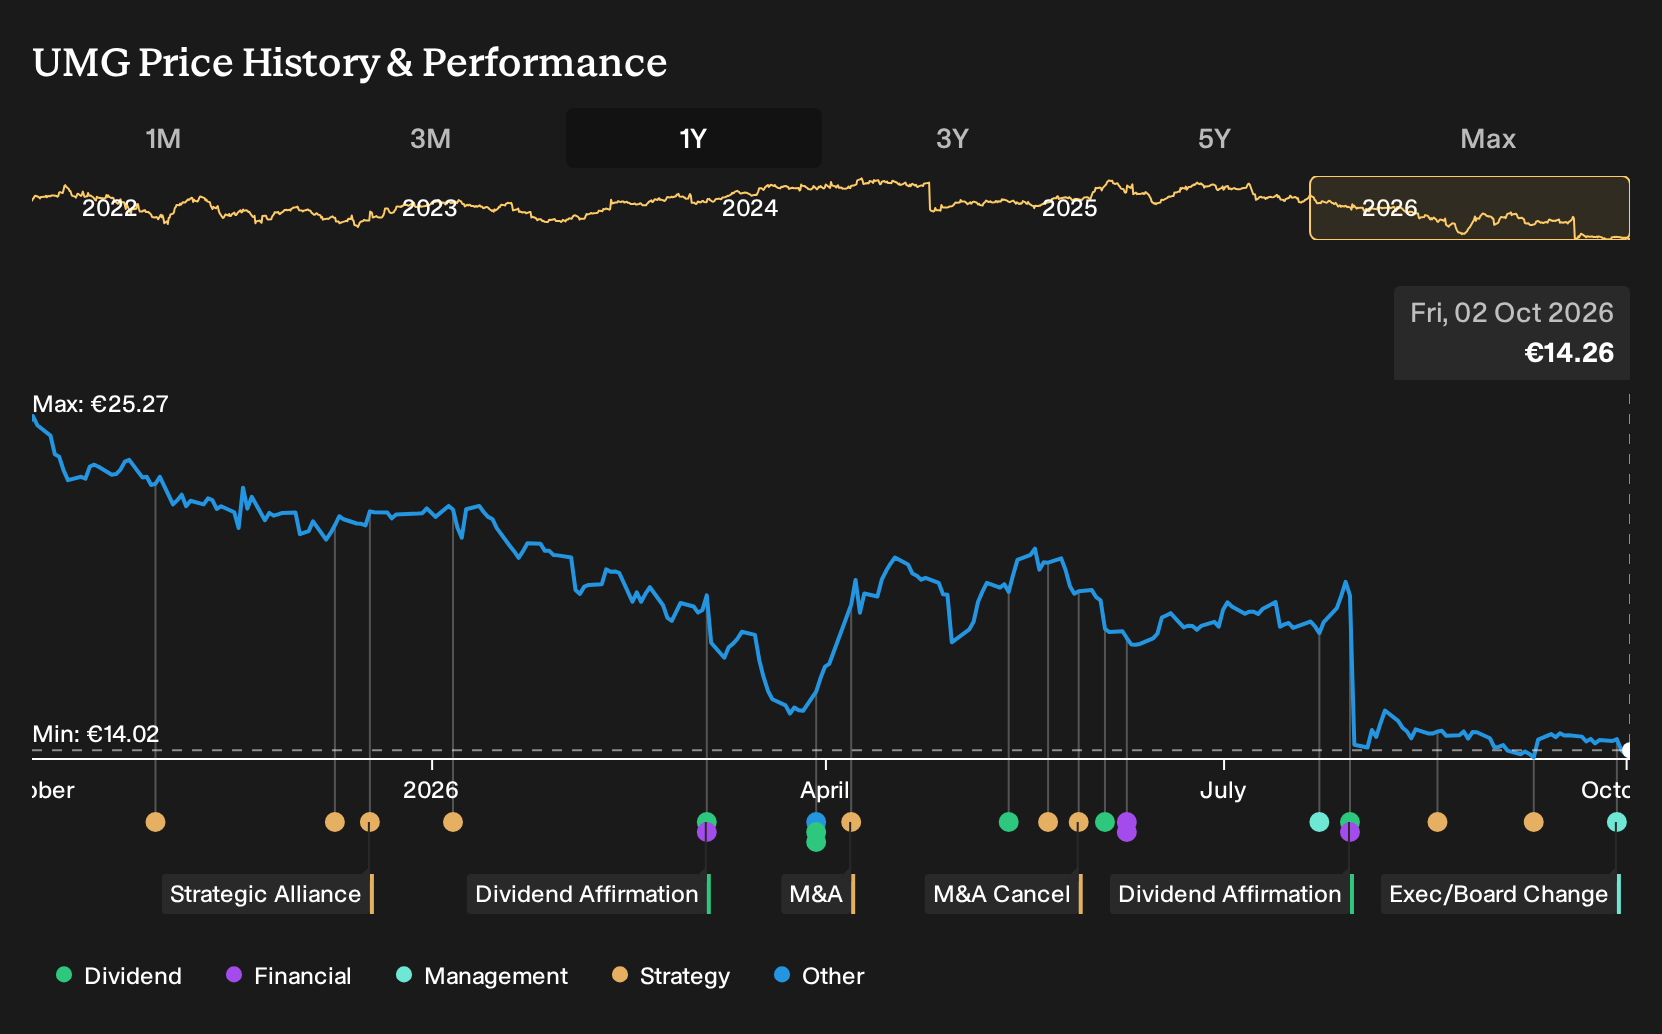
Exploring Other Perspectives
Some of the most optimistic analysts frame Libby Bush’s brand role as the real swing factor for Universal Music Group. Before this news, the bullish camp was already pencilling in €16.3b revenue and €2.6b earnings by 2029. That is far above consensus and could shift again as brand and AI plans become clearer.
Explore 6 other Universal Music Group fair value estimates, including one that suggests up to 145% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Music Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Music Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Music Group's overall financial health at a glance.
Looking For More Ideas Beyond Universal Music Group?
If you want to stress test your thesis on Universal Music Group against other opportunities, a quick tour through the Simply Wall St Screener can surface very different risk and reward profiles in a few minutes.
- If capital preservation sits at the top of your list, weigh Universal Music Group against 228 resilient stocks with low risk scores that score well on resilience and downside protection.
- For investors hunting for quality at a fair tag, line up Universal Music Group beside 196 high quality undervalued stocks that pair strong fundamentals with more modest expectations.
- Income focused readers can compare Universal Music Group's profile with 169 dividend fortresses that offer higher yields while still aiming to keep payouts supported by underlying cash generation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com