


Did AI Driven Disney+ Upgrades Just Shift Disney Stock Investment Narrative?
- Disney has moved to upgrade Disney+ with AI driven technology and fresh leadership, aiming to turn the platform into a central fan hub as media groups respond to cord cutting and weaker broadcast TV ratings.
- The focus on AI tools and platform leadership signals that Disney is treating streaming product quality and user experience as core operating priorities, rather than as side projects.
- This article examines how Disney's investment narrative intersects with its AI driven Disney+ overhaul and what that may mean for investors.
Scan how Disney's AI push on Disney+ compares with other media and tech players leaning into similar tools by reviewing our curated list of 37 profitable AI stocks that aren't just burning cash.
Walt Disney Investment Narrative Recap
Owning Walt Disney means believing the mix of streaming, sports and Experiences can keep pulling more value from its intellectual property. The near term hinges on whether Disney+ and ESPN direct to consumer can deepen engagement without relying only on price hikes. The fresh AI push on Disney+ fits that effort, but the impact on subscribers and churn is still unproven.
The biggest short term swing factor remains execution on the unified Disney+, Hulu and ESPN offering. The main risk is that higher content and technology spend, including AI tools and premium sports rights, weigh on margins if user growth or park and cruise demand softens. If the AI upgrades do not move the needle on usage, the news is more incremental than material.
The AI driven Disney+ overhaul lines up most clearly with Disney's plan to use a unified app and upgraded personalization to keep viewers watching longer and switching less. If that product work supports engagement, it can help the broader story that streaming, sports and Experiences together support earnings growth, with analysts currently forecasting 11.5% annual profit expansion.
That same announcement also interacts with cost and competitive risks. Heavy spending on technology and data infrastructure for Disney+ arrives alongside premium sports rights, Experiences expansion and rising competition from short form and user generated video. For you as a shareholder, the key question is whether these product upgrades help offset content inflation and margin pressure by improving retention and advertising yield over time.
Walt Disney's narrative projects US$112.8b revenue and US$13.1b earnings by 2029. This assumes 5.1% yearly revenue growth and an earnings increase of about US$1.9b from US$11.2b today.
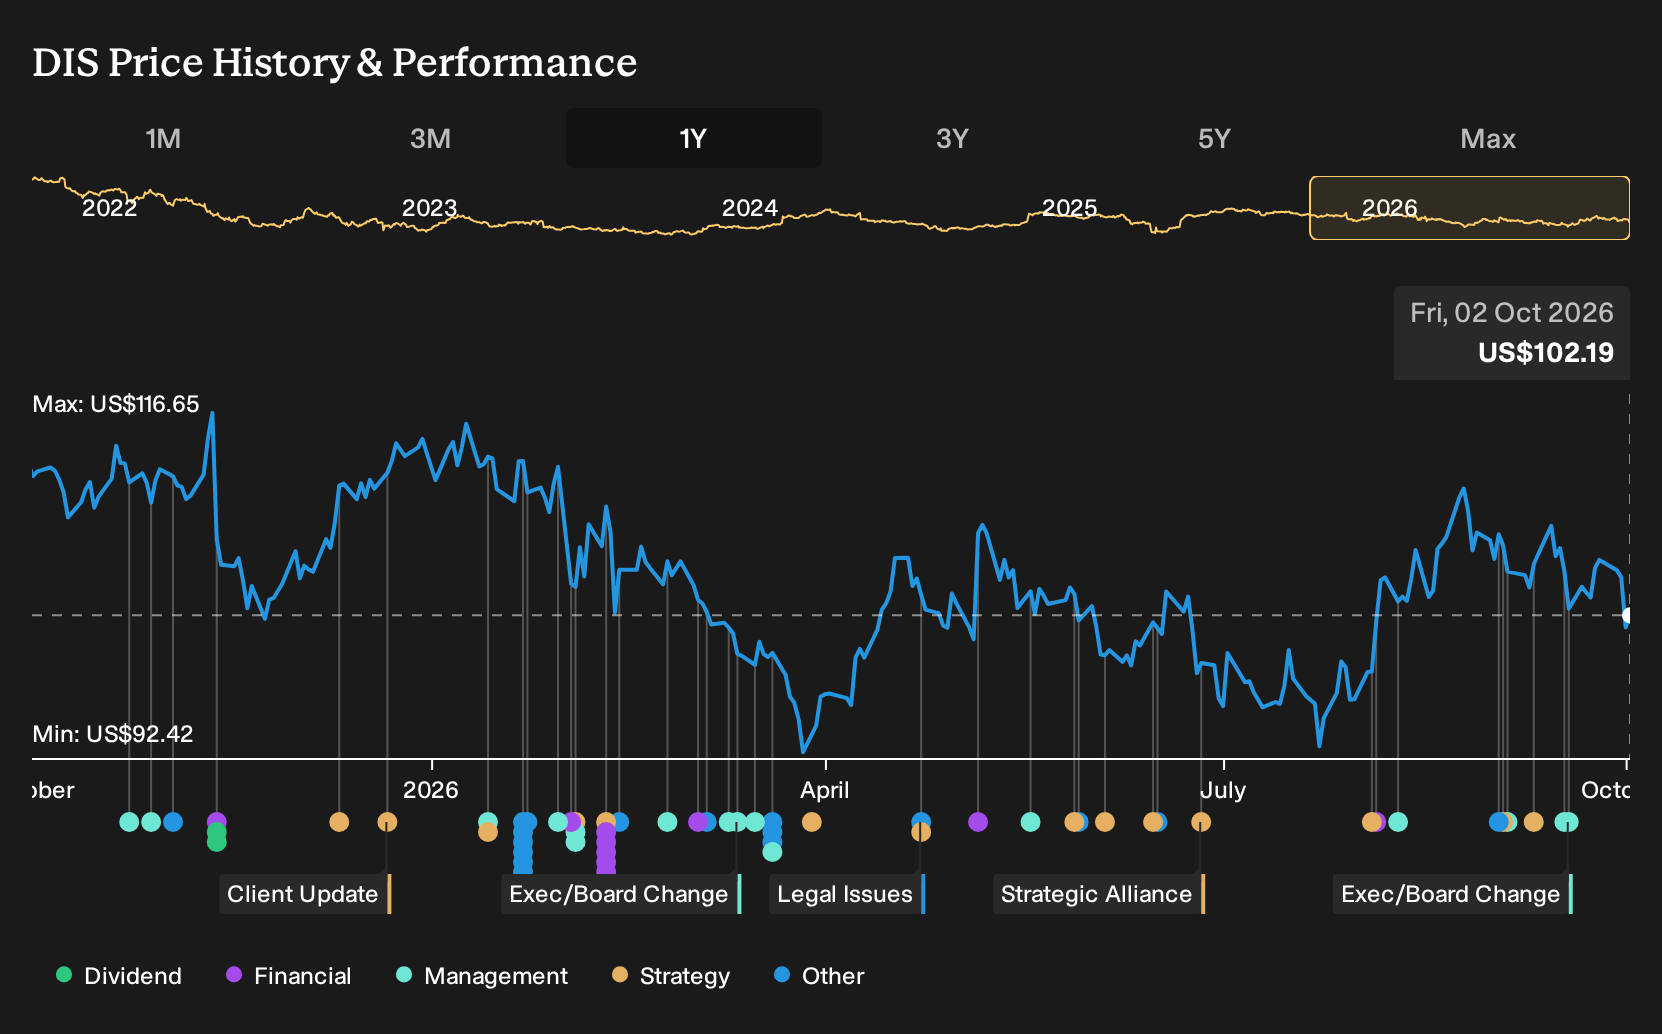
Uncover how Walt Disney's fair value indicates a 24% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community cluster between about US$124.86 and US$134.63, so everyday investors on Disney are working with a fairly tight band. These views do not yet reflect the AI heavy Disney+ plan or ESPN’s direct to consumer shift, which could reshape how you think about earnings resilience. Opinions clearly differ, so explore several of these community viewpoints before deciding where you land.
Explore 4 other Walt Disney fair value estimates, including one that suggests it could be worth just $124.86!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Walt Disney research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Walt Disney. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Walt Disney's overall financial health at a glance.
Looking for more Walt Disney style investment ideas?
If the Walt Disney story has sharpened your thinking and you want to broaden your watchlist, the Simply Wall St Screener can help you quickly spot other stocks that match different risk and return preferences.
- If capital preservation is high on your list, start with a set of businesses that screen for financial resilience and lower risk profiles through the 31 resilient stocks with low risk scores.
- If you care most about strong balance sheets and solid fundamentals, scan a targeted list of solid balance sheet and fundamentals (26 results) that can help you focus on sturdier companies.
- If you enjoy searching for underfollowed opportunities, look through a curated 19 high quality undiscovered gems that highlights smaller names with quality characteristics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com