


Does Sensitive Skin Launch Change The Bull Case For Bath & Body Works (BBWI)?
- Bath & Body Works recently launched Essentials, a hypoallergenic body care line for sensitive skin that includes dermatologist-approved body wash, ultra hydrating lotion and Eau de Parfum in three new close-to-skin scents at set price points.
- The Essentials franchise pushes Bath & Body Works further into dermatologically focused personal care, reflecting management’s effort to address sensitive-skin demand with higher-value formulas and routine-based usage.
- Next, the focus will be on how Bath & Body Works' broader investment narrative is influenced by this hypoallergenic Essentials launch.
Scan 19 high quality undiscovered gems to find other personal care and consumer brands that, like Bath & Body Works’ Essentials launch, are quietly building higher value through specialized product franchises.
What Is Bath & Body Works' Investment Narrative?
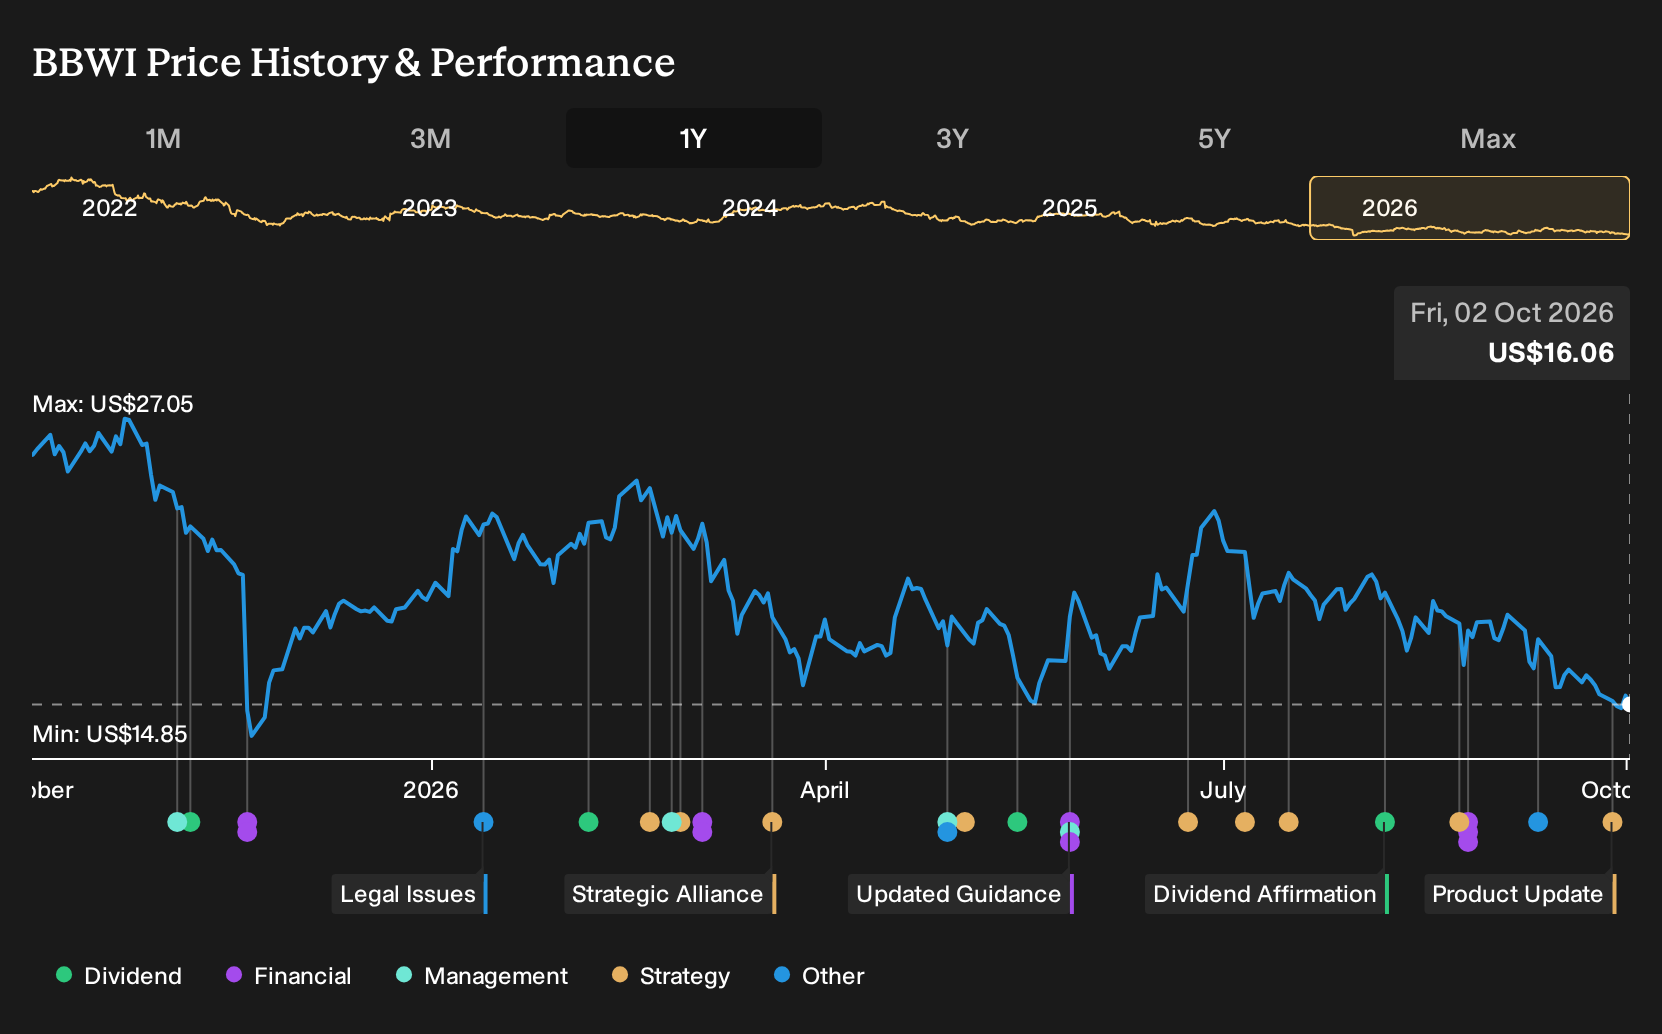
For Bath & Body Works, the core belief you would need as a shareholder is that this is still a powerful specialty fragrance retailer that can turn its product machine into consistent cash flow. The Essentials launch fits that story. It shows management trying to stretch the brand into sensitive skin and dermatologist-approved routines, which leans on existing fragrance strengths without heavy capital needs. The near term test is simple: Do shoppers accept higher-value formulas at set price points enough to stabilize demand after a share price that has fallen 35% over the past year?
In the short term, the bigger swing factors remain execution in core stores, pricing discipline and how much of that US$7.2b revenue base can be kept productive without aggressive discounting. Essentials probably does not change the debt picture, the negative equity position or the slower forecast growth profile on its own. It does, however, show a newer management team willing to push into more premium, routine-based usage, which matters if you think this P/E of 4.1x reflects overly low expectations.
Even so, anyone looking at Bath & Body Works as a value story still has to wrestle with ...
There's only one way to know the right time to buy, sell or hold Bath & Body Works. Head to Simply Wall St's company report for the latest analysis of Bath & Body Works's Fair Value.
Exploring Other Perspectives
Some analysts see a different risk for Bath & Body Works. They worry that softer body care demand and a pressured store base could keep revenue near US$7.2b and pull earnings down toward about US$594.8m by 2029. That is far more cautious than consensus. Use those pessimistic numbers as a reference point and test your own view of whether the Essentials launch might eventually shift expectations.
Explore 5 other Bath & Body Works fair value estimates, including one that suggests it could be worth just $17.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bath & Body Works research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bath & Body Works. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bath & Body Works' overall financial health at a glance.
Looking For More Ideas Beyond Bath & Body Works?
If you want to stress test your thesis on Bath & Body Works and widen your opportunity set, use the Simply Wall St Screener to compare it with other businesses that match the kind of balance sheets, dividends or value profile you care about most.
- For investors who want income that works harder than cash, check out 7 dividend fortresses and see which payers might deserve a closer look.
- If capital preservation comes first for you, use 31 resilient stocks with low risk scores to focus on companies with more resilient overall risk profiles.
- When you want financial strength to be the foundation of your watchlist, start with a list of solid balance sheet and fundamentals (26 results) and then compare those candidates to Bath & Body Works.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com