


Will Record Gold Drill Hit Change Lundin Gold's (TSX:LUG) Narrative
- Lundin Gold reported past near mine drilling results at Fruta del Norte in Ecuador, including the highest grade gold interval recorded at Bonza Sur and the discovery of the Quebrada Dorada epithermal vein system that extends the mineralized trend beyond eight kilometres.
- The concentration of multiple high grade intercepts close to existing infrastructure highlights how near mine exploration could influence Lundin Gold's future mine planning options, capital allocation choices, and operating life at Fruta del Norte.
- We will now examine how Lundin Gold's investment narrative could be affected by the high grade Bonza Sur drilling success.
Lundin Gold Investment Narrative Recap
To hold Lundin Gold, you need to be comfortable with a single flagship asset in Ecuador and an investment case that leans heavily on Fruta del Norte running efficiently. The recent Bonza Sur and Quebrada Dorada drill results speak directly to that. Higher grade hits around existing workings support the idea that near mine exploration could matter more to the short term story than new greenfield projects.
The biggest swing factor near term stays simple. It is how consistently Lundin Gold converts its current resource base into production and free cash flow while funding exploration, dividends and sustaining capex. The key risk is that all this remains tied to one jurisdiction and one mining complex, so any operational, social or regulatory setback at Fruta del Norte could hit both output and the balance sheet quickly.
The most relevant operational update is the concentration of very high grade intercepts at Bonza Sur. You now know that drill hole BLP 2026 553 returned 204.26 g/t Au over 3.05 m, including a very large grade sub interval, and that this is described as the highest grade interval recorded at the deposit. In practical terms, that puts more focus on how quickly Lundin Gold can tighten drill spacing and convert these zones into mineable inventory.
Quebrada Dorada adds another layer. The new epithermal system extends the mineralized trend on the Fruta del Norte property to more than eight kilometres and remains sparsely tested. For catalysts, the real tell will be follow up drilling and any future resource definition along this trend. For risk, the bigger footprint concentrates even more value in Ecuador, so investors may want to track community relations, permitting and cost pressures as the drilling ramps up.
Lundin Gold's narrative projects $2.6b revenue and $1.1b earnings by 2029, which implies 8.2% yearly revenue growth and an earnings increase of about $165m from $935.1m in the most recent period.
Uncover why Lundin Gold's fair value indicates a 9% potential upside to its current price, before that discount starts to close.
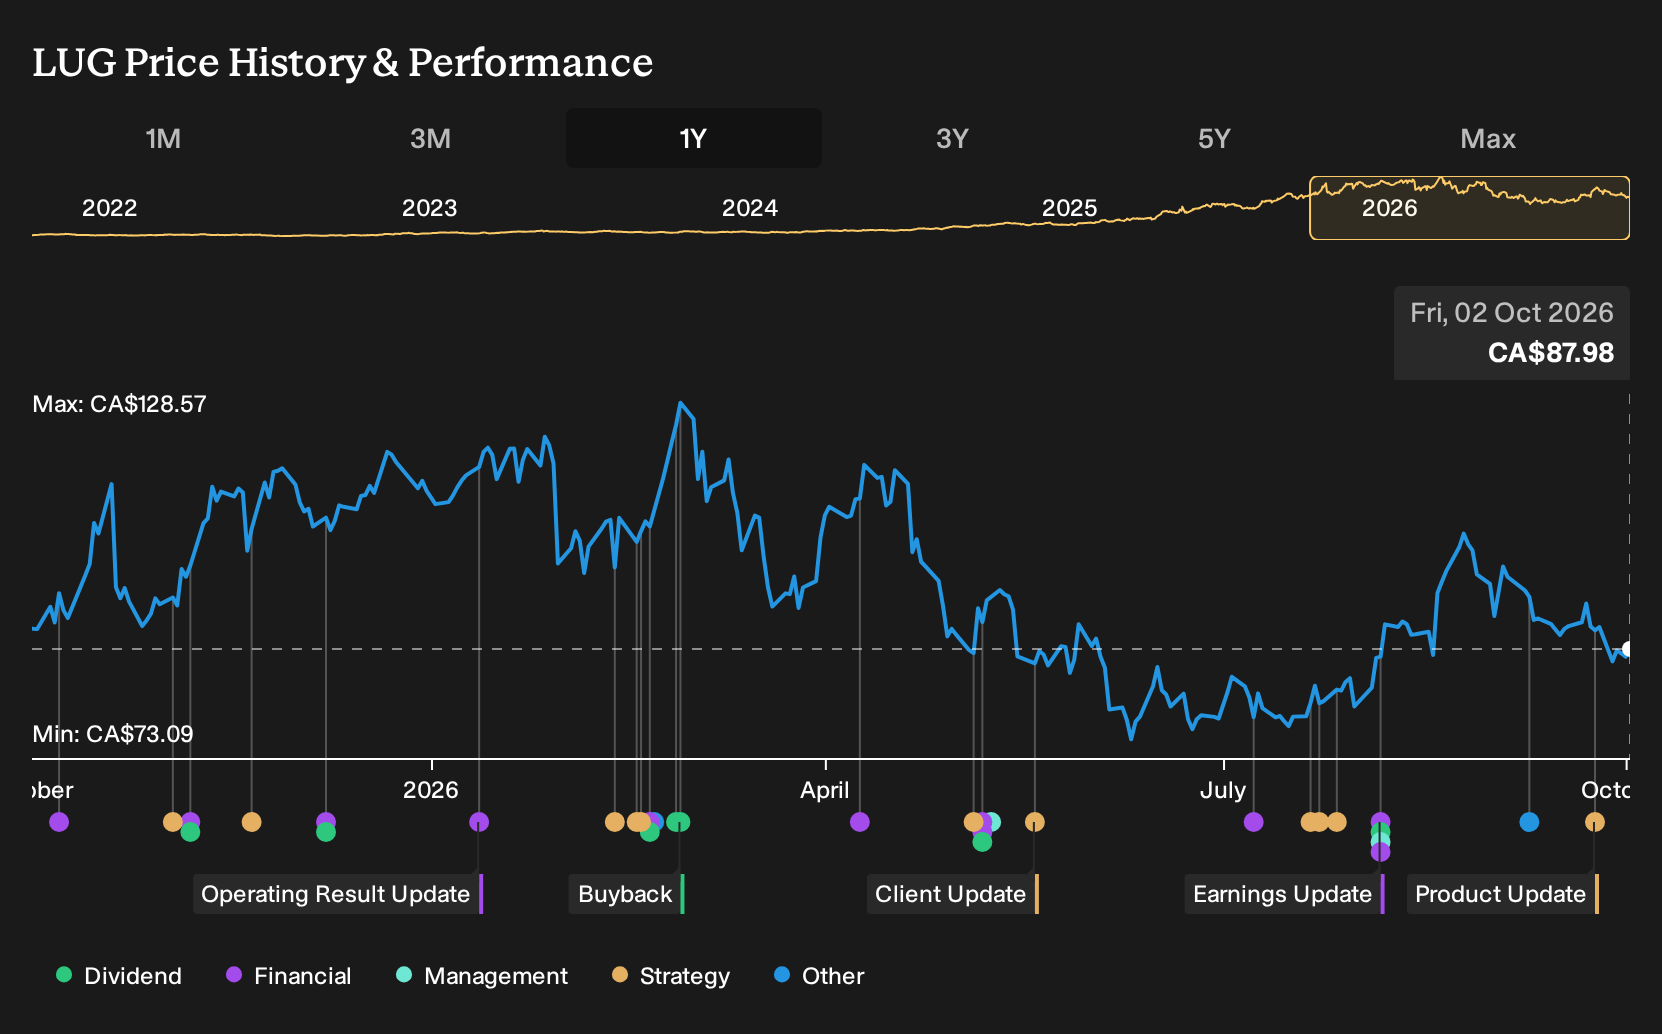
Exploring Other Perspectives
Some of the most optimistic analysts focus on throughput expansion as the real swing factor for Lundin Gold, not just higher grades at Bonza Sur. Before this drilling update, the bullish camp was already sketching out $3.2b in 2029 revenue and $1.3b in earnings. You now have fresh information that could reshape both stories.
Explore 3 other Lundin Gold fair value estimates, including one that suggests there could be as much as 44% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Lundin Gold research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lundin Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lundin Gold's overall financial health at a glance.
Looking For More Ideas Beyond Lundin Gold?
If the Lundin Gold story has sharpened your thinking around quality, risk and concentration, it can be useful to compare it with a broader set of potential holdings using the Simply Wall St Screener. That way you can see how other businesses stack up on income, quality and balance sheet strength before deciding where to focus your attention next.
- If reliable income is high on your priority list, scan for companies that resemble income workhorses through 1 dividend fortresses and see which ones match your yield and payout preferences.
- For readers who care most about safety first, stress test your watchlist against 8 resilient stocks with low risk scores and look for businesses that align with your tolerance for volatility and financial risk.
- To round out your research with quality names that may fly under the radar, widen your search using 9 high quality undiscovered gems and compare their fundamentals to Lundin Gold.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com