


Whitecap Resources (TSX:WCP) Could Be 12% Undervalued As Veren Synergies Build
Why Whitecap Resources Stock Is Back in Focus
Whitecap Resources (TSX:WCP) has turned investor attention to its integration of Veren assets, with early operational synergies, lower costs, and better capital efficiency reshaping how the business generates cash and manages profitability.
On the price side, Whitecap Resources has moved to CA$18.0 per share after a 1-day share price return of 1.52%. The 90-day share price return of 22.28% and year-to-date gain of 53.98% indicate that momentum has been building rather than fading.
Scan other energy producers showing similar cost and cash flow momentum using our hand picked 6 high quality undervalued stocks.
Whitecap Resources now trades at a clear discount to both analyst targets and an intrinsic value estimate after a sharp run in the share price. Is that a sensible margin of safety, or is the market flagging real risks?
Most Popular Narrative: 12% Undervalued
Whitecap Resources last closed at CA$18.00, while the most followed narrative pegs fair value around CA$20.53. The gap rests on how much weight you put on free cash flow, premium reservoirs, and balance sheet flexibility.
Successful integration of Veren assets is resulting in early operational synergies, cost reductions, and improved capital efficiency, which are expected to unlock further sustainable cost savings and margin expansion over the next 6 to 12 months, directly supporting higher future earnings and free cash flow.
See why 156 investors see Whitecap Resources as 12% undervalued.
Result: Fair Value of CA$20.53 (UNDERVALUED)
Still, Whitecap Resources carries clear pressure points, including commodity price sensitivity and the risk that heavy drilling and debt leave less room if conditions change.
Find out about the key risks to this Whitecap Resources narrative.
Another Angle On Whitecap Resources Valuation
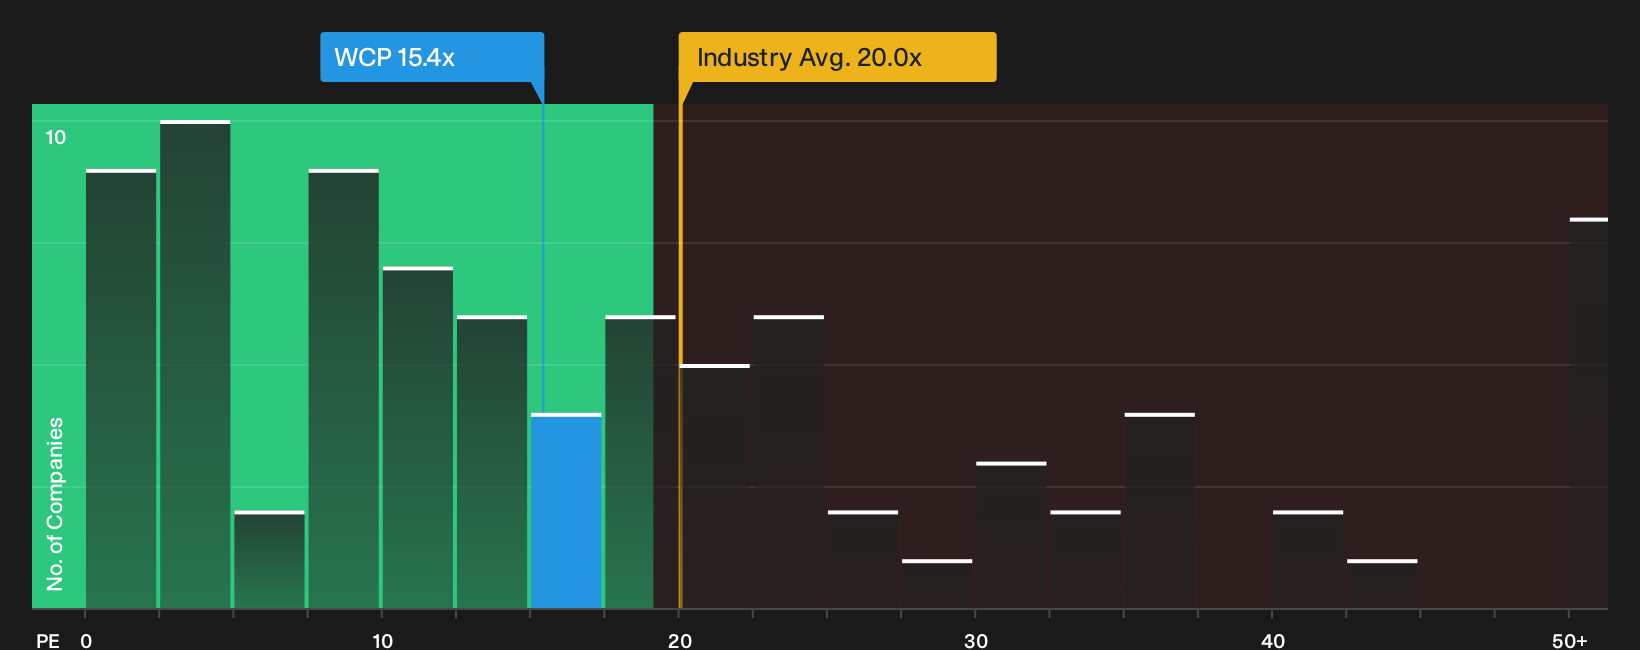
On simple earnings multiples, Whitecap Resources looks less generous than the 12% undervalued narrative suggests. The shares trade on a P/E of 15.4x, slightly above an estimated fair ratio of 14.4x. That headline multiple remains well below both peer and wider Canadian Oil and Gas industry averages around 34.5x and 20x. This could reflect a genuine mispricing, or it may indicate that investors are already accounting for execution and commodity risk.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Whitecap Resources leaves you unsure, that is the point. The story includes tension between clear risks and real upside potential. Weigh that for yourself by going straight to the source data through 3 key rewards and 1 important warning sign.
Looking for more Whitecap Resources style investment ideas?
Do not stop with Whitecap Resources if you want a fuller opportunity set. Use the Simply Wall Street Screener to scan for other stocks that fit your approach and avoid leaving potential ideas on the table.
- Target quality income by reviewing companies in the 1 dividend fortresses that combine higher yields with a focus on durability.
- Hunt for potential mispriced opportunities by scanning the 9 high quality undiscovered gems where fundamentals and market attention are not always aligned.
- Prioritise resilience by filtering for businesses in the 8 resilient stocks with low risk scores that score well on balance sheet strength and risk factors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com