


How Investors Are Reacting To Coeur Mining (CDE) Bigger 2026 Exploration Plans
- Coeur Mining reported past 2026 exploration updates at New Afton and Rainy River, planning a record US$158 million program that includes US$24 million for New Afton and US$18 million for Rainy River, with drilling extending key gold and copper zones and confirming mineralization across multiple targets.
- The company is allocating more than double its prior year exploration spend to convert and grow resources, using dense infill and expansion drilling to test continuity, extend mineralized systems and probe potential open pit connectivity between Rainy River zones.
- We will now look at how Coeur Mining's heavier 2026 exploration spend and drilled extensions could influence the broader investment narrative.
Coeur Mining Investment Narrative Recap
To own Coeur Mining, you need to be comfortable with a capital intensive miner that leans heavily on exploration to sustain mine life and production. The record US$158 million exploration program in 2026 reinforces that this is an exploration led operating story rather than a pure cost cutting one. The near term focus remains execution at existing sites and keeping grades and throughput on track.
The most important short term swing factor is whether ongoing projects and drilling translate into stable output without straining cash generation. The biggest risk is that heavy spending, past shareholder dilution and any permitting or development delays cause financial pressure without enough resource conversion to offset it. This update does not materially change that risk reward balance.
The recent exploration update around the K Zone at New Afton is the operational highlight that matters most here. Coeur Mining flagged a US$24 million 2026 exploration budget at New Afton with 68 kilometers of core drilling aimed at expanding and upgrading the maiden K Zone resource. Management reported infill drilling confirming mineralization and expansion holes extending it more than 300 meters.
For catalysts, the key question is whether those K Zone and East Picrite results, combined with Rainy River underground and open pit drilling, can support mine life and potential production profiles enough to justify the higher capital spend. The risk is that resource growth or conversion falls short while cash requirements stay high, which would keep pressure on valuation and future funding choices.
Coeur Mining's current analyst storyline points to revenues of US$5.1b and earnings of US$1.5b by 2029, based on an assumed 17.0% yearly revenue growth rate and an earnings increase of roughly US$649.6m from US$850.4m today.
Uncover why Coeur Mining's fair value indicates a 36% potential upside to its current price, before that discount to Coeur Mining's shares starts to close.
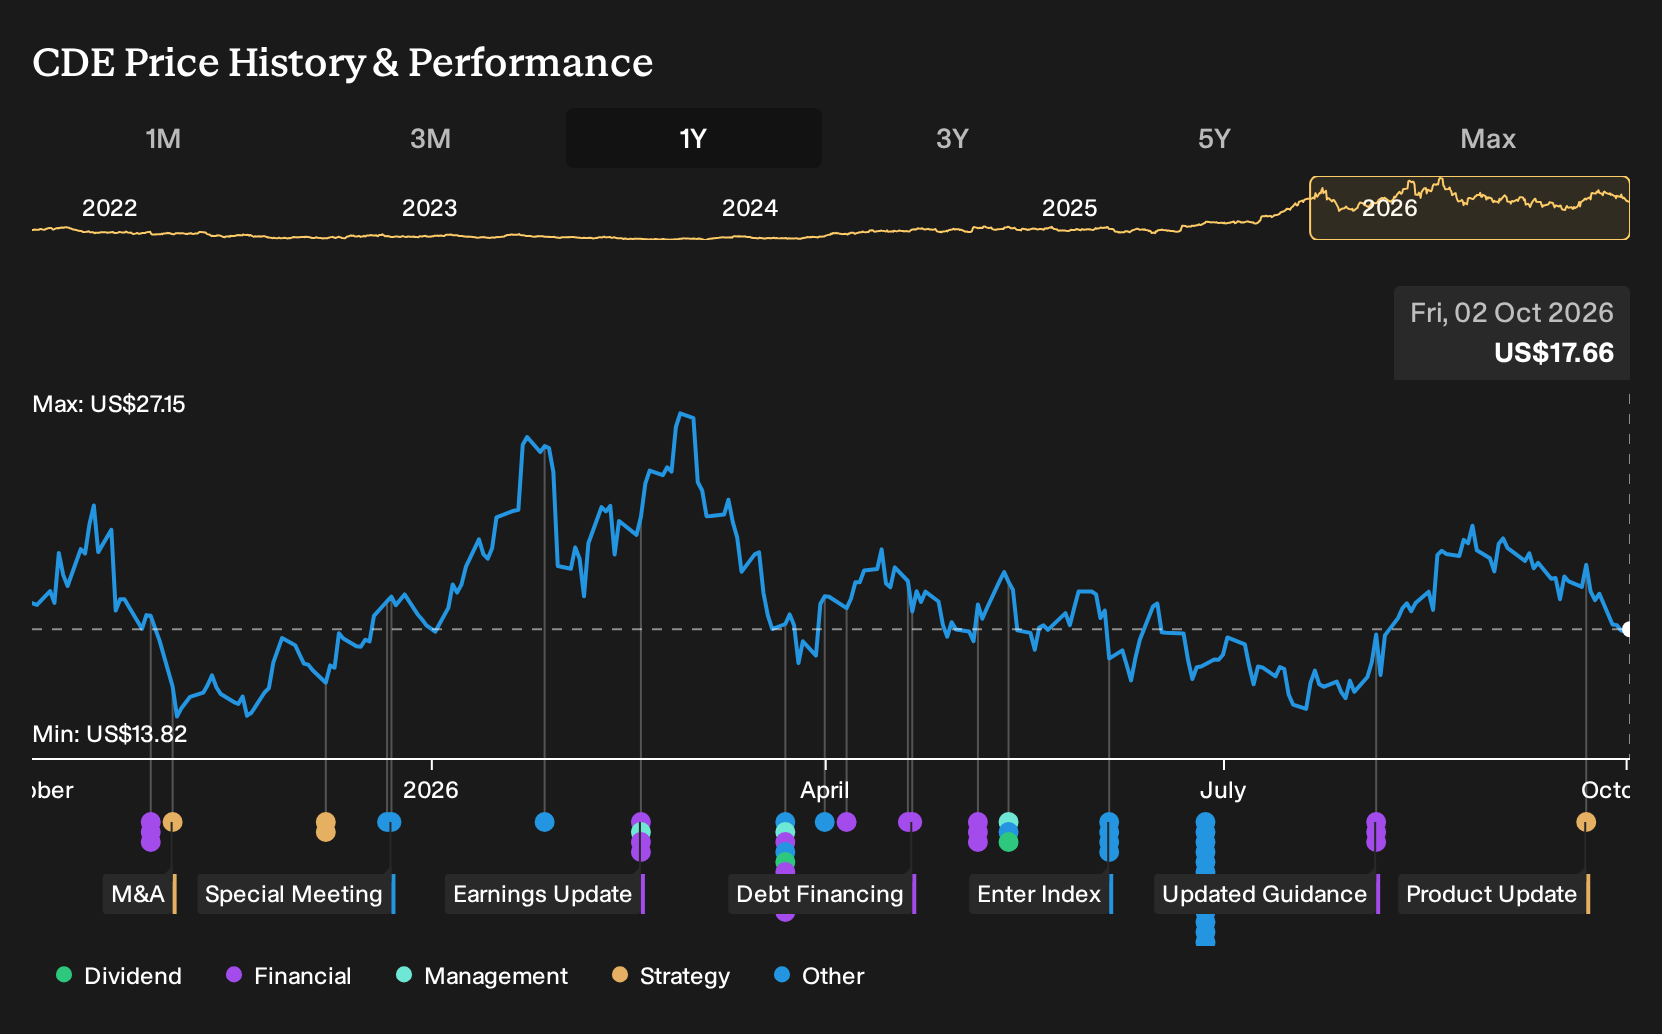
Exploring Other Perspectives
One alternate, more optimistic take focuses on Coeur Mining turning record exploration into faster earnings expansion. The most bullish analysts were already penciling in revenue of about US$5.9b and earnings near US$2.5b by 2029, compared with US$5.1b and US$1.5b in the baseline view. This fresh New Afton and Rainy River data could prompt those expectations to shift again. Treat it as one of several viewpoints to explore, not the final word.
Explore 5 other Coeur Mining fair value estimates, including one that suggests potential upside of as much as 84% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Coeur Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Coeur Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coeur Mining's overall financial health at a glance.
Looking for more investment ideas beyond Coeur Mining?
Once you have a view on Coeur Mining, it can help to widen the lens and see how other businesses stack up on value, income and balance sheet strength using the Simply Wall St Screener.
- For investors hunting for potential mispricing, start with a curated set of 31 high quality undervalued stocks that combine quality fundamentals with discounted share prices.
- If resilience matters most to you, focus on a 31 resilient stocks with low risk scores that screens for companies with more stable risk profiles and fewer red flags.
- Income focused readers can zero in on a 7 dividend fortresses targeting firms with higher yields that may support a steadier stream of payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com