


3 Greek Energy Stocks Investors Are Watching As Power Prices Stay High
Greek inflation running at 5.1% and energy costs jumping 25.4% year on year have turned power and utilities from a dull backdrop into the main story for local assets. Elevated prices can hurt many sectors, yet they can also strengthen some balance sheets tied closely to domestic energy markets. This article breaks down how three Greek energy producers and utilities exposed to these trends may be positioned in the current surge.
The three stocks covered next are only a starting sample, as the wider screen of Greek energy producers and utilities surfaced 3 more listed companies with equally compelling narratives that are not unpacked in this article.
If you want to identify and analyze the full field of Greek power, fuel and grid operators tied to domestic pricing, head straight to the Greek Energy Producers & Utilities Benefiting from Elevated Energy Prices screener.
HELLENiQ ENERGY Holdings (ATSE:ELPE)
HELLENiQ ENERGY Holdings plugs directly into the screener’s theme through its mix of refining, fuel marketing and power generation across Greece and Southeast Europe, giving investors exposure to domestic energy pricing as well as regional demand for oil products and electricity.
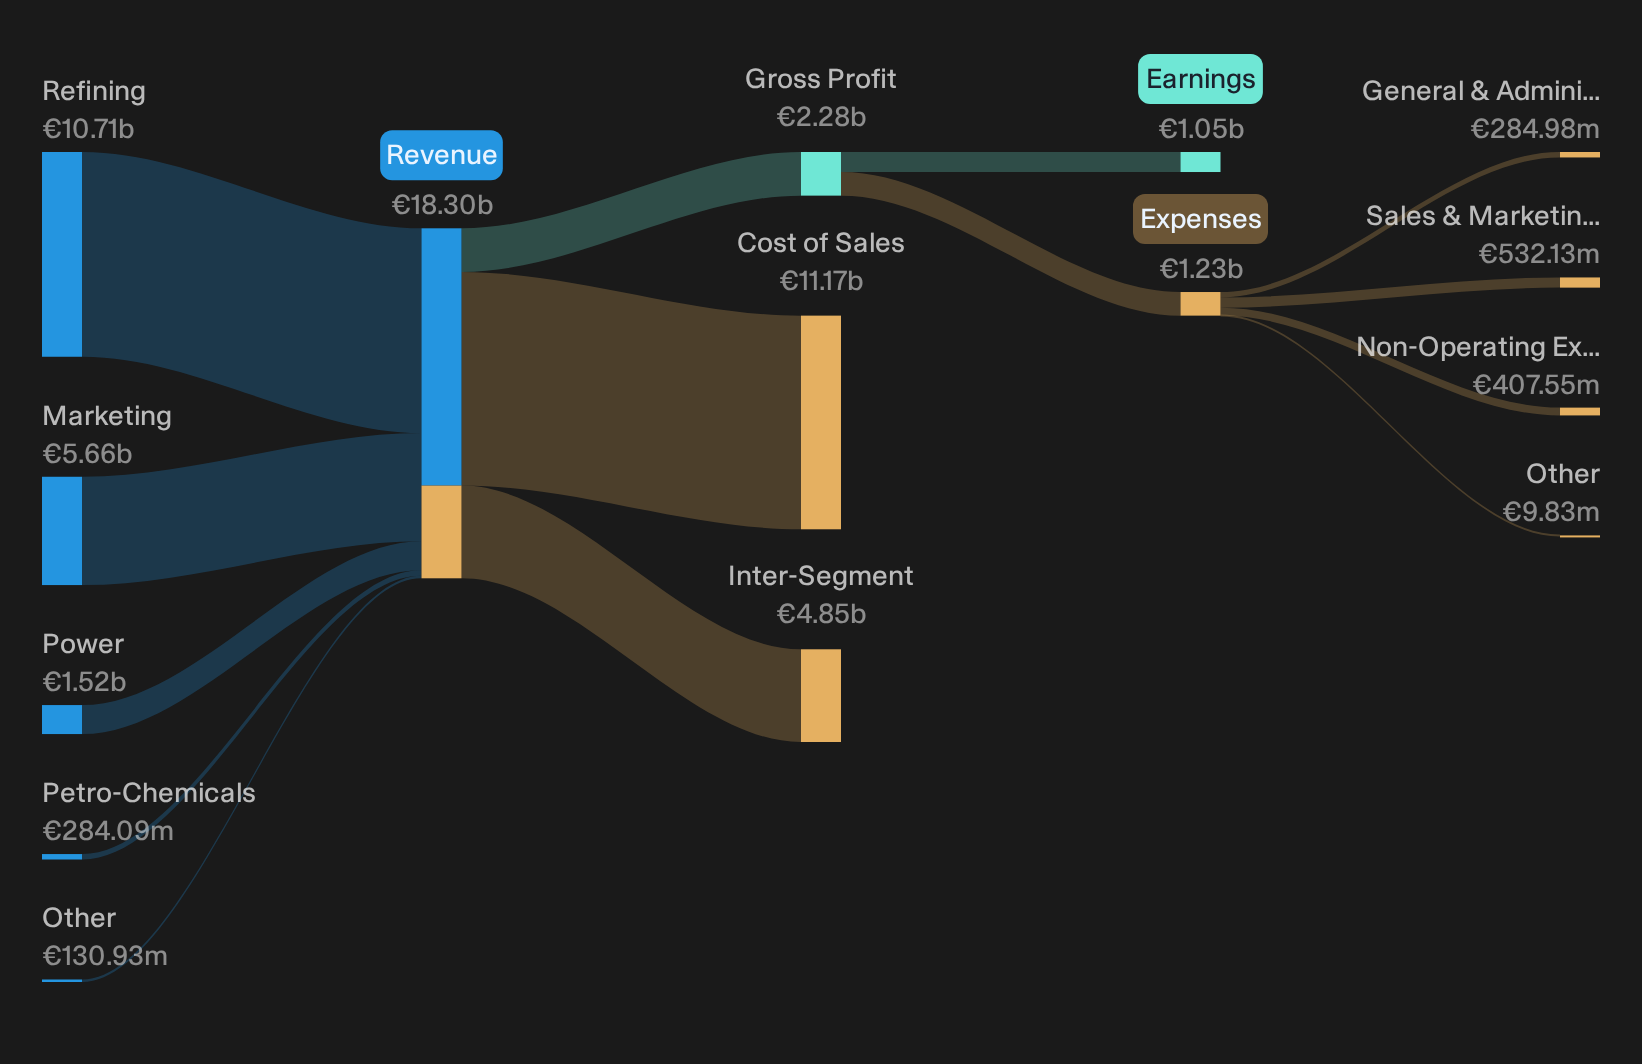
HELLENiQ ENERGY Holdings is an integrated Greek energy group, with most revenue coming from refining at about €10.7b, supported by €5.7b from marketing, €1.5b from power and €0.3b from petrochemicals, and it carries a market value of roughly €5.6b.
"The Geneva trading platform, improved supply chain and procurement, and strong export capabilities are already contributing to margin overperformance versus benchmarks and can continue to support realized refining margins and net income even when benchmark refining margins fluctuate."
What investors need to watch now is how one less visible pressure on future cash generation ultimately shapes those margins and earnings resilience.
That pressure point is exactly where the full narrative for HELLENiQ ENERGY Holdings picks up, spelling out how HELLENiQ ENERGY Holdings could see those refining gains amplified or quietly capped.
Motor Oil (Hellas) Corinth Refineries (ATSE:MOH)
Motor Oil (Hellas) Corinth Refineries is a Greek refiner and fuel marketer tied closely to domestic energy pricing through its refining, fuel retail, power and gas operations. It has about €16.3b recorded under Other and segment adjustments, and a market value near €7.3b.
Greek energy inflation of 25.4% puts Motor Oil (Hellas) Corinth Refineries squarely in focus because its refining and fuel activities are tightly linked to oil product prices and local energy conditions. Investors watching Greek inflation may care most about what happens if a single key assumption about refining margins breaks.
If that refining margin assumption is the real swing factor, the 2 key rewards and 4 important warning signs (1 is major!) and see how Motor Oil (Hellas) Corinth Refineries could surprise either way.

Public Power (ATSE:PPC)
Public Power is the purest expression of this Greek energy theme, with an electricity, networks and retail footprint that directly rides higher domestic power prices and regulated returns. This is exactly why the next comment from management carries extra weight for this list.
"Acceleration of renewables and flexible generation, with 9.9 gigawatts of renewables and flexible capacity already in place and 6.7 gigawatts either under construction, ready to build or in tender, positions Public Power to shift more of its output to lower cost generation, which can support adjusted EBITDA and net income resilience."
The real swing factor is how one less visible shift in its mix between Greek power pricing, regulation and funding costs ultimately feeds through to margins.
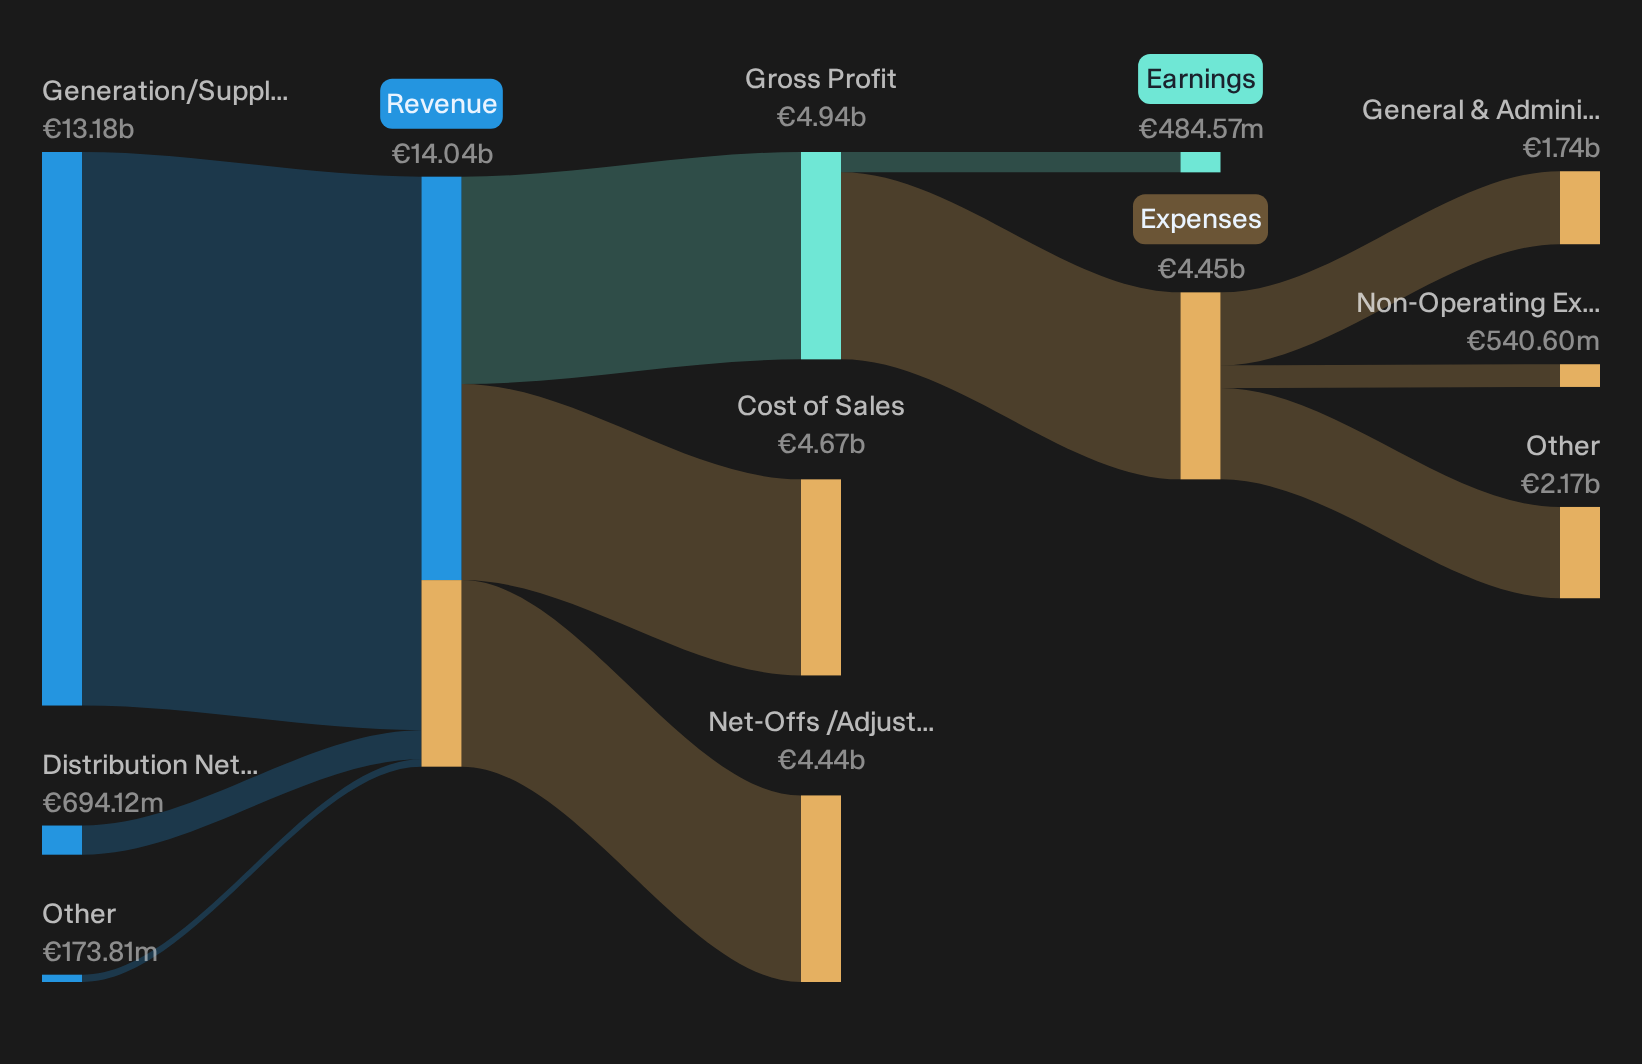
Public Power runs an integrated electricity and infrastructure platform across Greece and neighboring markets, with about €13.2b from generation and supply and roughly €700 million from the distribution network, and it carries a market value near €13.4b.
That mix shift is exactly where the full narrative for Public Power pulls back the curtain on how Public Power might balance regulated returns, funding costs and Greek pricing to accelerate or stall.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every chart looks like a breakout, early entry is gone and prices are already flying. Scan these under-the-radar lists and consider acting while they still appear early in their move.
- Look for cash-generating opportunities that still appear overlooked by the crowd by running the list of solid balance sheet and fundamentals (208 results) while it may still matter, before sentiment focuses on the next theme.
- Review companies linked to demand in electrification and infrastructure by checking the curated 40 power grid technology and infrastructure stocks before additional capital potentially narrows the most attractive entry points.
- Monitor gold producers when they are quietly resetting costs and project pipelines by reviewing the hand-picked 36 elite gold producer stocks before more short-term traders become active in the space.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com