


Earnings Beat Might Change The Case For Ero Copper Stock
- Ero Copper reported Q2 FY26 earnings per share above analyst estimates, reflecting operational performance across its Brazilian mining operations and by-product contributions.
- The earnings result points to cost control and more consistent execution at Caraíba and related assets, which could influence how investors assess Ero Copper’s ability to manage future expansion projects.
- This analysis examines how Ero Copper's investment narrative may shift in light of its Q2 earnings per share coming in above expectations.
Scan how Ero Copper’s Q2 beat fits within the wider copper story by reviewing our hand picked 16 top copper producer stocks focused on operational execution and balance sheet strength.
Ero Copper Investment Narrative Recap
To own Ero Copper, you need to be comfortable with a tight focus on Brazilian mines and the idea that operational upgrades can keep costs in check even as ore grades shift. The Q2 earnings beat supports that belief by pointing to better execution and cost discipline. The near term hinge remains delivery on production plans across Caraíba, Tucumã, and Xavantina without slipping on unit costs.
The biggest risk still sits with execution. Repeated guidance resets, lower grade feed at Caraíba, and the complexity of ramping multiple assets leave little room for operational missteps. The Q2 result helps sentiment but does not erase those concerns. Any stumble on volumes, recoveries, or project timing could quickly pull focus back to those weak spots.
With no fresh company announcements tied directly to this Q2 release, the reference point remains Ero Copper’s broader plan to transition its Brazilian portfolio into a higher throughput, more mechanized operation. That roadmap underpins the key catalyst you care about: more consistent output at Tucumã and Xavantina, combined with Caraíba upgrades that stabilise grades and recoveries.
Viewed through that lens, the Q2 earnings beat mainly acts as a progress check on execution. It hints that preventive maintenance, technology rollouts, and cost initiatives are feeding through operationally. The catalyst is sustained delivery of those gains over several quarters. The risk is that country concentration, cost inflation, or project delays interrupt that trajectory before it fully shows up in cash generation.
Ero Copper Consensus Outlook And Valuation Markers
Ero Copper's narrative projects $1.3b in revenue and $455.5 million in earnings by 2029. That profile lines up with analyst assumptions of 8.1% yearly revenue growth and an earnings increase of about $144 million from $311.3 million today.
Uncover why Ero Copper's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
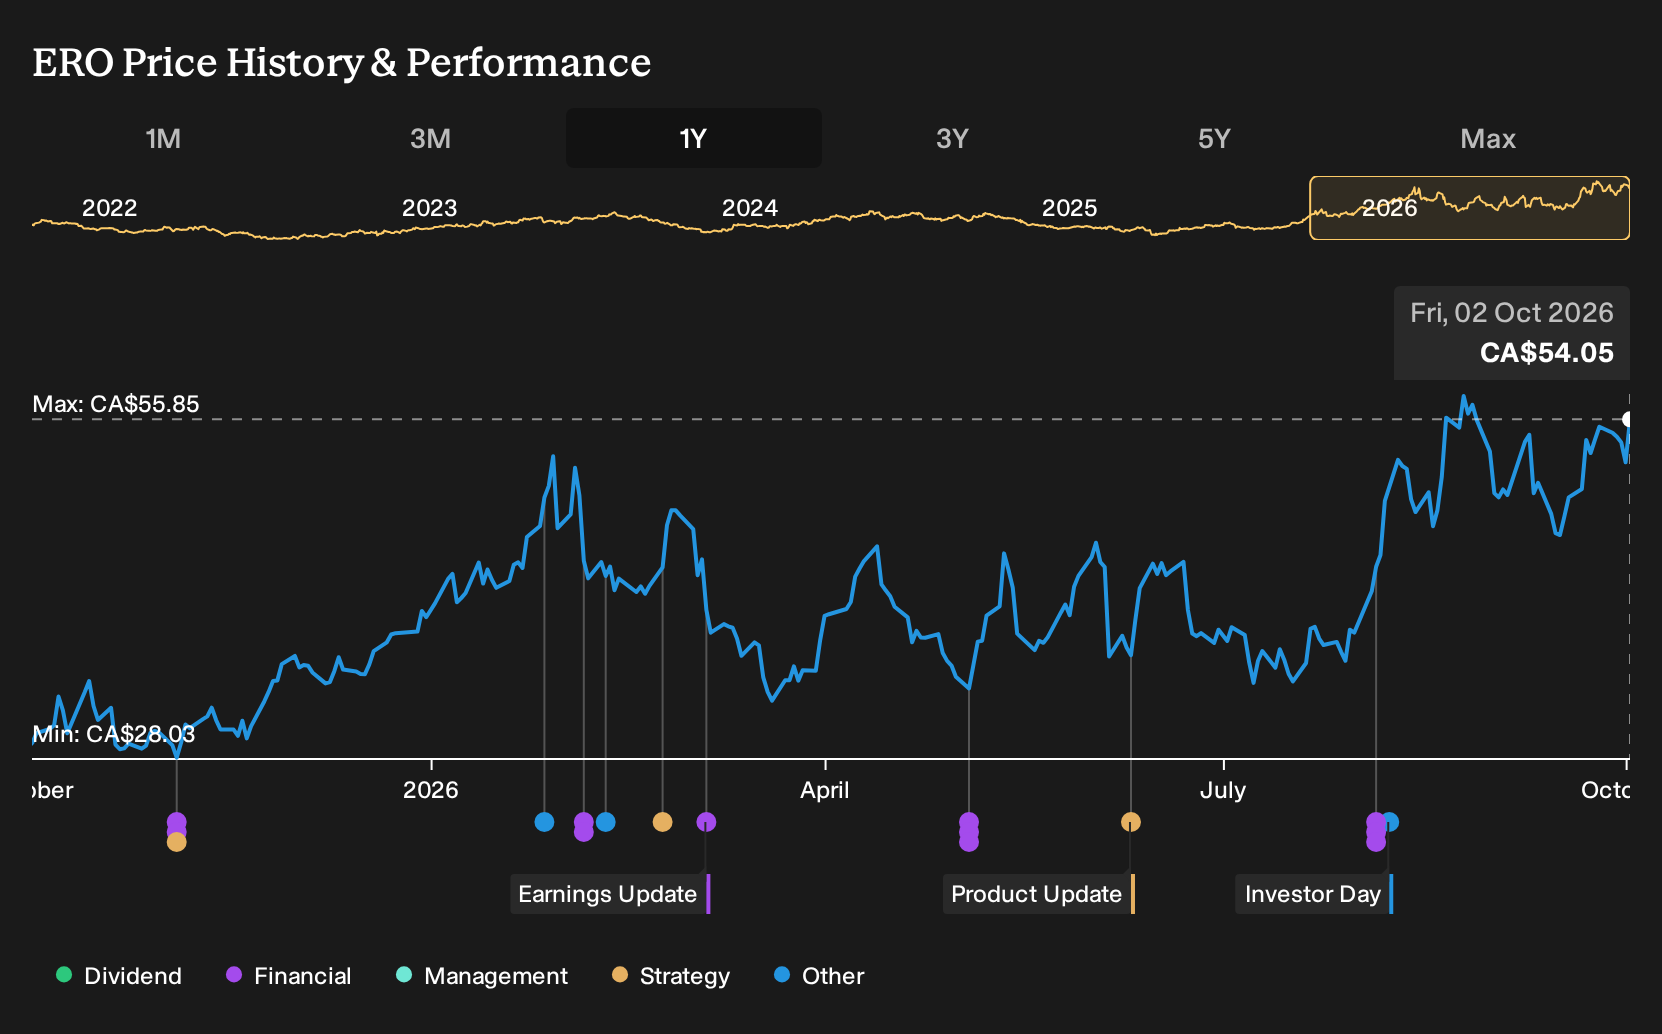
Exploring Other Perspectives
One alternate angle on Ero Copper focuses on the risk that high grade gold concentrate stockpiles at Xavantina are temporary, which could leave a hole in earnings once they run off. The most cautious analysts were only assuming about 5.7% yearly revenue growth and roughly $443.2 million in 2029 earnings. Those forecasts came before this Q2 beat, so use them as a reference point and explore how views might shift as new results come through.
Explore 4 other Ero Copper fair value estimates, including one that suggests there could be as much as 58% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ero Copper research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ero Copper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ero Copper's overall financial health at a glance.
Looking for more investment ideas beyond Ero Copper?
If the Ero Copper story has sharpened your thinking, use that same framework to scan other opportunities where balance sheets, cash flow and risk profiles line up with your own comfort zone.
- If capital preservation comes first for you, start with a curated set of resilient businesses by reviewing 8 resilient stocks with low risk scores, which aims to keep volatility in check.
- For investors hunting for mispriced opportunities, widen your watchlist with a focused screen of 6 high quality undervalued stocks that combines quality fundamentals with more modest expectations baked into the price.
- When you want sturdier foundations behind each ticker you research, build a shortlist from a list of solid balance sheet and fundamentals (7 results) to see which companies pair financial strength with durable business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com