


How Investors May Respond To Cooper (COO) Opening New Eye Care Hub
- Cooper Companies recently opened The Vision Centre in Southampton, England, a global hub that combines R&D, clinical work, pilot manufacturing, and commercial teams to speed contact lens product development at CooperVision.
- The Vision Centre weaves data science, advanced digital tools, and emerging AI capabilities into CooperVision’s day to day work, which could affect how quickly new eye care products move from early research into commercial launch.
- We will now look at how Cooper Companies' investment narrative could shift as The Vision Centre starts shaping product development.
See how Cooper Companies' push into AI driven eye care compares with other healthcare stocks making similar moves by reviewing our hand picked 35 healthcare AI stocks in one place.
Cooper Companies Investment Narrative Recap
To own Cooper Companies, you need to believe its contact lens engine can keep compounding through premium products like MyDAY while the weaker CooperSurgical arm does not drag too hard on group results. The Vision Centre speaks directly to that belief. It concentrates R&D and clinical work in one place, which could help CooperVision respond faster to shifts in demand and product mix.
The near term swing factor still looks like execution on the Clariti to MyDAY transition and conversion of fitting and trial activity into repeat orders. The biggest risk remains softer industry growth and pricing pressure, especially in Asia Pacific, which could dilute the benefits of any faster product rollout coming out of The Vision Centre.
The Vision Centre matters most when set against the MyDAY rollout story. Capacity constraints have already been addressed and management has leaned into premium daily lenses, new fittings, and private label deals. A more integrated hub for research, pilot manufacturing, and commercial teams could support smoother new product introduction and lessen the revenue lumpiness seen during portfolio transitions.
No other major announcements sit alongside this opening right now. As a result, the focus stays on execution risk. If pricing pressure persists and Clariti volumes remain soft, even well designed products coming through The Vision Centre could struggle to offset slower market growth. For you as an investor, the question is whether Cooper Companies can translate this physical investment into steadier conversion of its pipeline while keeping margins resilient.
Cooper Companies' current analyst narrative points to revenues of US$4.9b and earnings of US$782.6m by 2029, based on expectations of 4.7% yearly revenue growth and earnings rising by about US$212m from US$570.3m today.
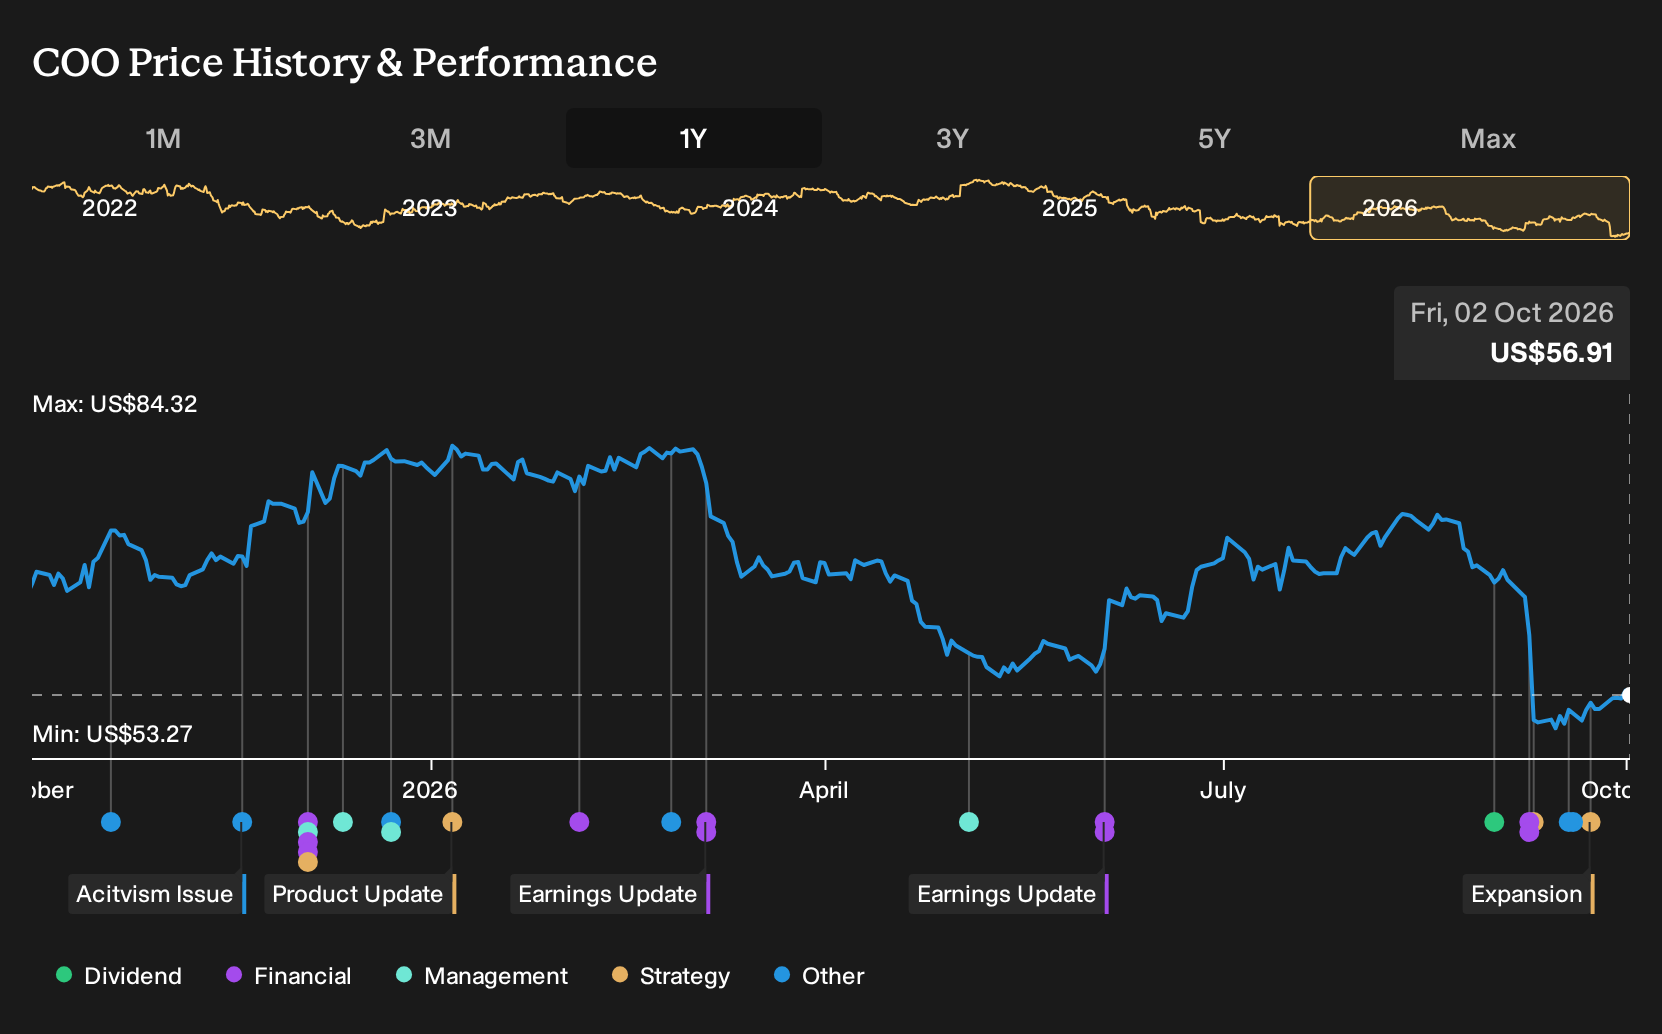
Uncover why Cooper Companies' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view says the real risk for Cooper Companies is that MyDAY and MiSight need heavier R&D and education spend, which could keep margins tighter for longer. Some more cautious analysts were pencilling in US$4.7b of revenue and US$705.4m of earnings by 2029. Their forecasts and The Vision Centre news may eventually collide and shift expectations. Use this spread in opinions as a prompt to explore both narratives before deciding how you feel about the stock.
Explore 5 other Cooper Companies fair value estimates, including one that suggests as much as 24% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cooper Companies research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cooper Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cooper Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cooper Companies?
If the Cooper Companies story has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you surface other businesses that fit your style in a few clicks.
- If capital preservation matters most to you, consider starting with a set of 31 resilient stocks with low risk scores that could offer a steadier ride through different market conditions.
- For investors hunting for quality at a reasonable price, filter for 31 high quality undervalued stocks that combine solid fundamentals with what our models view as discounted valuations.
- Those who like backing stronger balance sheets can build a shortlist from a list of solid balance sheet and fundamentals (26 results) and use it as a base for deeper research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com