


Can Nayax (TASE:NYAX) Justify Its Valuation As The Getnet Deal Expands Its Reach?
Nayax (TASE:NYAX) just expanded its reach. A new alliance with Getnet focuses on integrated cashless payments for unattended machines across Iberia and key Latin American markets.
The new Getnet agreement lands at a moment when Nayax’s 7 day share price return of 10.37% contrasts with a 30.41% decline over 90 days and softer year to date performance. The 3 year total shareholder return of 83.32% reflects a much stronger longer term journey.
Scan other payment and self-service operators showing similar momentum shifts by running your eye over the 615 high quality undiscovered gems alongside Nayax after this Getnet partnership move.
Nayax’s jump after the Getnet deal could be the market finally catching up with a business that has been executing, or it could be just a brief sentiment reset after a tough spell. How does the current valuation line up with that tug of war?
Most Popular Narrative: 5% Overvalued
Nayax last closed at ₪150.10, while the most followed narrative pegs fair value at ₪142.35. This frames the recent Getnet move against a slightly richer valuation and puts the focus on how recurring revenue and new verticals justify that gap.
Growth in ecosystem lock-in, driven by the embedding of Nayax's payment platforms inside OEM devices and diversification of value-added services (including SaaS, embedded banking, and business management), is likely to lift ARPU, reduce customer churn, and drive scalable operating leverage, supporting sustainable margin expansion and earnings growth.
See why 2 investors see Nayax as 5% overvalued.
Result: Fair Value of ₪142.35 (OVERVALUED)
Still, if recurring payments pricing comes under pressure or new acquisitions struggle to generate cash quickly, Nayax’s current premium narrative could be tested quickly.
Find out about the key risks to this Nayax narrative.
Another View: Nayax Through The Sales Multiple Lens
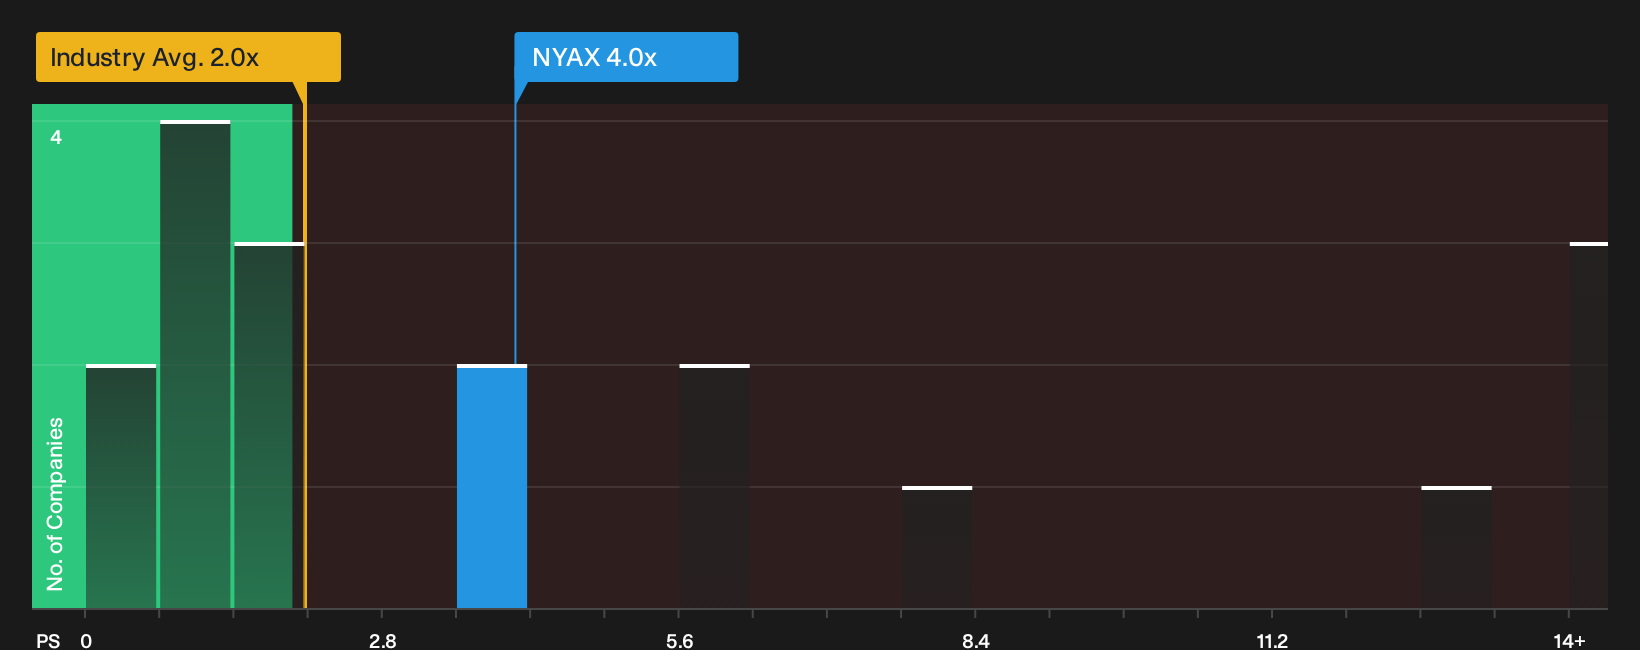
The first narrative says Nayax is about 5% rich to its fair value. On a sales basis, the picture shifts. The stock trades on a P/S of roughly 4x, which compares with a fair ratio of 5.9x and a peer average of 11.8x, yet sits above the wider Asian Electronic group at 2x.
That mix of being cheaper than the model and close peers, but higher than the broader sector, points to real valuation risk if expectations fade and to potential upside if Nayax keeps justifying a premium. Which side of that trade-off fits your own thesis?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Nayax’s valuation story are clear, and the push and pull between risks and rewards is not going away soon. If you want to move quickly and decide where you stand, start by weighing the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Nayax?
If Nayax has sharpened your thinking, do not stop here. Fresh ideas and clear numbers give you options when this story changes gear.
- Spot potential value plays early by scanning the 195 high quality undervalued stocks before the crowd pays attention.
- Anchor your portfolio with payout-focused opportunities by checking the income potential across the 169 dividend fortresses.
- Dial down volatility risk by focusing on companies screened in the 227 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com