


Manulife Financial (TSX:MFC) Could Be 6% Undervalued As ChatGPT Plugin Draws Attention
Manulife Financial (TSX:MFC) is drawing attention after launching a CoverMe travel insurance plugin inside ChatGPT, giving Canadian travellers an AI-assisted way to explore coverage options and receive personalized quotes in English or French.
The plugin launch lands at a time when Manulife Financial’s share price has climbed to CA$61.31, with a 23.11% year to date share price return and a 42.65% total shareholder return over 1 year, suggesting momentum has been building rather than fading over the longer run.
Scan how Manulife Financial’s AI push compares with other insurers and financials tapping artificial intelligence by reviewing our hand-picked 37 profitable AI stocks that aren't just burning cash.
Manulife Financial has surged ahead on AI headlines, yet its share price still sits below the average analyst target and far under some intrinsic value estimates. Is that gap a warning sign or an opportunity?
Most Popular Narrative: 6% Undervalued
Manulife Financial’s most followed narrative pegs fair value at CA$65.20 against the current CA$61.31 share price, framing the AI push and international footprint inside a broader growth story that still prices in some caution on margins and capital use.
The acquisition of Comvest Credit Partners meaningfully scales Manulife's private markets platform and introduces high-growth, fee-based private credit capabilities, leveraging Manulife's global distribution, especially into Asia's fast-growing wealth pools. This should drive a higher mix of stable, capital-light fee income, thereby improving net margins and supporting core EPS and ROE growth.
See why 135 investors see Manulife Financial as 6% undervalued.
Analysts building this fair value view apply a 6.44% discount rate and assume Manulife Financial can keep growing earnings, but at profit margins that ease from 18.8% now toward 13.9%. That mix of higher revenue with slimmer profitability underpins the CA$65.20 figure and helps explain why the current 6% gap is not larger.
The same narrative expects earnings to reach roughly CA$8.5b with a P/E of 14.6x by 2029, compared with a current industry figure of 16.2x for Canadian insurers. That implies Manulife Financial would need to earn its way into that valuation through execution on Asia, wealth and asset management, and digital tools like the new CoverMe travel plugin, rather than leaning on a richer multiple.
Result: Fair Value of CA$65.20 (UNDERVALUED)
Still, the Manulife Financial narrative could be knocked off course by weaker Asian momentum or higher-than-expected credit losses in U.S. loan and real estate exposures.
Find out about the key risks to this Manulife Financial narrative.
Another View: Manulife Financial Through The P/E Lens
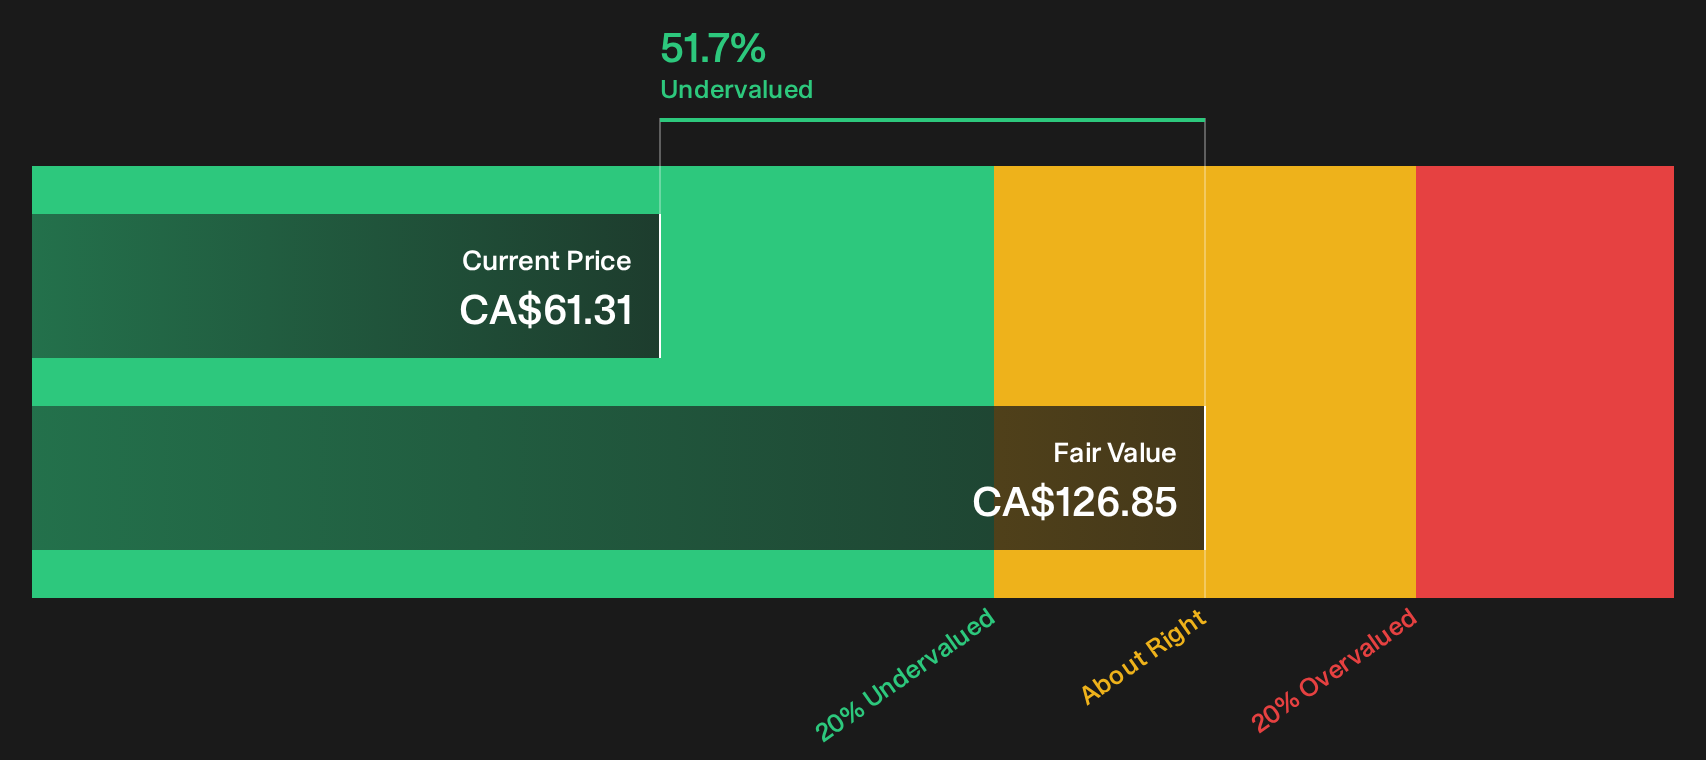
The SWS DCF model flags Manulife Financial as undervalued, with a fair value estimate of CA$126.85 against the current CA$61.31 share price. Yet the market is already paying a 16.3x P/E, above the North American insurance group at 11.4x and its own fair ratio of 15x.
That mix of a large DCF gap and a richer earnings multiple raises a practical question for investors. Is the opportunity in the cash flow story, or is the risk that the P/E drifts back toward the 15x fair ratio instead?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If sentiment in this Manulife Financial story feels mixed, use that as a prompt to check the numbers yourself and consider acting early while others hesitate. To see what investors already like about the business, review its 4 key rewards
Looking for more Manulife Financial style investment ideas?
Do not stop your research with Manulife Financial. Broaden your watchlist now using data driven ideas that can help you spot opportunities others overlook.
- Target steadier compounding by scanning companies that prioritize resilience and capital discipline through our 8 resilient stocks with low risk scores.
- Hunt for potential mispricings by reviewing the 6 high quality undervalued stocks that pair solid fundamentals with room for a rerating.
- Build a watchlist of future contenders by checking the 9 high quality undiscovered gems that have quality metrics most investors have not focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com