


Nike vs. Starbucks: One Beaten-Down Icon Is Primed for an Explosive Rebound
AI may be dominating the headlines, but some of the biggest consumer names are quietly trying to make comebacks of their own.
Nike (NKE) and Starbucks (SBUX) are two good examples. Both were once seen as almost untouchable in their categories, but slowing growth and execution problems eventually caught up. Their stocks have taken very different paths since, and that creates an interesting setup: the harder a company falls, the more room there is for a rebound if the turnaround works.
For dividend investors, there is another reason to watch: Both companies pay investors while they wait.
So let’s see which turnaround looks more believable, and which stock offers the better opportunity today.
Nike Stock: Why the Sneaker Giant's Market Cap Fell to Just $52.5 Billion
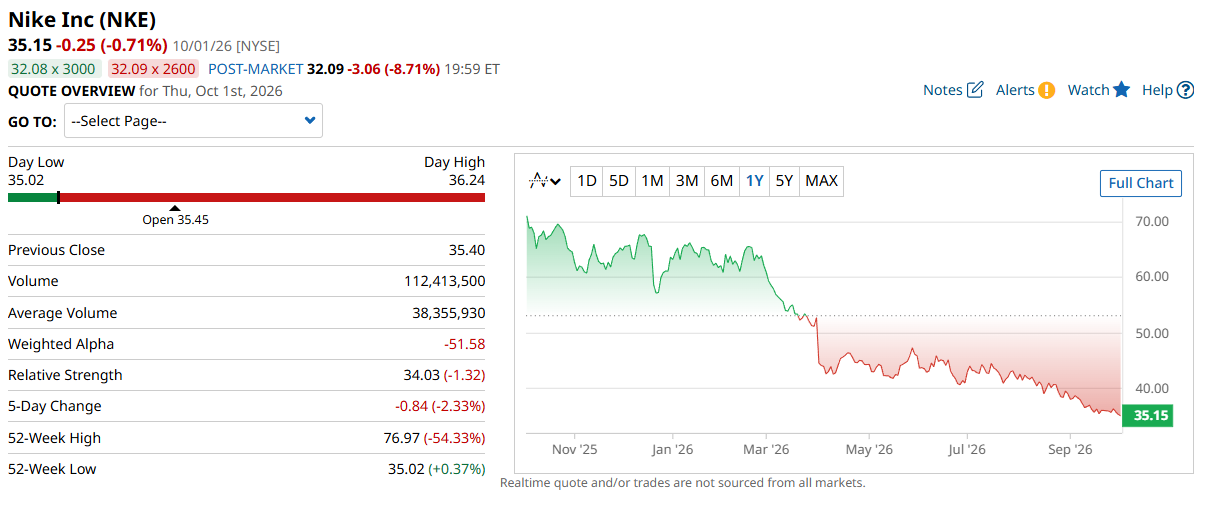
Nike is of course best known for turning sneakers into something bigger than footwear. Air Jordans became part of basketball culture, running shoes became status symbols, and the company built a business around products people wanted before they necessarily needed them, but that very model became harder to maintain.
Today though, the company trades at a market cap of $52.5 billion, far from the dominance investors once associated with the brand.
Starbucks Stock: Why Growth Stalled Despite a $107 Billion Market Cap
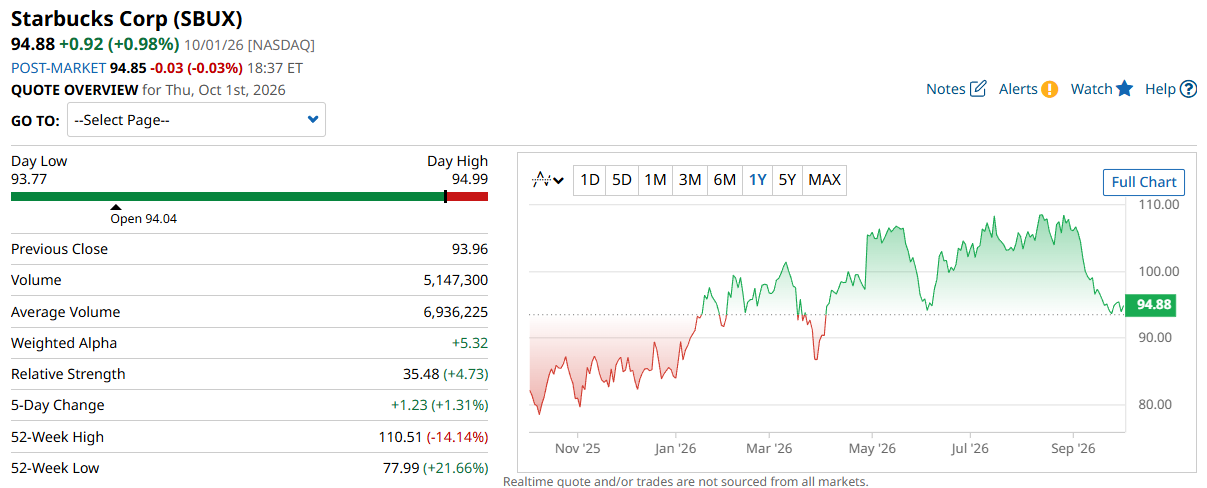
Starbucks did something similar with coffee. It turned an everyday purchase into a routine, whether that meant grabbing a drink before work or meeting someone at a café. But similar to Nike, growth eventually hit a wall, showing signs that something needed to change.
Even after those struggles, Starbucks has a market cap of $107 billion.
Both companies spent years turning ordinary products into habits and culture. Eventually, however, some of the decisions made to sustain that growth began working against them.
How Nike and Starbucks Lost Momentum, and Plan to Get It Back
Nike’s problems were fairly simple: it pulled back from stores where customers expected to find its products, pushed harder to sell through its own channels, and didn't refresh its lineup fast enough. That gave rivals more room to win shoppers Nike once had.
Now, Nike is trying to put sports back at the center of the business. Its Sport Offense strategy reorganizes teams around categories like running and basketball, while the broader Win Now plan includes rebuilding retail partnerships and bringing more new performance products to market.
Meanwhile, Starbucks reached its own breaking point for different reasons. Mobile orders, drive-thru traffic, and an increasingly complex menu made stores busier, but they also made it harder to deliver a consistent experience.
Its Back to Starbucks plan is designed to simplify that experience again. The company is adding more staff during busy periods, improving how café, mobile, drive-thru, and delivery orders are handled, and refreshing stores to bring back more seating and the coffeehouse atmosphere that originally set Starbucks apart.
Both companies are effectively going back to what made them successful in the first place.
Nike wants to win through sport and product again, while Starbucks wants customers to enjoy spending time in its stores again. The question is whether these initiatives are showing up positively in the numbers.
Nike vs. Starbucks: Financials and Valuation
To see which turnaround has stronger numbers, I compared Nike and Starbucks using Barchart’s Stock Comparison Tool.
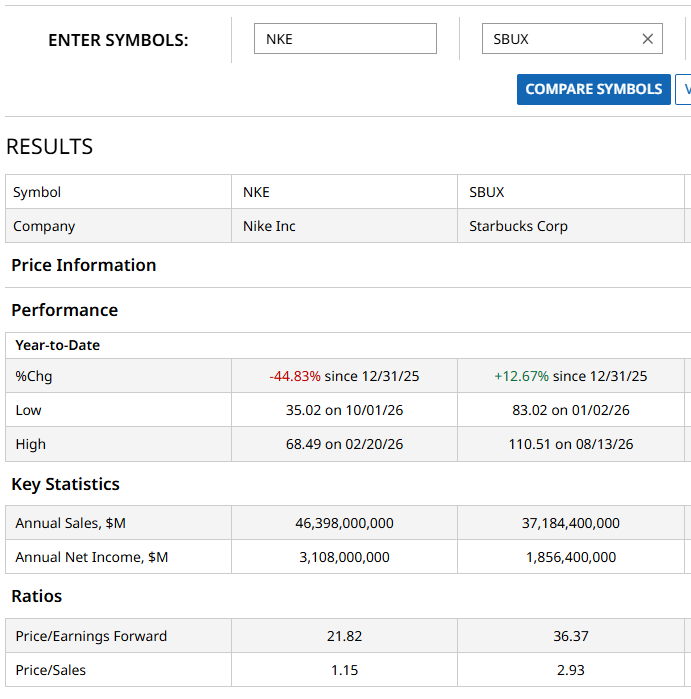
Based on their latest full-year results, Nike's sales were nearly flat, rising just 0.2% to $46.4 billion, while net income slipped 3.4% to $3.1 billion.
Starbucks posted slightly better top-line growth, with sales up 2.8% to $37.2 billion. However, net income fell a whopping 50.6% to $1.9 billion, showing just how much pressure the business is still under.
So far, investors have been much more willing to bet on Starbucks' recovery. SBUX is up about 12% YTD, while Nike has fallen more than 44%.
Valuation also favors Nike. NKE trades at about 22x forward earnings, slightly below the sector average of 24.13x. Starbucks trades at roughly 36.4x, indicating investors are paying a much higher premium. Nike also looks cheaper on sales, trading at 1.15x revenue compared with Starbucks at 2.93x.
Nike has the edge on earnings and valuation, but Starbucks has the momentum. Dividends could help break the tie. Let’s see which one offers the better payout.
NKE vs SBUX Dividend Comparison
Nike pays $1.64 per share annually, translating to a yield of around 4.58%. That is a generous payout, but its dividend payout ratio is 102.64%, meaning the company is currently paying out more than it earns.
Starbucks is not far behind. It pays a forward annual dividend of $2.48, which translates to a yield of approximately 2.6%, while its payout ratio stands at 101.24%.
On yield alone, Nike wins. But with both payout ratios above 100%, neither dividend looks as comfortable as the headline yield might suggest.
With that in mind, let’s see how Wall Street views both turnarounds.
Wall Street Opinion
Here’s how analysts currently view both stocks.
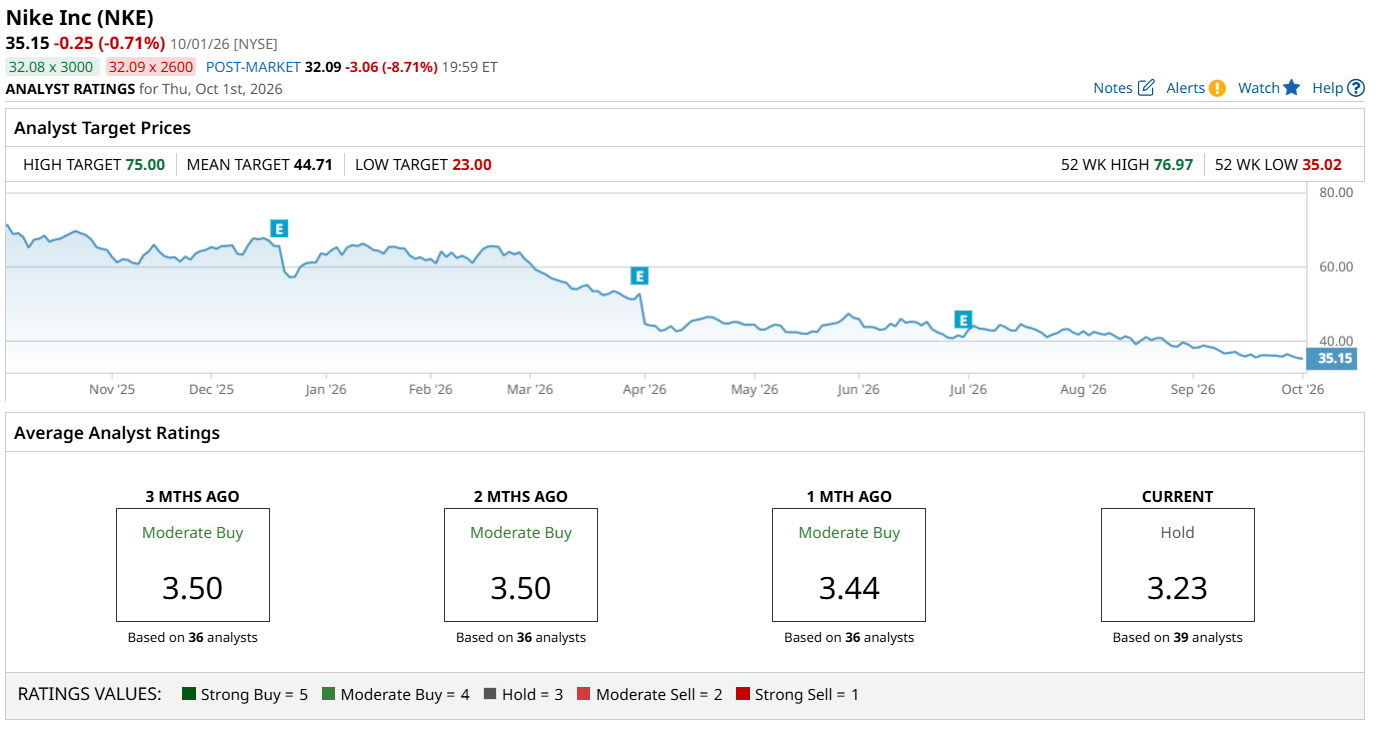
A consensus among 39 analysts rates NKE stock a “Hold”. Its high target suggests upside of up to 113% over the next year.
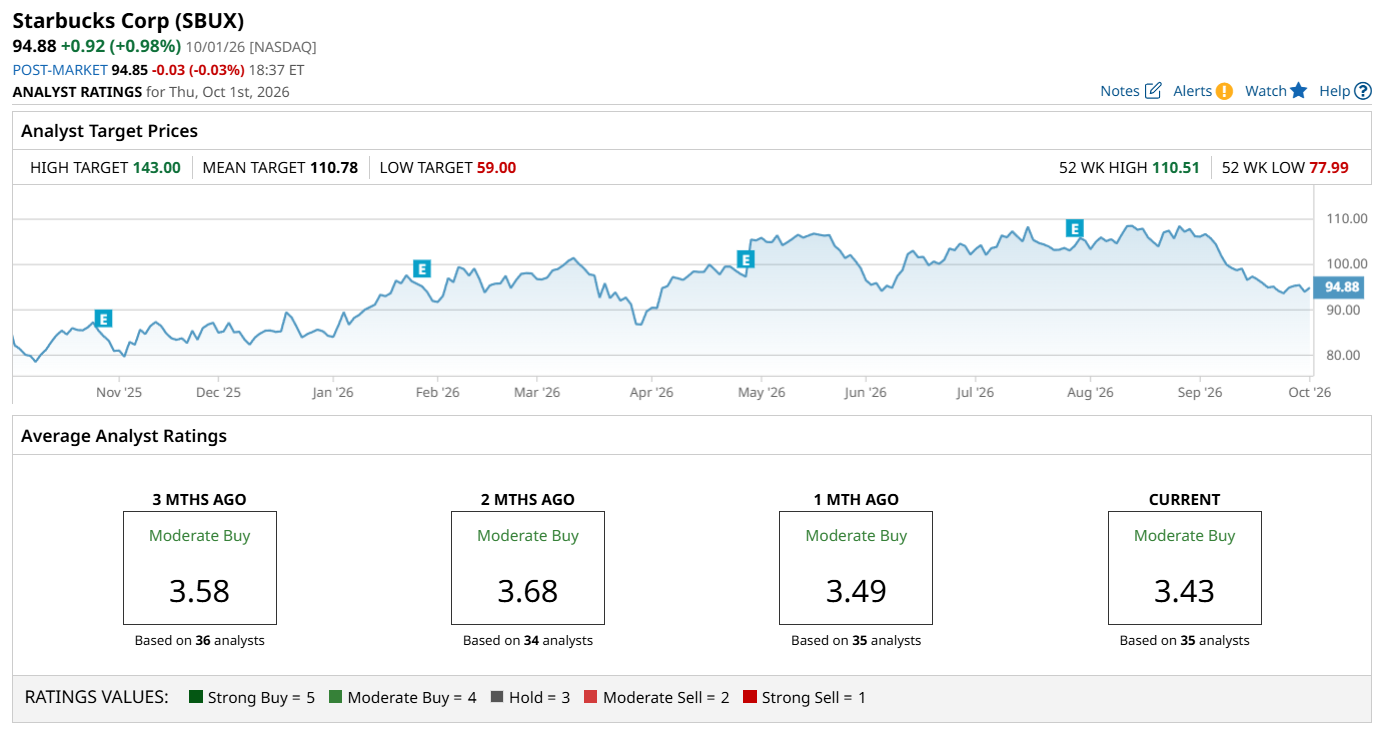
Wall Street is more optimistic on SBUX stock, with 35 analysts rating it a “Moderate Buy,” and its high target price suggests decent upside potential of around 51%.
Verdict: Which is the Better Buy?
Nike has already shown how powerful the sneaker market can be when the product hits. The problem is that demand can also be fickle, and the company still needs to prove it can create that excitement consistently again.
Starbucks has a different advantage. Coffee is closer to a daily habit, giving the company more chances to win customers back as its store experience improves.
On the date of publication, Rick Orford did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.