


Nutrien (TSX:NTR) Faces Fertilizer Cost Pressure Following Industry Commentary Is It Fully Valued
Industry pressures reshape the Nutrien story
Fresh commentary on the fertilizers industry has put Nutrien (TSX:NTR) in focus, as higher input costs and expectations for lower fertilizer use intersect with firmer pricing that could influence the company’s margins and investor sentiment.
Recent trading reflects that tension between headwinds and pricing support, with Nutrien’s share price at CA$99.97 after an 8.76% 90 day share price return and a 15.19% year to date share price return. The 1 year total shareholder return of 24.76% points to momentum that has built over a longer stretch rather than just a short term bounce.
Scan fertilizer peers facing similar cost pressures and pricing support by focusing on 5 high quality undervalued stocks that might be positioned for the next phase of momentum.
Nutrien looks like a solid agriculture supplier with CA$27.3b in revenue and CA$2.4b in profit, and the share price has already moved. Is that strength already baked into CA$99.97, or not yet?
Most popular Nutrien narrative: 7% undervalued
The most followed narrative pegs Nutrien’s fair value at CA$107.49, a touch above the current CA$99.97 price, which frames today’s fertilizer worries against a longer view of earnings power and capital discipline.
Global food demand is structurally supporting long-term fertilizer use: Increasing world population and rising global food demand, particularly in emerging markets, are creating sustained demand for essential crop nutrients like potash and nitrogen, which are Nutrien's core products. This is expected to underpin stable or growing sales volumes and improve revenue visibility.
See why 69 investors see Nutrien as 7% undervalued.
Result: Fair Value of CA$107.49 (UNDERVALUED)
Still, tighter environmental rules on fertilizer production and any shift toward lower synthetic fertilizer use could pressure Nutrien’s volumes and challenge the 7% undervaluation thesis.
Find out about the key risks to this Nutrien narrative.
Another view on Nutrien’s valuation
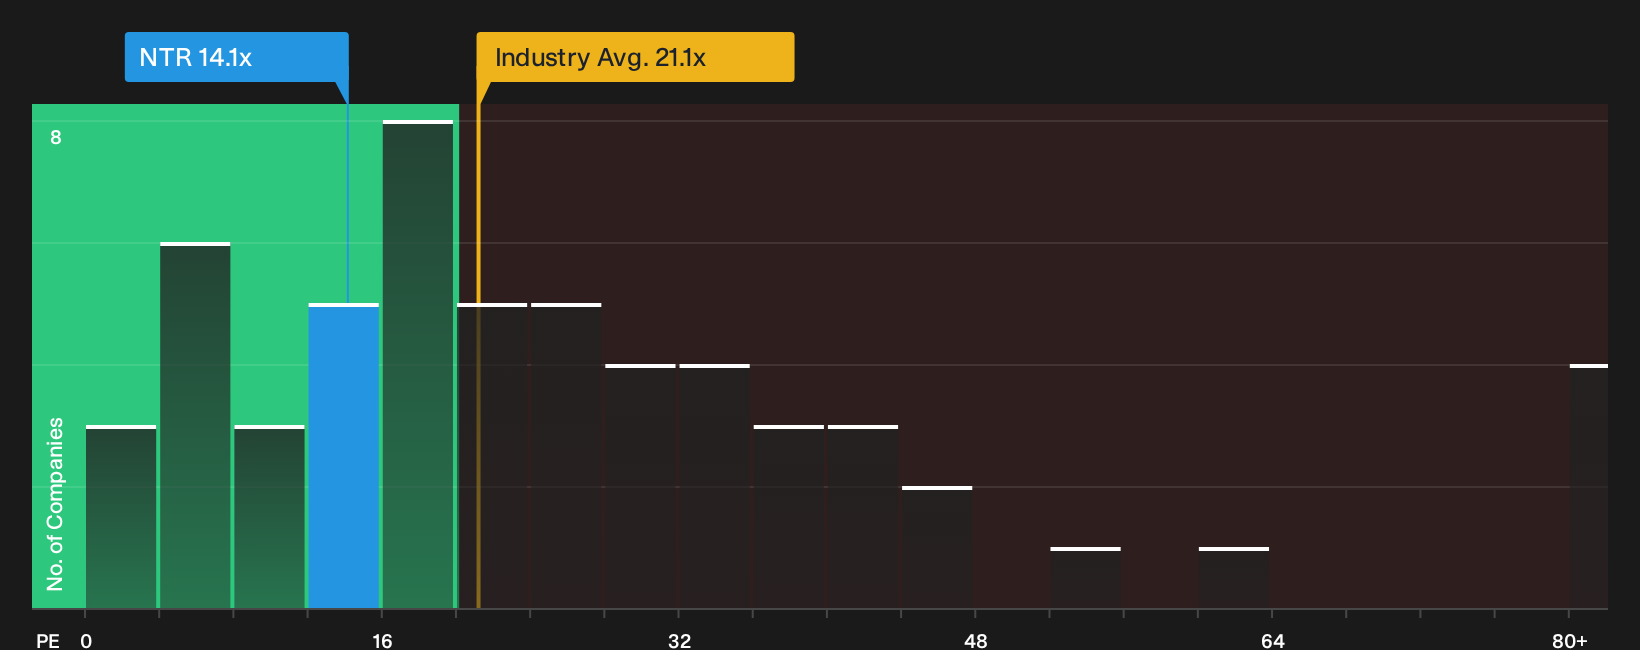
On simple earnings multiples, Nutrien sends a mixed signal. The stock trades on a P/E of 14.1x, which is higher than its direct peer average of 12.4x but slightly above a fair ratio estimate of 13.8x. That gap points to limited margin of safety if earnings fade.
Against the wider North American Chemicals group though, where the typical P/E sits at 21.1x, Nutrien looks cheaper on this metric. The question for investors is whether slower forecast earnings and revenue justify a discount, or whether the market is being too cautious about the fertilizer cycle.
For a closer look at how this pricing stacks up against fundamentals, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and fundamentals can be useful. Use that friction as a prompt to review the key data points yourself, then consider Nutrien’s risk and reward balance by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Nutrien?
If Nutrien has sharpened your thinking, do not stop there. Broader research across quality watchlists can help you spot opportunities before they become crowded trades.
- Target financially resilient businesses by scanning a list of solid balance sheet and fundamentals (7 results) that filters for companies with sturdier foundations.
- Hunt for mispriced opportunities using the 9 high quality undiscovered gems that flags quality firms the wider market may be overlooking.
- Prioritise stability and capital preservation by reviewing a 8 resilient stocks with low risk scores that highlights companies with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com