


Westpac Banking (ASX:WBC) Shares Sit 3% Above Fair Value As Business Lending Gains Focus
Westpac Banking (ASX:WBC) is reworking its playbook as home loan momentum cools, increasing its focus on business lending, where higher net interest margins and faster growth are reshaping how the bank allocates capital.
Recent trading in Westpac Banking reflects that shift in focus. The 1 day share price return of 1.24% comes after the share price declined 11.89% year to date. In contrast, the 3 year total shareholder return of 86.68% and 5 year total shareholder return of 72.36% point to a much stronger longer term payoff profile than the last few months imply.
Scan how Westpac Banking’s business lending pivot compares with other banks by reviewing a curated group of list of solid balance sheet and fundamentals (12 results).
Westpac Banking now trades slightly above both its analyst target and estimated fair value, which raises a sharper question: Is the recent rebound ahead of fundamentals, or is the market still underpricing the business lending pivot?
Most Popular Narrative: 3% Overvalued
On the latest figures, Westpac Banking closed at A$34.32 against a widely followed fair value estimate of A$33.47. This leaves the stock trading modestly above that narrative benchmark while investors reassess the shift toward business lending.
The UNITE program, intended to simplify systems and improve processes, requires significant investment without immediate returns. This may affect earnings in the short to medium term. The transition from call to term deposits in response to rising interest rates has changed the deposit mix, which might be less favorable for net interest margins and could influence revenue outcomes negatively.
See why 91 investors see Westpac Banking as 3% overvalued.
Result: Fair Value of A$33.47 (OVERVALUED)
Still, if Westpac Banking executes on UNITE and keeps credit quality tight, stronger efficiency or lower impairment charges could quickly challenge that mildly overvalued narrative.
Find out about the key risks to this Westpac Banking narrative.
Another View On Westpac Banking’s Valuation
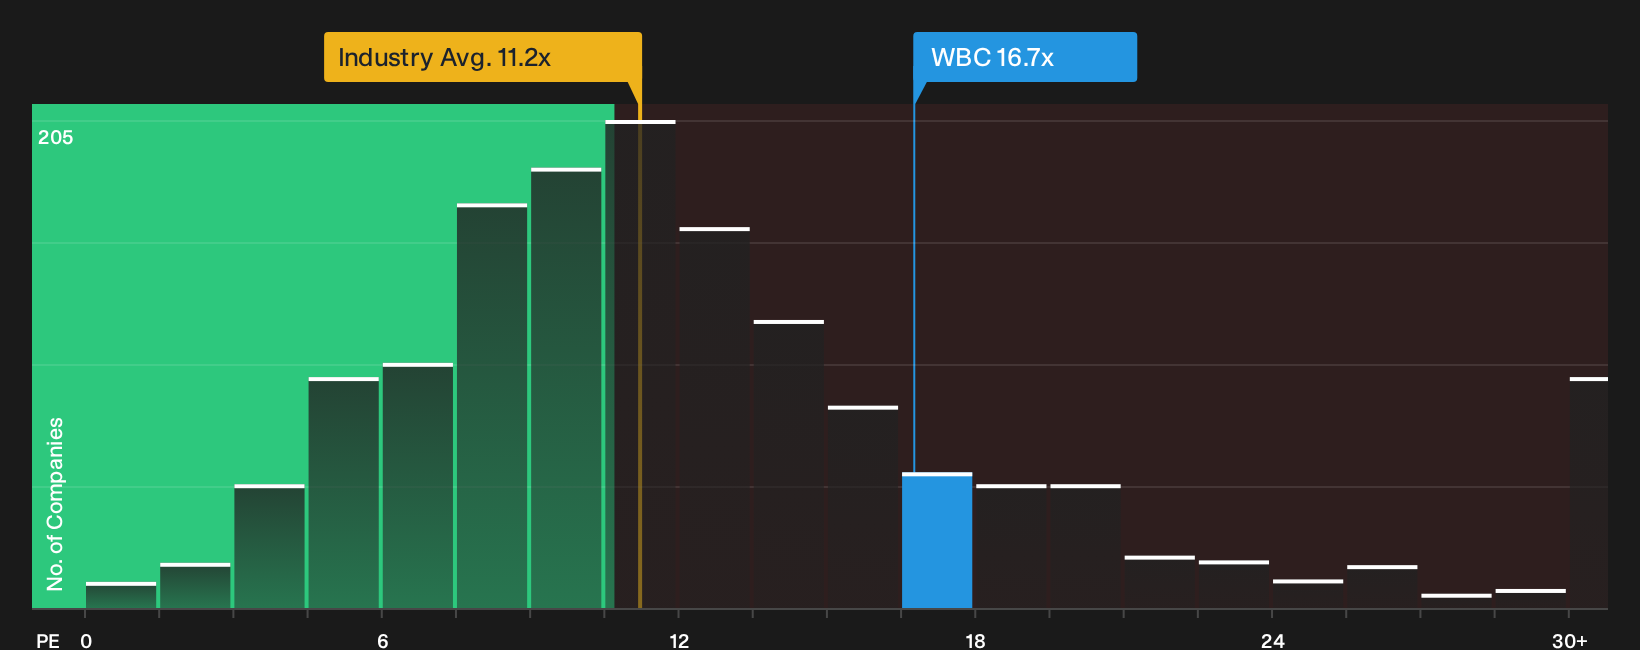
The fair value narrative pegs Westpac Banking as slightly overvalued at A$34.32 versus A$33.47. The market ratio picture complicates that. The stock trades on a P/E of 16.7x, just below its fair ratio of 17.1x and under a 17.7x peer average, yet well above the 11.2x global banks figure. This can be viewed as either a modest premium for quality or a thin cushion if sentiment turns.
Investors who lean on earnings multiples rather than fair value models can pressure test that gap and decide whether this pricing feels tight or comfortable by running through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around Westpac Banking’s valuation and earnings story only matter if you act on them. Move quickly, test the numbers yourself, and weigh the 1 key reward and 3 important warning signs.
Looking For More Investment Ideas Beyond Westpac Banking?
Westpac Banking gives one angle on banks, but real investing edge comes from comparing many different opportunities. Do not leave that perspective on the table.
- Target resilient balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (12 results) that can help you sidestep weaker financial structures.
- Zero in on potential value gaps by reviewing a focused 5 high quality undervalued stocks that could surface businesses trading below what their fundamentals may justify.
- Lock in income ideas by checking a hand picked 3 dividend fortresses that groups higher yielding stocks with more robust payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com