


Big Technologies And 2 Other British Penny Stocks To Watch
Eurozone inflation recently moved to a 3 year high, and that kind of price pressure often keeps smaller, fragile companies under strain. Stronger British penny stocks with cleaner balance sheets and low dilution can look more interesting when many peers are still wrestling with higher costs and tight money. This piece walks through three such UK-listed penny shares that combine financial resilience with growth forecasts from analysts.
The three stocks covered below are just a sample. The full screen surfaced 8 more elite penny shares with similar balance sheet strength and growth profiles that are not included here. To go straight to the source and identify your own high conviction ideas, head into the Elite Penny Stocks screener.
Big Technologies (AIM:BIG)
Overview: Big Technologies provides Buddi branded remote monitoring platforms and GPS wearables to criminal justice agencies across Europe, Asia-Pacific and the Americas.
Operations: The group generates about £51.9 million from electronic tracking devices, products and services, with roughly £35 million from Asia-Pacific, £11 million from the Americas and £6 million from Europe.
Market Cap: £275.4 million
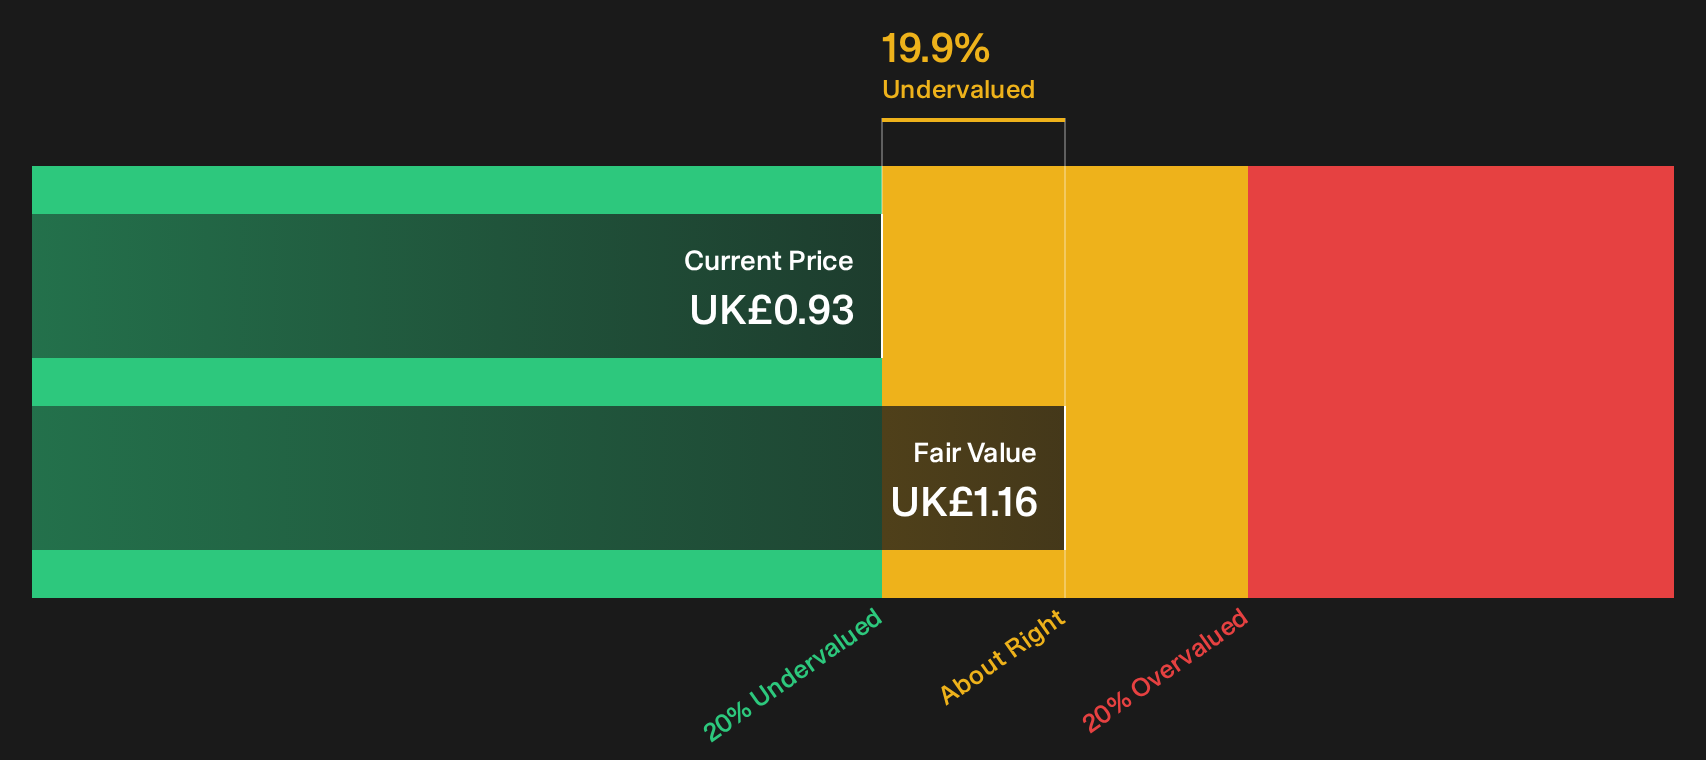
Big Technologies ties neatly into the Elite Penny Stocks theme through its Buddi remote monitoring platform, a justice focused service now backed by a New Zealand contract extension to 2029. The shares trade on a P/E that is below both peers and an estimated fair value multiple, so pricing could hinge on how one unseen pressure shapes future Buddi contract economics.
To see how that contract mix and valuation really stack up, review the DCF valuation analysis for Big Technologies and judge whether Big Technologies' pricing reflects its longer term contract profile.
Franchise Brands (AIM:FRAN)
Overview: Franchise Brands runs a portfolio of service franchises. Filta’s recurring fryer management network provides the group with a scalable, growth focused engine.
Operations: Franchise Brands generates about £64 million from Pirtek, £44.6 million from Water & Waste Services, £36.5 million from Filta International, and £5 million from B2C operations.
Market Cap: £306.5 million
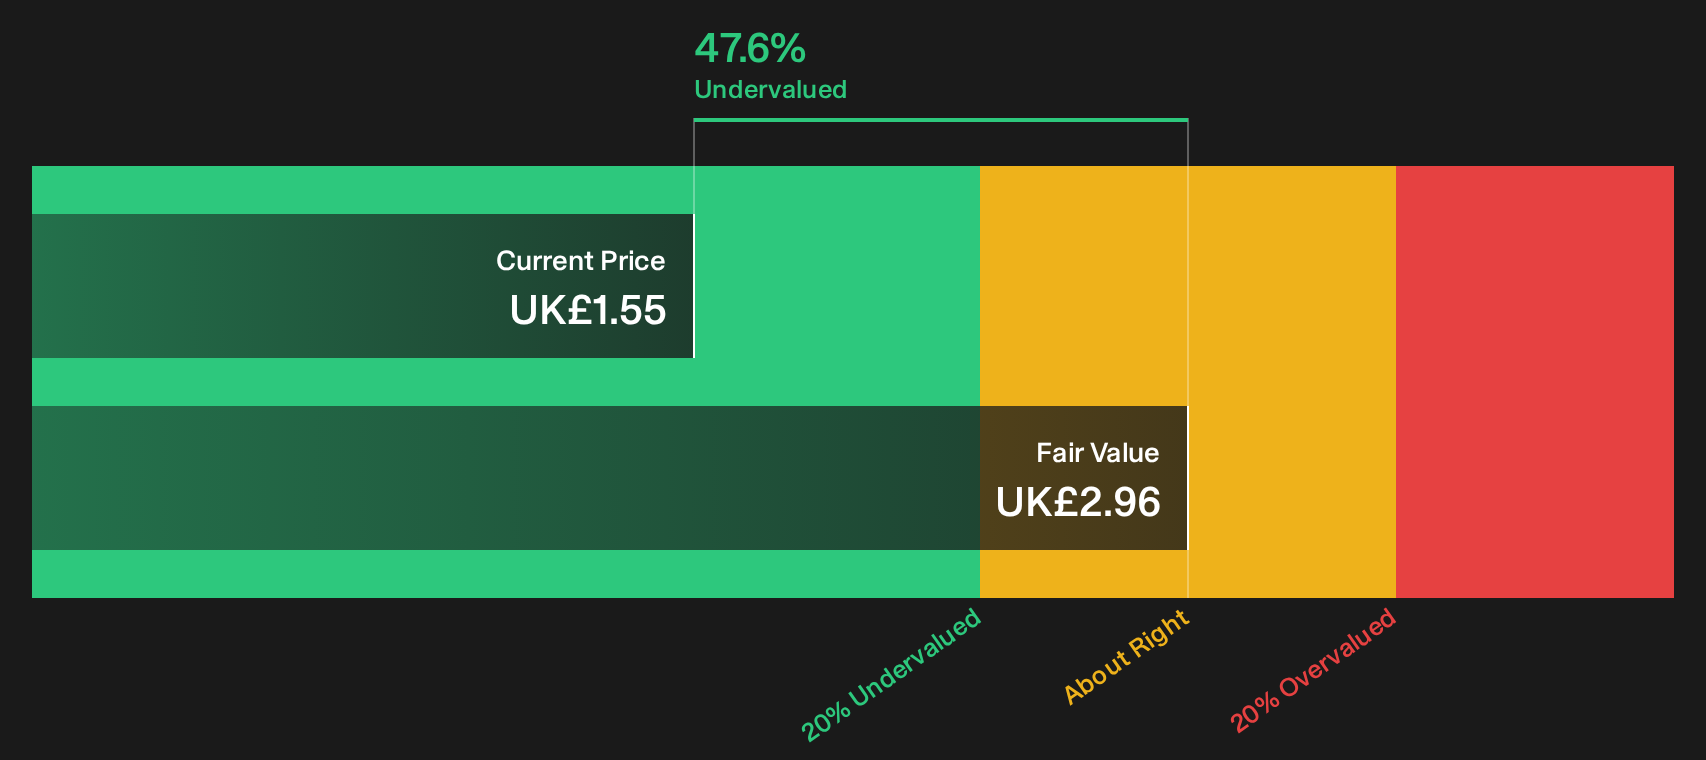
Franchise Brands combines 39.1% earnings growth over the past year with a share price 47.6% below fair value estimates, which is unusual for a profitable, cash returning franchisor. The Filta franchise network links that valuation gap directly to recurring service revenue, so much depends on how one specific constraint shapes future rollouts and margins.
That rollout constraint is exactly what the analysis report for Franchise Brands unpacks, so you can see where Franchise Brands’ earnings engine could accelerate next.
Diaceutics (AIM:DXRX)
Overview: Diaceutics runs the DXRX diagnostic data platform, helping pharma and biotech firms pinpoint eligible patients and support precision medicine launches.
Operations: Diaceutics generates about £41.3 million from Medical Labs & Research, with roughly £38.8 million coming from North America and smaller contributions from Europe and the UK.
Market Cap: £162.6 million
Diaceutics links closely to the Elite Penny Stocks theme through DXRX, a data driven diagnostics platform. The attraction is that investors get high growth forecasts and a value support on P/S, while the outcome depends on how one funding related pressure affects DXRX scaling costs.
If that funding pressure is the swing factor, the analyst forecasts for Diaceutics shows where Diaceutics expectations are concentrating before DXRX scaling costs fully show their hand.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar for now. Do not get caught watching prices move without a plan. Consider your options in advance.
- Identify income workhorses before yields change as more investors pay attention and review the 1 dividend fortresses while the strongest payouts are still being overlooked.
- Follow early AI momentum as capital focuses on companies with real earnings and explore the 37 profitable AI stocks that aren't just burning cash before the most attractive entries become harder to find.
- Evaluate opportunities ahead of potential grid upgrades and examine the 39 power grid technology and infrastructure stocks while these infrastructure names may still reflect limited expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com