


CVS Health (CVS) Stock Could Be A Bargain Despite Its 39% 3 Year Gain
CVS Health has delivered a 3 year gain that contrasts with recent share price weakness, which puts fresh attention on whether today's valuation still lines up with its earnings power. With the stock last closing at US$86.46 after declines over the past week and month, investors are asking how much of the business story is already reflected in that figure.
- Over the past 3 years, CVS Health has returned 38.7%, which puts real weight on the question of whether the current earnings base can carry that performance further.
- Management's push into an integrated, value based primary care model and ongoing scrutiny of its pharmacy benefit manager role can reshape earnings mix, margin profile, and the timing of cash flows that support the valuation.
- The analysts covering CVS Health have run their own numbers. See what analysts think CVS Health's shares could be worth.
The issue now is whether CVS Health's current share price is adequately explained by the earnings it is producing today and what those profits may reasonably support over time.
To see how CVS Health's recent swing in sentiment compares with other companies where valuation depends on earnings strength, it can help to scan 31 high quality undervalued stocks.
Is CVS Health Still Cheap on Earnings?
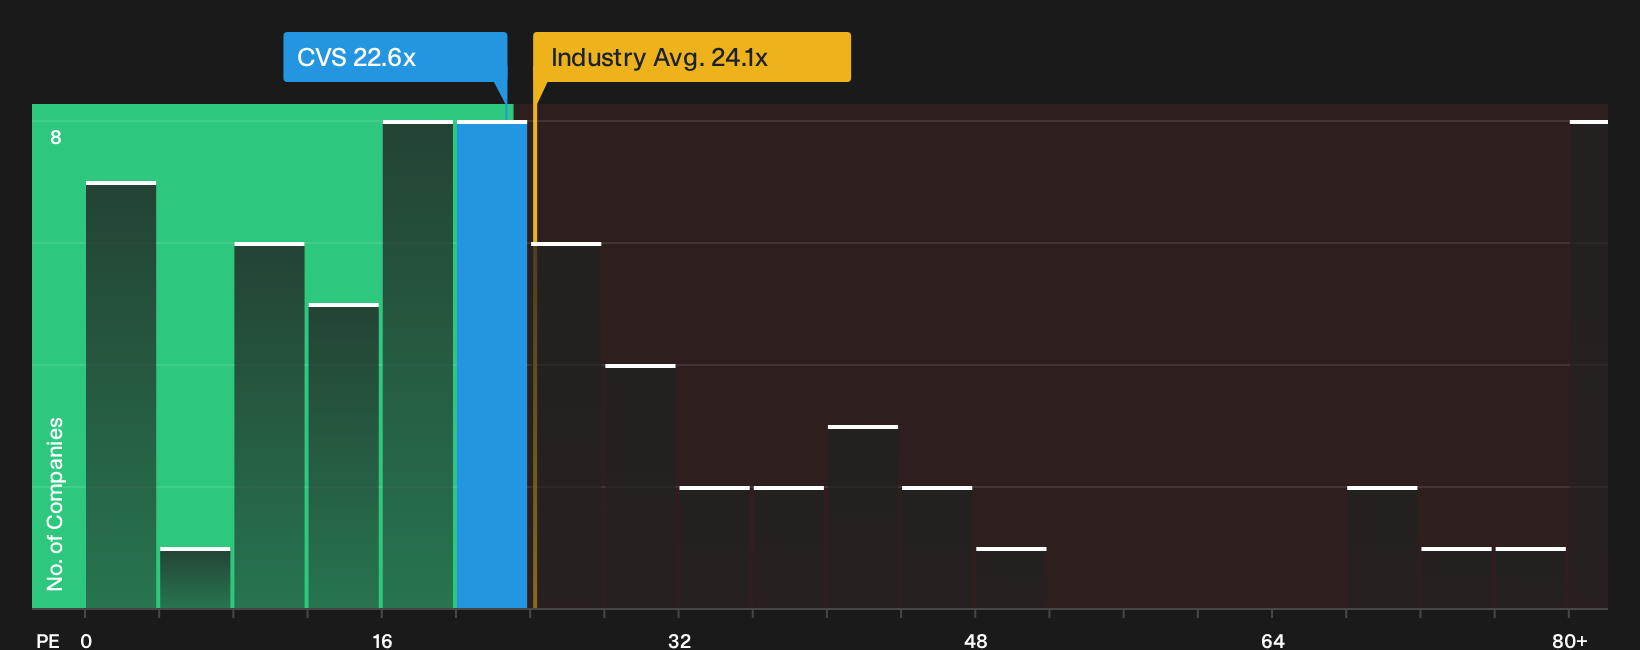
The P/E ratio is a useful lens for CVS Health because earnings still sit at the center of how investors judge its integrated health model. At a current P/E of 22.6x, the stock trades at a premium to its healthcare peer group on 18.6x, yet at a slight discount to the broader healthcare industry average of 24.1x. That split suggests the market is applying some extra weight to CVS Health's profit stream compared with close peers, while still keeping a modest cushion relative to the wider sector.
The fair value framework, which looks at factors like margins, risk profile and scale, points to a higher P/E than where CVS Health is priced today, so the current multiple screens as undervalued on that yardstick. Because management is pushing further into value based primary care while facing scrutiny of its pharmacy benefit manager operations, the gap between price and this more tailored benchmark will likely feel comfortable only to investors who are confident the earnings base can absorb those pressures. Explore the numbers behind CVS Health's P/E valuation.
The CVS Health Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E discussion leaves off for CVS Health by spelling out which mix of future growth, margins and earnings would need to materialise for the stock to be worth meaningfully more or less than it is today on Simply Wall St's Community page. Each scenario ties a fair value estimate to a particular view of CVS Health's potential catalysts and pressure points, so you can track over time which version of events appears to be taking shape.
One of the top community narratives on CVS Health: 17% undervalued
"CVS is no longer trying to be a faster pharmacy. It’s trying to be a more complete healthcare system, and that distinction matters…"
Discover why this Narrative puts CVS Health at 17% undervalued.
For CVS Health, the valuation story still leaves one crucial issue hanging
Price and earnings only tell part of CVS Health's picture, because the research also flags specific risk checks that could change how you weigh everything you have just seen. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com