


Minerals 260 (ASX:MI6) Swung To A Profit, Is The Stock Fully Priced?
Minerals 260 earnings shift puts profit profile in focus
Minerals 260 (ASX:MI6) has moved from a net loss to a net profit of A$83.48 million for the year to June 30, 2026, sharply altering its earnings profile.
The latest move to a net profit lands on top of a sharp swing in market sentiment, with Minerals 260’s share price delivering a 101.16% year to date share price return and a 253.06% 1 year total shareholder return, even as the 7 day share price return fell 7.98%, hinting at some cooling momentum after a 13.82% 90 day share price return and recent updates on the Bullabulling Gold Project.
Scan how Minerals 260 compares with other resource plays showing sharp sentiment shifts using our hand picked list of 15 high quality undiscovered gems.
The share price has already rerated hard on Minerals 260’s profit swing and Bullabulling updates. The next question is whether most of the upside is already in the rear view mirror once valuation enters the frame.
Price-to-earnings of 25.6x for Minerals 260: Is it justified?
Minerals 260 now trades on a P/E of 25.6x, which sits well above the Australian metals and mining industry average of 12.1x, even after the sharp run in the share price and the recent pullback.
The P/E ratio compares the current share price to earnings per share. For a resources explorer and developer like Minerals 260, it effectively reflects how much investors are willing to pay today for each dollar of current profit while they weigh up the development risk on projects such as Bullabulling and the lack of meaningful reported revenue.
That 25.6x multiple is materially richer than both the sector and the stock’s own estimated fair P/E of 24.7x. This signals that the market is paying a premium for the earnings profile and the expected 35.6% annual profit growth, rather than pricing Minerals 260 purely in line with its peers or the level our model suggests the ratio could move towards.
Against the broader Australian metals and mining group at 12.1x, this valuation looks stretched. Investors are effectively assigning more than double the sector earnings multiple to Minerals 260 while also accepting that the SWS fair ratio points to a slightly lower P/E as a more balanced level.
Explore the SWS fair ratio for Minerals 260.
Result: Price-to-earnings of 25.6x (OVERVALUED).
Still, Minerals 260 relies on exploration progress at Bullabulling and Moora, and any delay or disappointing drill results could quickly challenge the current premium.
Find out about the key risks to this Minerals 260 narrative.
Another view on Minerals 260 using cash flows
Multiples tell one story for Minerals 260, but the SWS DCF model tells a tougher one. On that cash flow view, A$0.87 trades above an estimated future cash flow value of A$0.41, which points to an overvalued stock if those long term assumptions hold. Which lens do you trust more for a zero revenue explorer?
For a closer look at how this cash flow view is built and what assumptions sit under it, check out the Look into how the SWS DCF model arrives at its fair value..
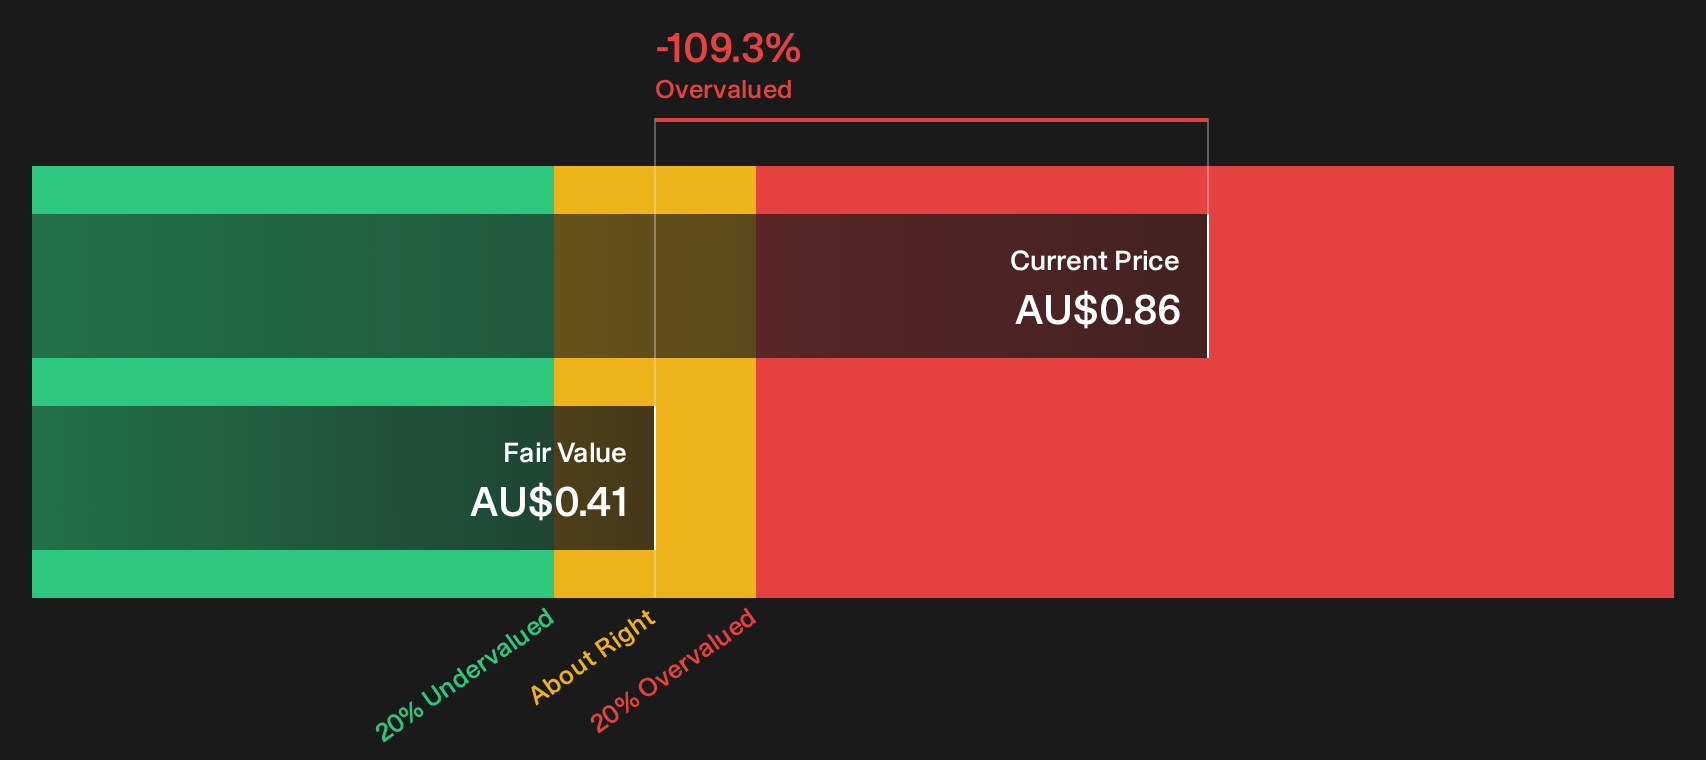
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Minerals 260 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this Minerals 260 story feels finely balanced between excitement and caution, move quickly. Test the numbers, cross check expectations and build your own stance with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Minerals 260?
Do not stop with Minerals 260 if you want a fuller picture. Broaden your watchlist now using focused screens that surface very different types of opportunities.
- Target resilient balance sheets and fewer nasty surprises by scanning companies in the 7 resilient stocks with low risk scores.
- Hunt for strong businesses trading below what the numbers suggest they could be worth through the 5 high quality undervalued stocks.
- Prioritise dependable cash returns by filtering for higher yielding payouts in the 3 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com