


Why Infineon Technologies Stock Is In Focus After Bangkok Plant Opening
- Infineon Technologies has opened a new backend manufacturing site in Bangkok, Samut Prakan, adding modular capacity, advanced automation, cleanroom assembly and test capabilities, and targeting about 1,000 employees as Module A ramps.
- The Bangkok facility runs on 100% green electricity with on-site solar, water recycling and rainwater collection, tying Infineon Technologies’ capacity build-out directly to its resource efficiency and emissions reduction goals.
- Next, the focus shifts to how this Thailand capacity build, with its scalable backend footprint, could influence Infineon Technologies’ investment narrative.
Infineon Technologies Investment Narrative Recap
To own Infineon Technologies, you need to believe its power, sensor and security chips keep winning sockets in AI data centers, EVs and energy infrastructure, and that current capacity and pricing can support that demand. The big near term swing factor is how quickly volumes recover as inventory correction eases. The Bangkok backend site helps operationally but does not change that core volume catalyst on its own.
The largest immediate risk still sits in potential excess capacity and margin pressure if customer destocking or weaker EV demand drags on. Extra backend headroom in Thailand could either absorb a pickup in orders or, if conditions soften, add to underutilization and idle costs. That duality makes execution on loading this new plant, and aligning it with the Step Up cost program, important to monitor.
The Bangkok manufacturing opening is the key new data point here. It ties directly into Infineon Technologies’ push into AI data center power and industrial energy projects, where management already highlights demand for power and sensor solutions. Incremental backend capability in Southeast Asia gives the business more flexibility to support those programs and to qualify for complex automotive and industrial modules.
For catalysts, link this to the upcoming AI focused investor and industry events. Presentations at the virtual AI & Technology conference on 1 October 2026 and at Data Centre World Asia give management a platform to explain how Bangkok feeds into AI and data infrastructure opportunities, and how capital spending, inventory days and idle charges might evolve as the new site ramps.
Infineon Technologies' current analyst story points to revenues of €23.7b and earnings of €4.8b by 2029. That profile assumes 16.1% yearly revenue growth and an increase in earnings of about €3.7b from €1.1b today.
Uncover why Infineon Technologies' fair value indicates a 34% potential upside to its current price that could narrow quickly.
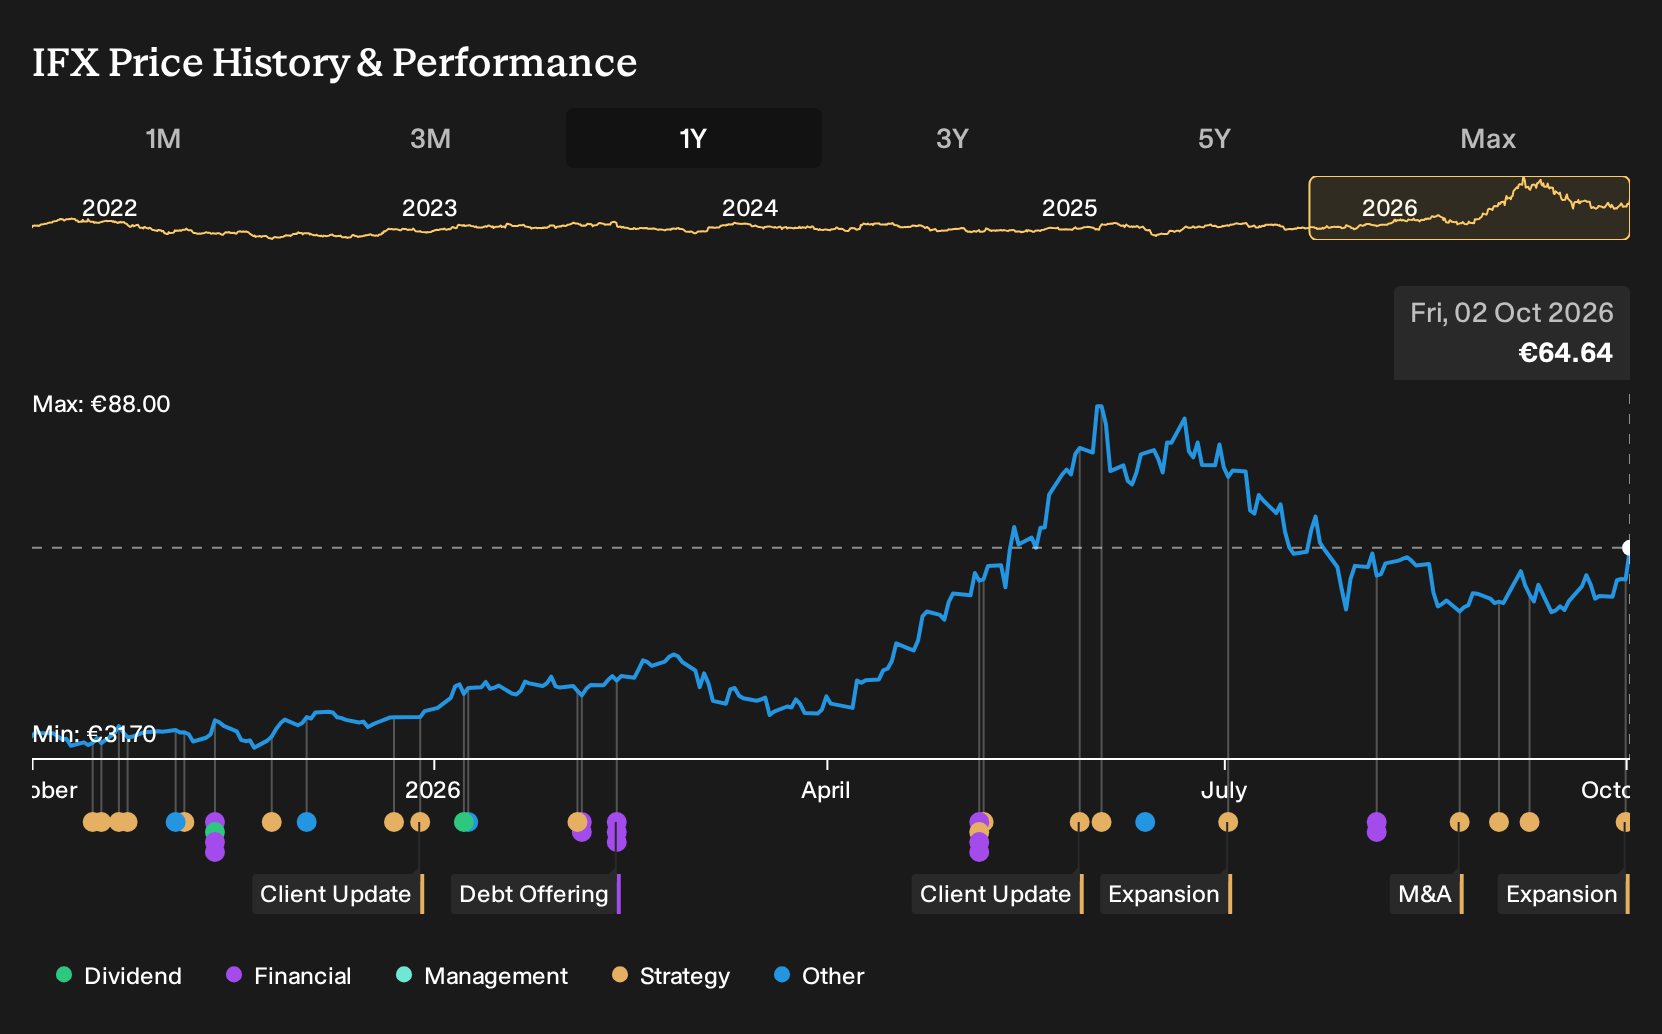
Exploring Other Perspectives
Some of the lowest Infineon Technologies analysts lean into a different catalyst. They worry that redirecting capacity into AI data center power makes results more fragile if that buildout cools. Their models, before this Bangkok news, pointed to about €21.8b in 2029 revenue and €4.0b earnings, which is well below consensus. Use that gap as a prompt to compare several viewpoints and decide which story feels more realistic to you.
Explore 3 other Infineon Technologies fair value estimates, including one that suggests as much as 22% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Infineon Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Infineon Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Infineon Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Infineon Technologies?
Once you have formed an opinion on Infineon Technologies, it can help to compare that thesis with opportunities across other parts of the market using the Simply Wall St Screener. Each list below focuses on a different angle, so you can match ideas to your risk tolerance and return objectives.
- If capital preservation is front of mind, start with companies that score well on resilience and balance sheet strength through our 228 resilient stocks with low risk scores.
- For investors hunting for value backed by fundamentals, consider stocks that combine quality metrics with a price that screens as potentially cheap through the 192 high quality undervalued stocks.
- If you are looking for off-the-radar opportunities, scan for financially solid businesses that receive less attention from the market through the 615 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com