


Lisi (ENXTPA:FII) Could Be 34% Undervalued As Europe Pushes Local Sourcing
Fresh commentary has put Lisi (ENXTPA:FII) back in focus as European aerospace and automotive groups lean harder into local sourcing and aim to curb reliance on Chinese supply chains.
Lisi’s share price has climbed year to date, with a 12.71% share price return and a 27.23% total shareholder return over the past year. However, the 90 day share price return of 14.47% indicates momentum has cooled recently as investors reassess supply chain and earnings risks.
Scan how Lisi fits into the European reshoring story by lining it up against list of solid balance sheet and fundamentals (206 results) that could also benefit from supply chain diversification.
Lisi now appears to be a solid operator aligned with reshoring themes. After a strong three-year stretch on the chart, however, investors may question whether that quality is already fully reflected in the current €60.30 share price.
Price-to-Earnings of 29.5x: Is it justified for Lisi?
Lisi trades on a P/E of 29.5x, and with the last close at €60.30 the stock screens as a mix of quality, optimism, and some valuation tension versus different benchmarks.
The P/E multiple compares what investors pay today for each euro of current earnings, which matters a lot for an industrial supplier like Lisi where profit cycles can be uneven. A higher P/E usually signals that the market expects stronger earnings growth or greater resilience than the average listed peer.
For this stock, the signals pull in two directions. The P/E of 29.5x is slightly below the European Aerospace & Defense peer average of 32.5x and also below the French peer group at 30.8x, which points to some relative value. At the same time, the ratio sits above the estimated fair P/E of 26.2x. This suggests the market is paying a premium to the level that quantitative fair value work indicates it could settle toward.
The comparison is blunt. Against sector P/E levels, Lisi looks cheaper than a typical Aerospace & Defense peer and a touch cheaper than the broader comparison set, yet richer than its own fair P/E benchmark of 26.2x that the market could eventually converge on if expectations cool or earnings catch up.
Explore the SWS fair ratio for Lisi.
Result: Price-to-Earnings of 29.5x (ABOUT RIGHT)
Still, the story can crack if aerospace or automotive demand softens, or if supply chain shifts slow and leave Lisi’s current valuation looking stretched.
Find out about the key risks to this Lisi narrative.
Another View on Lisi’s Value
The P/E work paints Lisi as roughly fairly priced, but the SWS DCF model points in a different direction. With the share price at €60.30 and a future cash flow value estimate of €80.94, that framework presents the stock as undervalued and raises a simple question for you: Which yardstick feels more convincing?
Look into how the SWS DCF model arrives at its fair value.
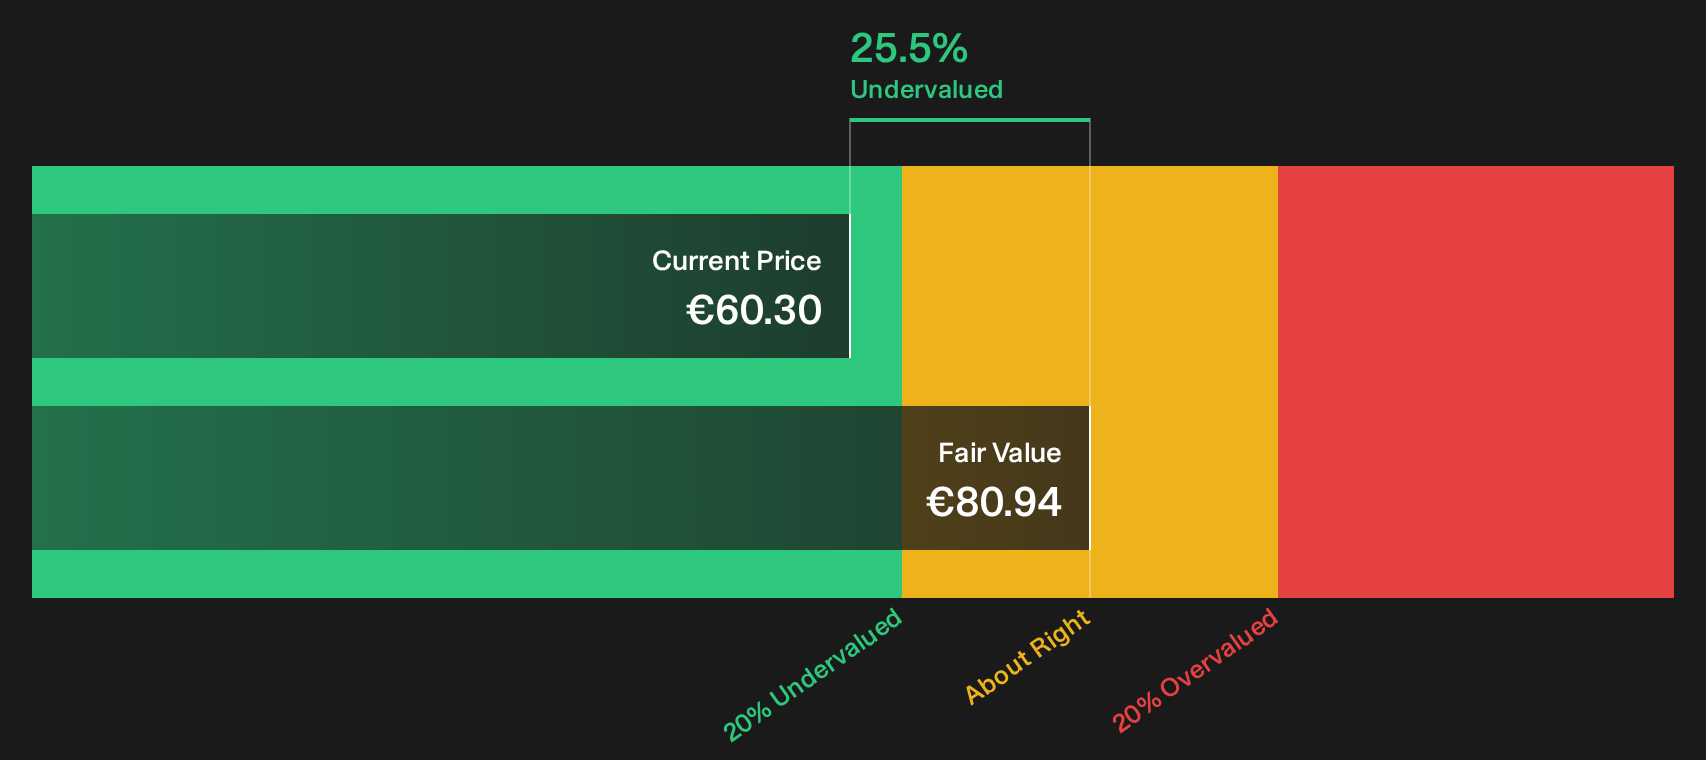
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lisi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of upside signals and flagged concerns around Lisi feels finely balanced, consider acting quickly and carefully test the story against your own framework, starting with the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Lisi?
Do not stop with Lisi if you want a fuller picture of what the market is offering right now across different types of opportunities and risk levels.
- Target potential mispricings by scanning the 192 high quality undervalued stocks that combine solid fundamentals with market expectations that may not fully reflect their underlying strength.
- Prioritise resilience by reviewing 228 resilient stocks with low risk scores that score well on stability so sudden shocks are less likely to catch your portfolio off guard.
- Hunt for future leaders early by checking 615 high quality undiscovered gems before attention and liquidity push valuations to less appealing levels.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com