


3 Shipping Stocks Retail Investors Are Watching For Energy Route Disruption
Geopolitics has moved from the back page to the front line of markets, as carrier groups, sanctions and a fragile Strait of Hormuz reshape the risk map for global energy flows. Shipping routes, insurance contracts and day rates now sit under the same spotlight as oil prices. This piece walks through three stocks from the Global Energy Shipping and Marine Insurance screener that appear positively exposed to this turbulence and explains what their specific risk and reward setups might mean for your portfolio.
The stocks highlighted below are only a first cut, and the full screen surfaced 7 more large cap energy shippers and marine insurers with equally compelling narratives that are not discussed in this article. To see the wider field and identify your own high conviction ideas, head straight into the Global Energy Shipping and Marine Insurance screener.
Odfjell (OB:ODF)
Odfjell plugs directly into the Global Energy Shipping and Marine Insurance theme through its global fleet of chemical and oil product tankers and network of storage terminals, giving investors exposure to how route risk, sanctions and capacity constraints ripple through liquid cargo trade flows.
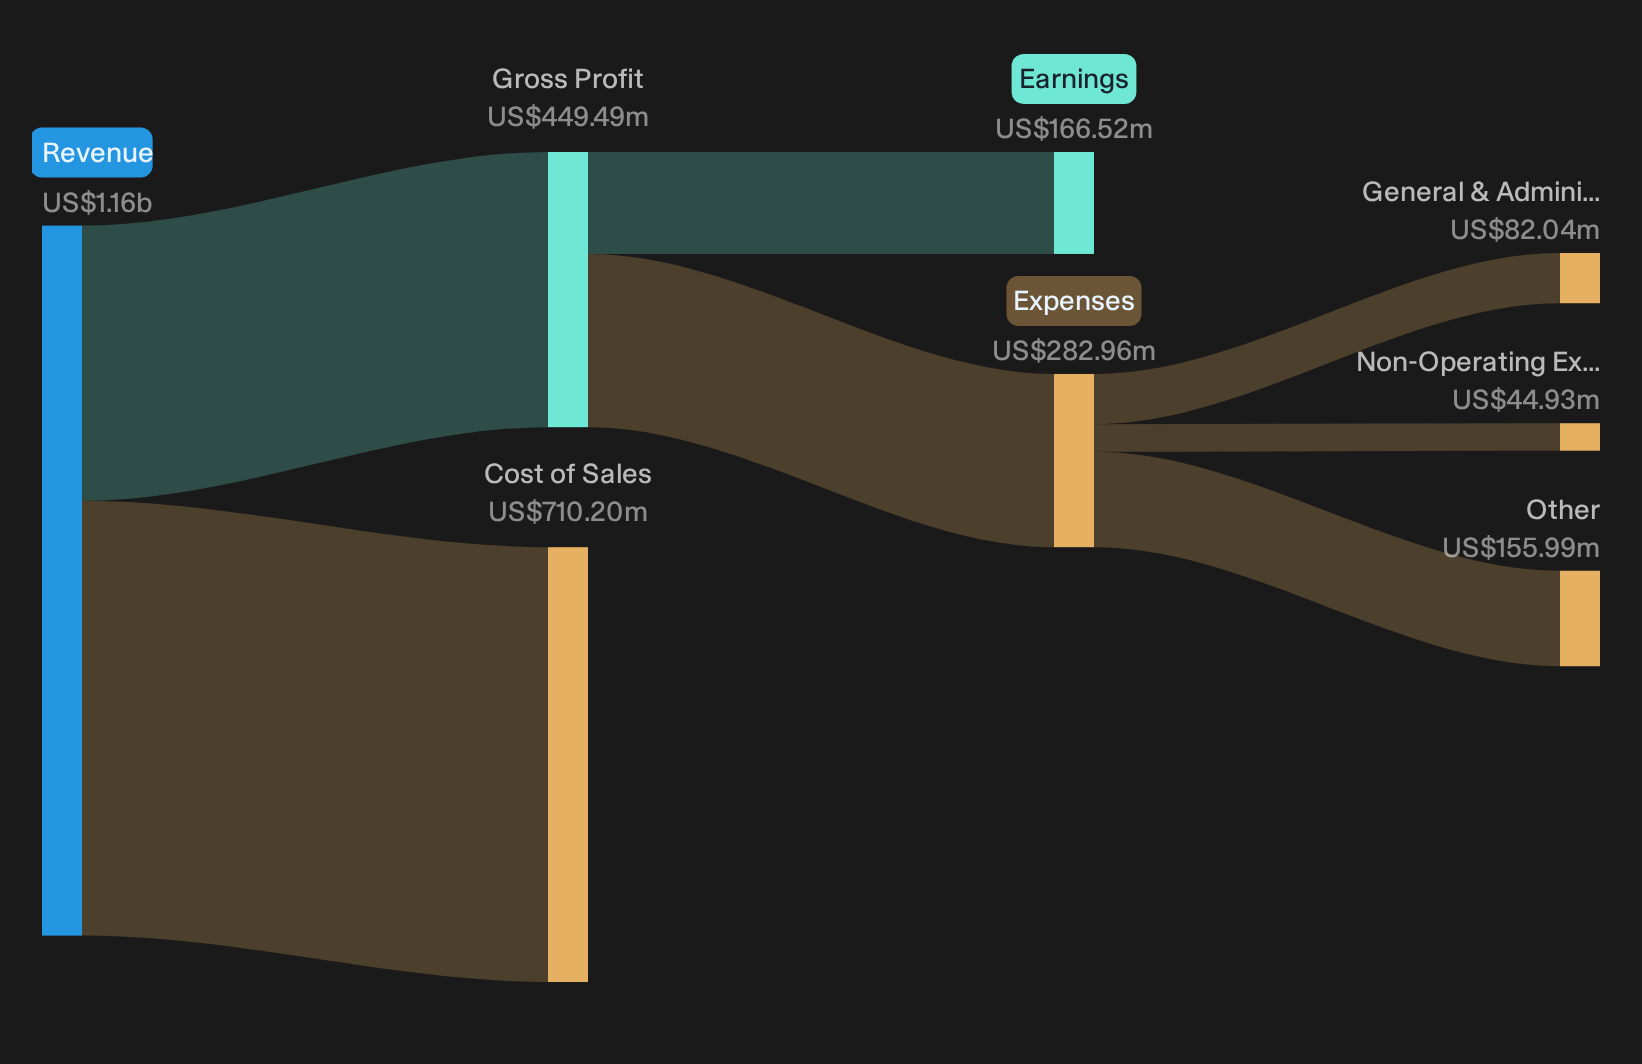
Odfjell SE operates a global fleet of chemical and oil product tankers and tank terminals that move and store bulk liquid chemicals, acids, edible oils and specialty products worldwide, and the company currently carries a market value of roughly NOK10.4 billion.
"Odfjell's long-term investments in sustainable shipping and retrofitting vessels with energy efficiency devices (such as sails) are reducing fleet carbon intensity and fuel costs, which may position the company to capture regulatory-driven premium rates and enhanced operating margins as environmental compliance becomes more valuable in the global shipping market."
What really moves the needle for Odfjell now is how one unseen pressure in global chemical trade flows ultimately feeds through to pricing power.
If that pricing power puzzle matters to you, read the full narrative for Odfjell to see how Odfjell’s carbon efficiency push could be masking bigger earnings and risk swings ahead.
Stolt-Nielsen (OB:SNI)
Stolt-Nielsen gives you another pure play on liquid bulk shipping within this screener, with chemicals, edible oils and fuels moving through its tanker fleets, terminals and container logistics network. All of these segments can feel the ripple effects when sea lanes and marine insurance costs shift.
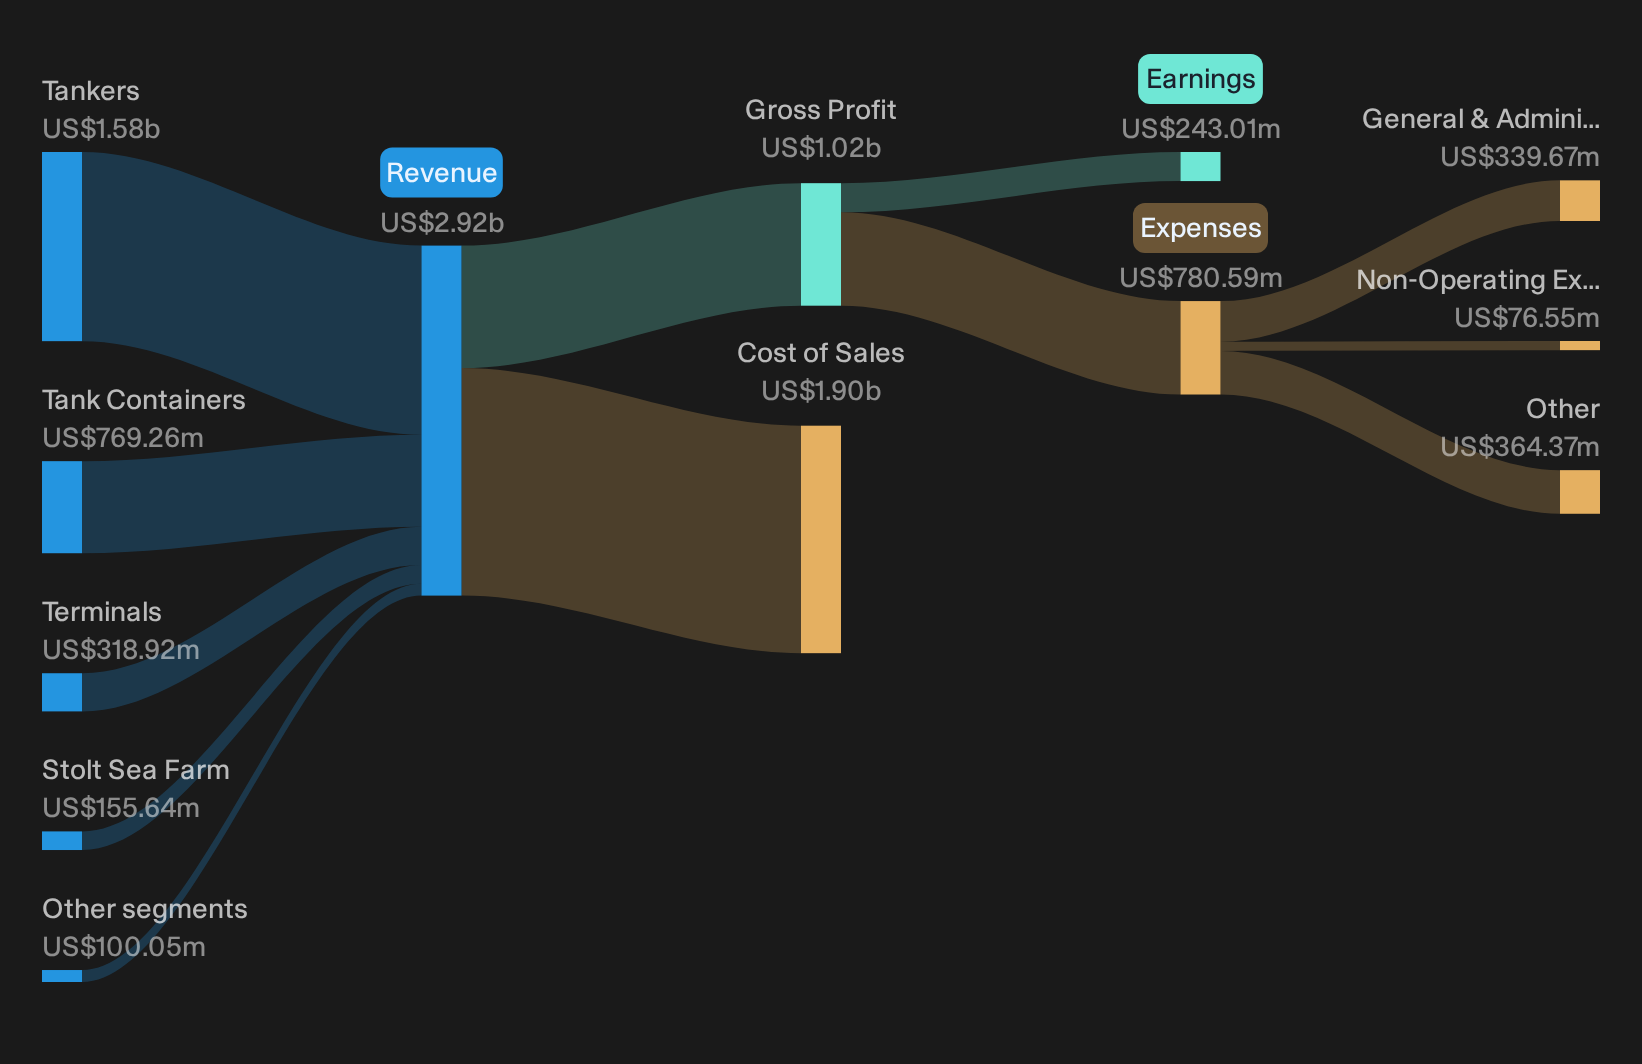
Stolt-Nielsen generates most of its income from Tankers at about $1.6b, supported by Tank Containers at roughly $769 million, Terminals at $319 million, Stolt Sea Farm at $156 million and Stolt Nielsen Gas at $93 million, and the stock carries a market value near NOK19.2b.
"Strategic acquisitions like Hassel 4 and LNG carrier Avenir, which together are expected to contribute approximately $50 million annually to EBITDA, are expected to impact earnings growth positively."
What happens to margins if one crucial assumption on freight demand and storage utilization shifts under that expanding footprint will matter a lot.
When that assumption starts to wobble, the full full narrative for Stolt-Nielsen shows how Stolt-Nielsen’s earnings path could be accelerating, decoupling or quietly stalling beneath the headline EBITDA boost.
Pyxis Tankers (PXS)
Pyxis Tankers gives you pure exposure to the Global Energy Shipping and Marine Insurance theme through its fleet of three product tankers moving gasoline, jet fuel and diesel, backed by three dry-bulk carriers. The group generated about $24 million from its Tanker Fleet and $19 million from Dry-Bulk, with a market value near $73 million.
Pyxis Tankers is a small, Greece-based owner directly linked to chokepoint risk. Its refined product vessels earn their keep on the same routes investors worry about when Hormuz or the Red Sea flare up, which can be a powerful tailwind for earnings, depending on how one unseen pressure in global product flows plays out.
Those route pressures may be masking where Pyxis Tankers’ earnings power really goes next, and the analyst forecasts for Pyxis Tankers hint at how that story could evolve.

Seeking Alternatives Before Momentum Flies Past?
Fresh ideas often move first. Markets can reprice quickly, stories can gain momentum and late entries can get caught chasing. Scan these under the radar for now opportunities and consider them promptly.
- Identify cash generative opportunities early by scanning the list of solid balance sheet and fundamentals (206 results) before the crowd starts bidding up resilient businesses.
- Explore potential income-focused ideas by checking the 169 dividend fortresses while yields and payout strength still look attractive.
- Review underfollowed growth stories before attention builds by using the 615 high quality undiscovered gems while they are still quietly priced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com