


HPE (HPE) Stock Looks Undervalued Despite Its 401% Five Year Run
Hewlett Packard Enterprise has ridden a powerful story around AI infrastructure and networking, yet the real test for the current share price is what the business can sustainably earn in cash flows. With the stock near record territory, the key issue is whether those cash flows are rich enough, and reliable enough, to line up with where the market now prices HPE.
- Over the past 5 years, Hewlett Packard Enterprise has delivered a very large total return of about 4x, which raises the question of how much of that move is backed by the cash the company can actually generate over time.
- Growing orders for high performance networking and the US$1.2b Helios server deal suggest investors now expect stronger and possibly earlier cash generation from HPE's infrastructure offerings, which feeds directly into any cash flow based valuation.
- Prefer to judge Hewlett Packard Enterprise on earnings? See what Hewlett Packard Enterprise's 32.0x P/E says about the price.
The stock's next move may depend on whether a Discounted Cash Flow (DCF) view of Hewlett Packard Enterprise's cash generation supports the price investors are paying today.
If you are weighing Hewlett Packard Enterprise on its cash flows, it can help to compare it with a wider set of AI infrastructure plays using 90 AI infrastructure stocks.
Does Hewlett Packard Enterprise Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Hewlett Packard Enterprise can return to shareholders over time and discounts it back to today. On the latest twelve month numbers, the company produced about $3.8b of free cash flow, and the model then steps this forward using a two stage Free Cash Flow to Equity approach.
Analyst and model projections build in growing free cash flows, with estimates running into the $6b to $8b range annually over the next decade, before easing into more moderate growth. Because the DCF outcome sits meaningfully above the current share price of $64.58, the math suggests the market is putting a cautious tag on those future cash streams. The recent record high close driven by networking demand and the US$1.2b Helios order helps explain why expectations have reset higher. Yet the model still indicates a gap between price and what those projected cash flows support. Find out what Hewlett Packard Enterprise could be worth using our Discounted Cash Flow (DCF) estimate.
The Hewlett Packard Enterprise Narrative: What Would Justify Today's Price?
Narratives for Hewlett Packard Enterprise pick up where the valuation puzzle leaves off and spell out what path for growth, profitability and earnings would need to play out for the stock to end up worth considerably more or less than it is today, all housed on Simply Wall St's Community page. Rather than leaning on a single multiple or one DCF result, each narrative lays out the key drivers behind its fair value view so you can later compare those assumptions with the actual results as they are reported.
Community views on Hewlett Packard Enterprise split between AI and networking upside and concern that a lot of that story is already in the price.
Bull case: 5% undervalued
"HPE's transition to an as-a-service model continues to succeed, annualized recurring revenue and software/services ARR both rose sharply..."
Discover why this Narrative puts Hewlett Packard Enterprise at 5% undervalued.
Bear case: 23% overvalued
"Although Hewlett Packard Enterprise highlights very strong AI driven networking demand, the gap between 36% networking order growth and 10% networking revenue growth points to persistent supply constraints..."
Explore why this Narrative puts Hewlett Packard Enterprise at 23% overvalued.
Hewlett Packard Enterprise's price is only one piece of the puzzle
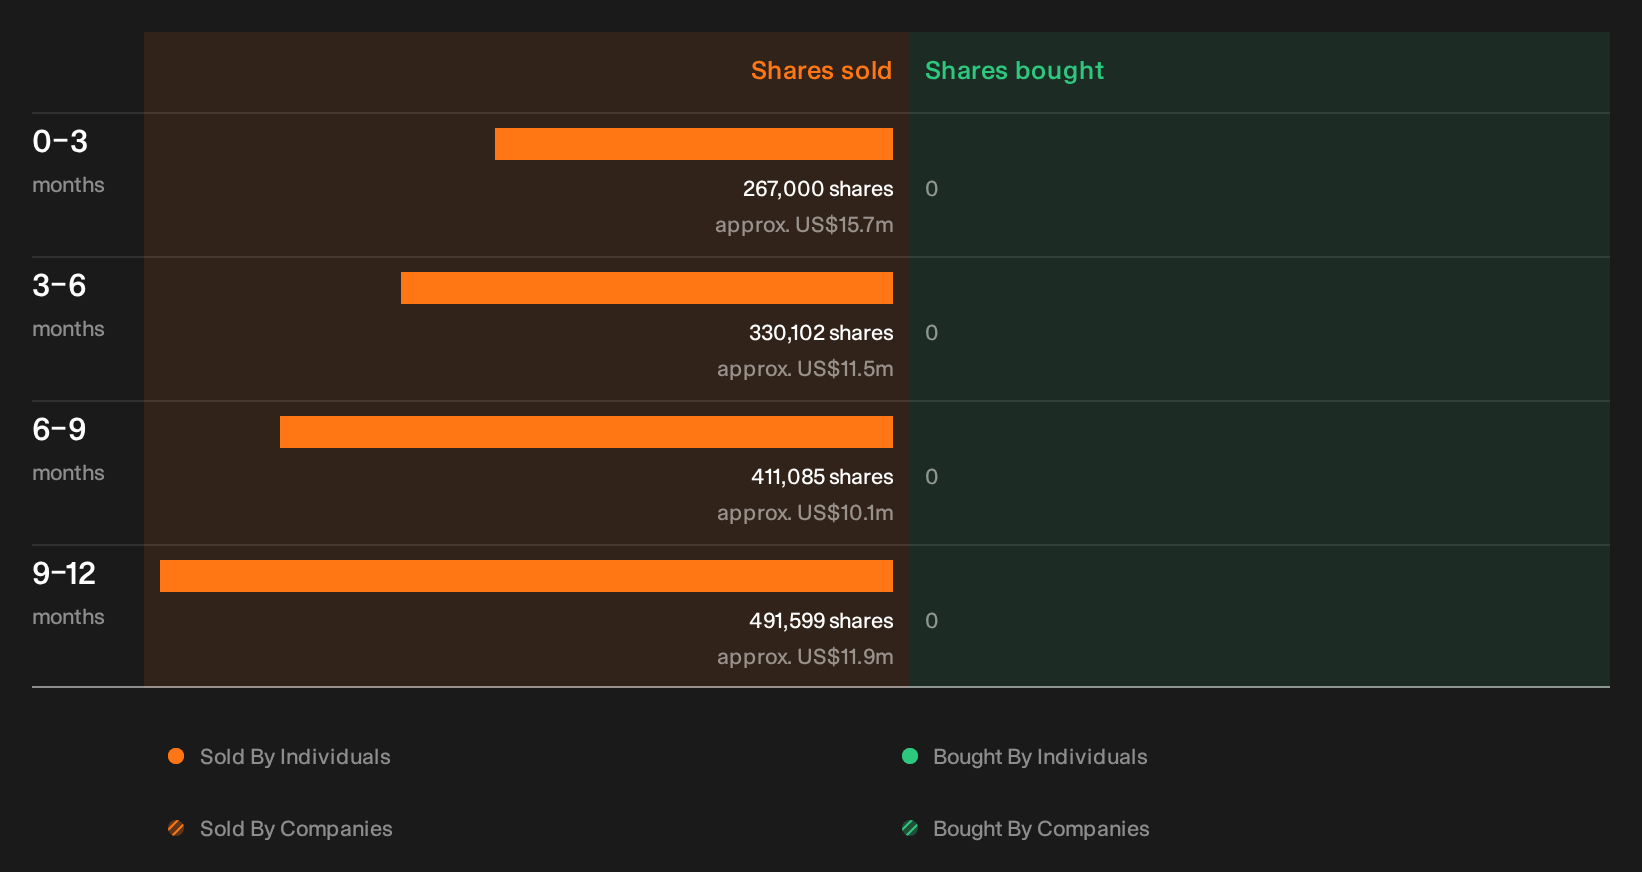
There is another signal worth checking before you make up your mind on Hewlett Packard Enterprise. Recent insider trading activity has been flagged, and the specific sellers, sizes and possible readings are all there for you to review. See the recent insider selling flagged for Hewlett Packard Enterprise.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com