


Learn Why The Bull Case For Ferrovial Stock Could Change Following Tennessee Toll Road Deal
- Ferrovial announced that commercial close has been reached with the Tennessee Department of Transportation for the I-24 Southeast Choice Lanes project near Nashville, a 26 mile public private partnership that includes a 50 year concession to finance, design, build, operate and maintain new managed lanes.
- The agreement deepens Ferrovial's role in long term U.S. toll road concessions by adding another multi decade project that ties capital, construction capability and operations into a single contract in a fast growing corridor.
- We will look at how Ferrovial's investment narrative is shaped by this 50 year I-24 Tennessee concession and long term U.S. exposure.
Scan how Ferrovial’s 50 year Tennessee concession compares with other long term infrastructure plays by reviewing our hand picked 39 power grid technology and infrastructure stocks in the same theme of transport and grid capacity expansion.
Ferrovial Investment Narrative Recap
To own Ferrovial, you need to believe in a long runway of user paid infrastructure concessions, especially in North America, and in management’s ability to recycle capital into higher returning projects. The I 24 Tennessee concession fits that story by extending visibility on contracted cash flows, although the near term driver remains execution on the existing €9.9b revenue base and the large construction backlog.
The key short term swing factor is how Ferrovial balances growth projects with its high debt load and currently thin 6% net margin. I 24 adds future optionality rather than changing that near term equation. The largest risk remains that expensive valuation multiples and aggressive earnings expectations meet project delays, weaker traffic or tighter funding conditions.
The I 24 Southeast Choice Lanes deal connects tightly with Ferrovial’s push into long term U.S. concessions, where analysts already expect earnings to grow about 14.1% a year off €592.0m of profit. A 50 year contract in a major Tennessee corridor reinforces that concession heavy mix, but construction and ramp up will consume capital well before any steady state cash generation.
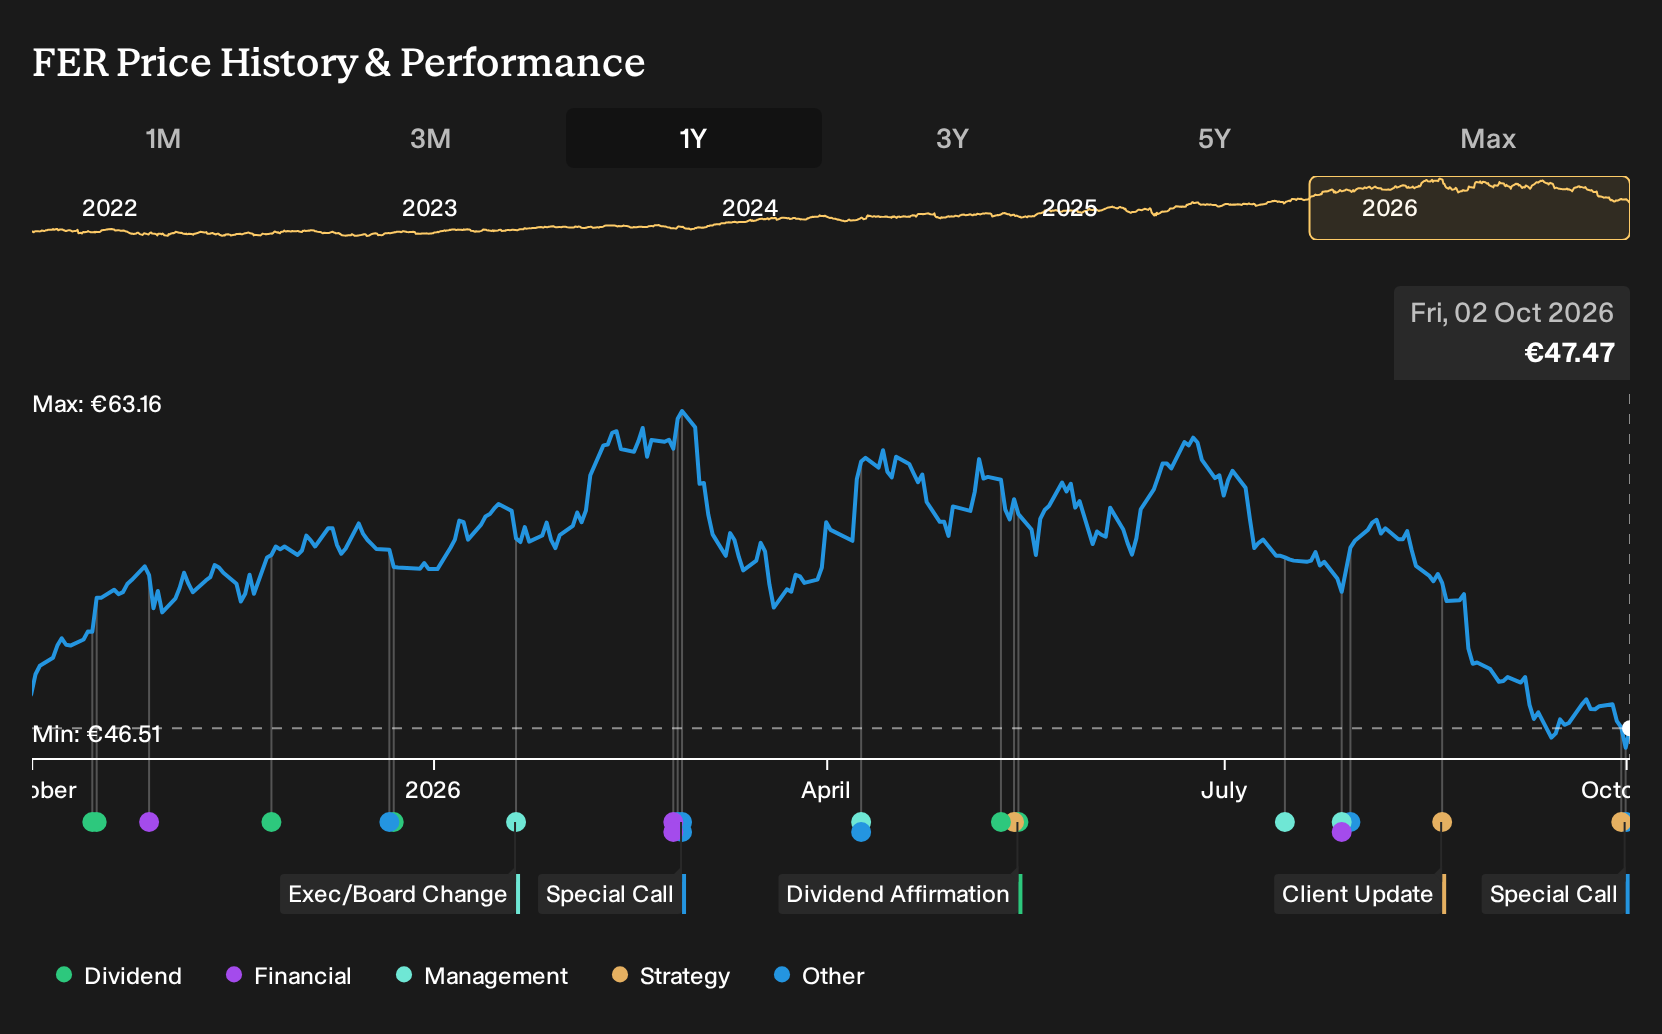
At the same time, the stock trades on a high P/E of 57.8x compared with both peers and an estimated fair P/E of 27.7x. It also sits above an internal future cash flow estimate of €43.43 per share. That puts even more weight on Ferrovial’s ability to execute projects like I 24 on time and on budget, because any disappointment on returns or traffic could matter more for such a richly valued business.
Ferrovial's narrative projects €11.4b revenue and €1.0b earnings by 2029. This projection assumes 5.0% yearly revenue growth and an earnings increase of about €408.0m from €592.0m today.
Uncover why Ferrovial's fair value indicates a 31% potential upside to its current price that could narrow quickly if Ferrovial executes smoothly on projects like I 24.
Exploring Other Perspectives
Some of the most optimistic analysts think the real kicker for Ferrovial is long haul U.S. toll exposure. Before this Tennessee news, the bullish camp was already pencilling in €12.4b revenue and €1.1b earnings by 2029. You might see the I 24 concession and wonder whether those upbeat traffic and margin stories now get even bolder.
Explore 3 other Ferrovial fair value estimates, including one that suggests as much as 60% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ferrovial research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ferrovial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ferrovial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ferrovial?
If the Ferrovial story has you thinking about how to spread risk and find other opportunities tied to solid fundamentals, the Simply Wall St Screener can help you build a broader watchlist that fits your own style.
- If capital protection is high on your list, start with a basket of companies that screen well on stability and downside metrics through the 228 resilient stocks with low risk scores.
- If value is your focus, check companies that pair quality fundamentals with prices that look appealing using the 192 high quality undervalued stocks.
- If you want to back stronger balance sheets, compare firms with healthier leverage and funding profiles by scanning the list of solid balance sheet and fundamentals (206 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com