


What Expro's 37% Gain Still Needs To Prove
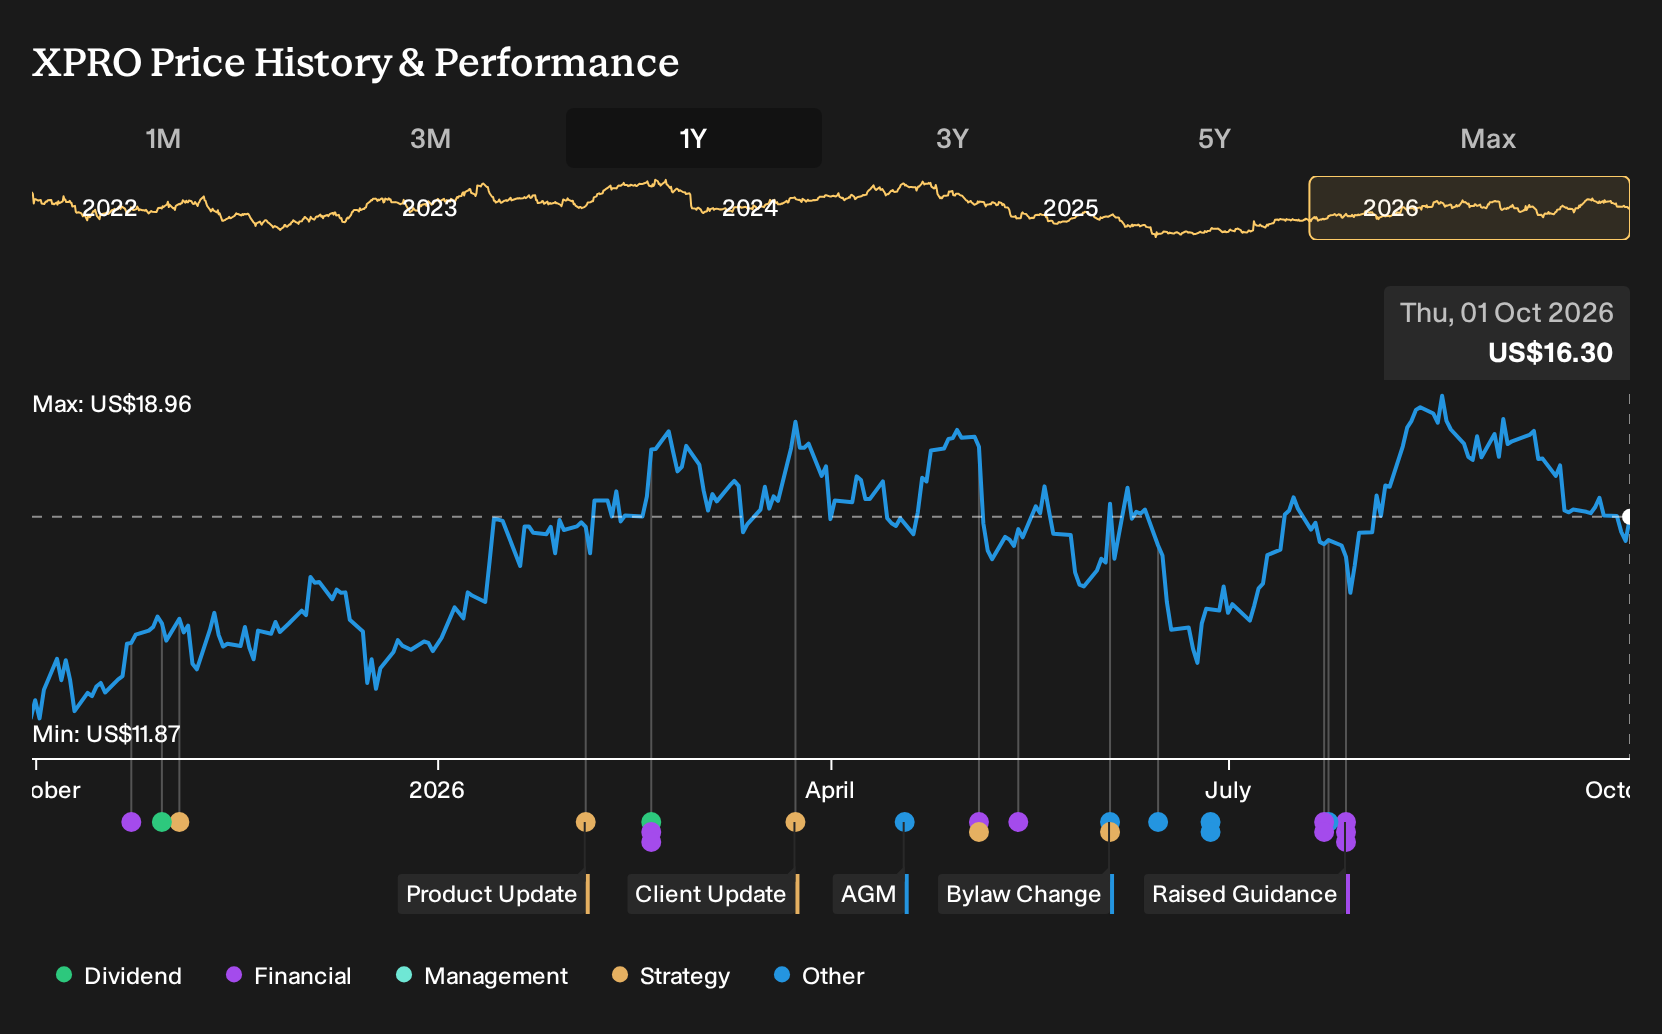
Expro just closed the purchase of Enhanced Drilling, bringing managed pressure drilling and riserless mud recovery into its toolkit while Q2 2026 results showed revenue and net income under pressure. Investors who held Expro over the past year are up 37.3%, including dividends. If you were deciding back on 1 October 2025, what beliefs about these kinds of contracts, tools and acquisitions would have justified buying in?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Expro. Zero in on 28 high quality undervalued stocks for companies trading below our estimates.
The Two Expro Narratives Investors Had To Weigh
The shares cost US$12.27 at the start of the period, and anyone looking at Expro then had to choose between two very different stories about the same business.
The bullish narrative pinned fair value at US$15 and leaned on a belief that offshore project approvals and AI-enabled tools could accelerate revenue, backlog, and net margin expansion, supported by a balance sheet with liquidity approaching US$500 million for faster acquisitions.
The bearish view pointed to a fair value of US$10 and focused on accelerating global decarbonization, higher regulatory costs, and exposure to offshore cycles that could pressure Expro's addressable market and compress oilfield service margins over time.
What The Evidence Around Expro Actually Tested
The Enhanced Drilling purchase gave Expro new managed pressure drilling and riserless mud recovery tools, which leaned toward the optimistic case about contracts and technology. Quarterly figures pulled the other way. Revenue moved from US$422.74 million in Q2 2025 to US$393.18 million in Q2 2026, while net margin slipped from 4.3% to 0.5%. The evidence cut both ways.
The key lesson is simple. When a story leans on higher value work from new tools and deals, you need to track whether net margin and backlog progress together, not just whether new products arrive.
What Expro's Run Up 37% Has Not Resolved Yet
Expro trades at US$16.3 today, with this Narrative’s Fair Value sitting above that quote based on its own assumptions rather than hard fact. The argument leans on offshore project approvals, AI-enabled tools and balance sheet flexibility to support higher value work and stickier customer spending.
The Narrative contends today’s price still does not fully credit the idea that Expro could translate these tools and contracts into meaningfully higher recurring revenue and net margin over time.
"Analysts broadly expect margin improvement from investments in automation and cost-effective technologies, but the emergence and early success of Expro's industry-first AI and automation-enabled tools, such as the Remote Clamp Installation System and fully remote cementing, have the potential to fundamentally transform operational workflows, enabling breakthrough net margin expansion and differentiated pricing power as adoption scales."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 24% below our estimate - targets data centre budgets shifting toward high power AI racks and software ecosystems.
- Company 2 - 37% below our estimate - wins subsea projects that bundle faster tieback delivery with long duration service contracts.
- Company 3 - 44% below our estimate - supports product makers facing tighter safety rules and more complex failure analysis demands.
Those are three of them. See all 25 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com