


Our Pick Of The Best Japanese Owner Led Stocks In October 2026
Tokyo inflation hitting 2.7% in September has put Japanese interest rates back in the spotlight and reminded investors that easy money does not last forever. When borrowing costs feel less certain, companies where the original founder still holds the wheel can offer a different kind of comfort. This article highlights three founder-led Japanese stocks that show how deep owner commitment can align with long term shareholder value.
The three founder-led Japanese stocks below are only a small sample, and the full screen surfaced 99 more businesses where the person who built the enterprise still has serious skin in the game and a story that is not covered here. If you want to identify and analyze the founder-led opportunities that best fit your own conviction level, head straight to the Founder-Led Companies screener.
Sansan (TSE:4443)
Overview: Sansan provides cloud-based contact, invoice and contract management tools that grew out of its founder-led focus on business relationships.
Operations: Sansan generates about ¥46,847 million from its Sansan and Bill One segment and ¥6,720 million from Eight, almost entirely in Japan at ¥53,761 million.
Market Cap: ¥260 billion
Sansan puts its founder’s original contact-management vision at the center of a broader cloud toolkit for invoices and contracts, which helps explain why earnings and margins have recently moved sharply higher under the same leadership. For investors who like founder-led stories, the real question is what happens when that focus is tested by one unseen pressure on profitability.
When that pressure on profitability hits, you can size up the trade off between growth and earnings quality in the DCF valuation analysis for Sansan that surfaces what the headline numbers miss.
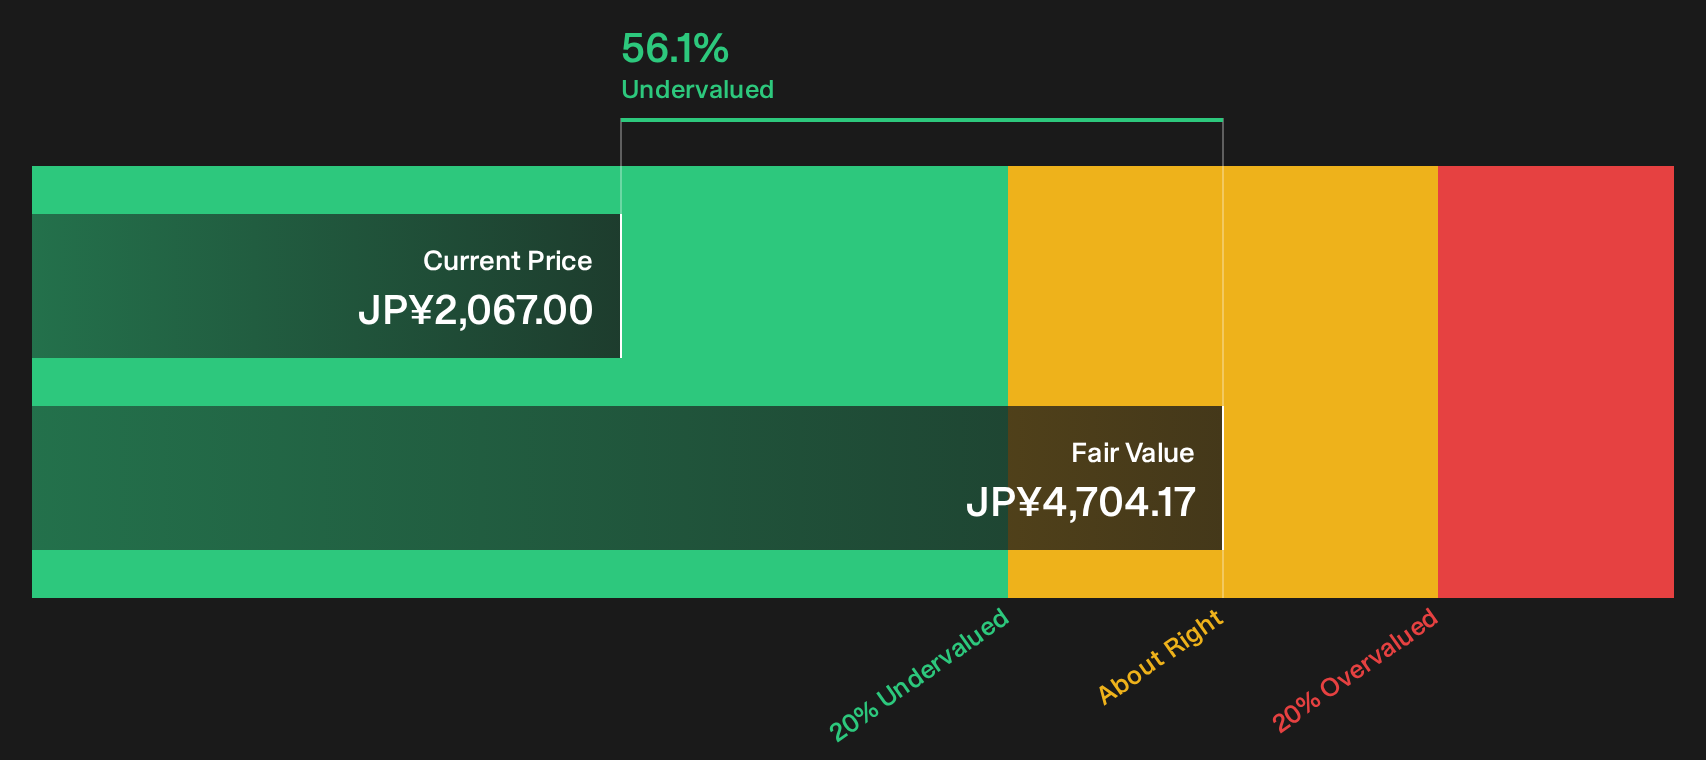
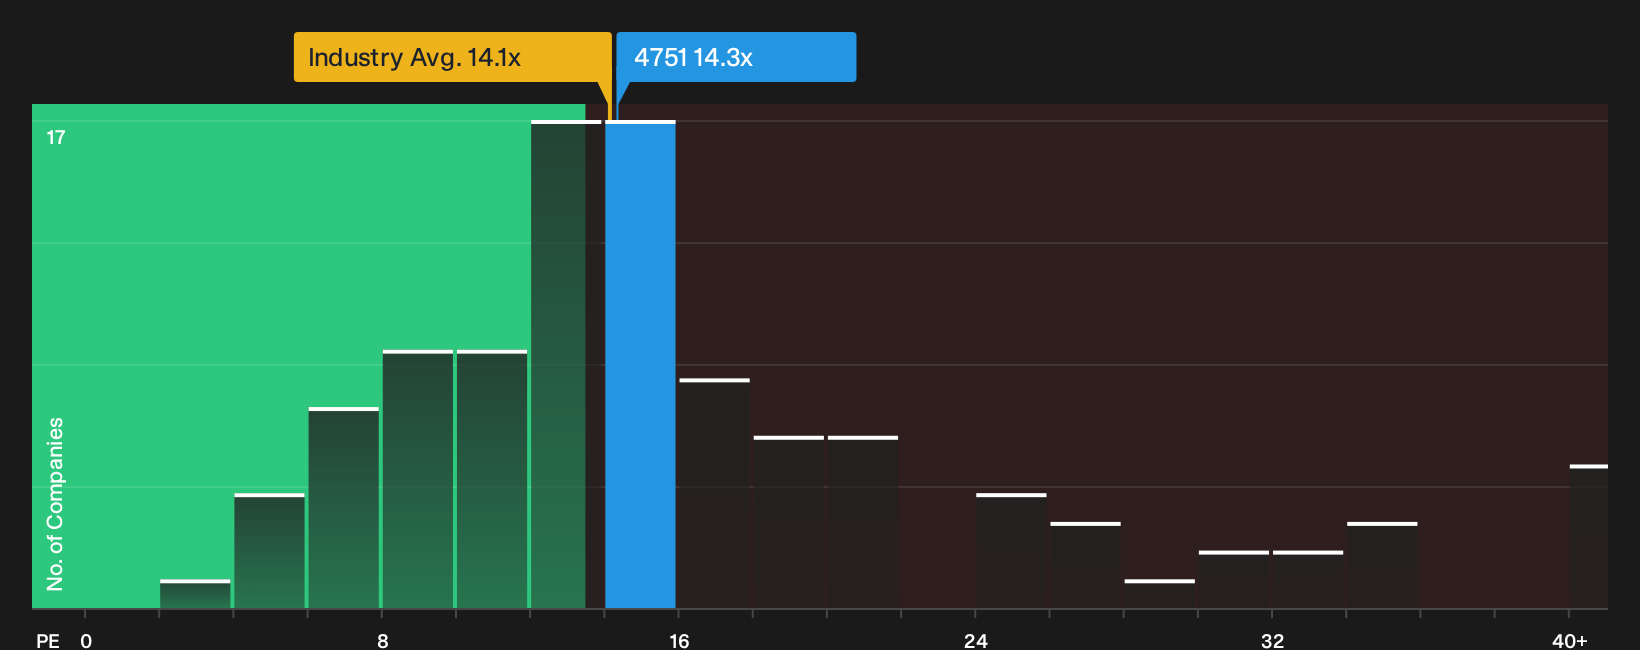
CyberAgent (TSE:4751)
Overview: CyberAgent runs founder-led media, internet advertising and gaming platforms such as Ameba that anchor Japan-focused digital content and marketing.
Operations: CyberAgent generates roughly ¥478,159 million from Internet Advertising, ¥269,737 million from Games and ¥246,561 million from Media & IP, almost entirely in Japan at ¥951,309 million.
Market Cap: ¥624.2 billion
CyberAgent matters for this founder-led screen because Susumu Fujita still shapes how Ameba’s content, advertising tools and games evolve together over time.
"The increasingly strict privacy regulations and data protection laws in both Japan and globally are likely to constrain CyberAgent's ability to maintain its current effectiveness in digital advertising. This may raise compliance costs and erode its core ad technology value, which could weaken revenue growth and ultimately impact operating profit margins over time."
The key question for CyberAgent is how its founder responds if a single assumption about platform monetisation no longer holds.
If that assumption breaks, you will want the full context in the full narrative for CyberAgent, which explains how CyberAgent could still move beyond those risks.
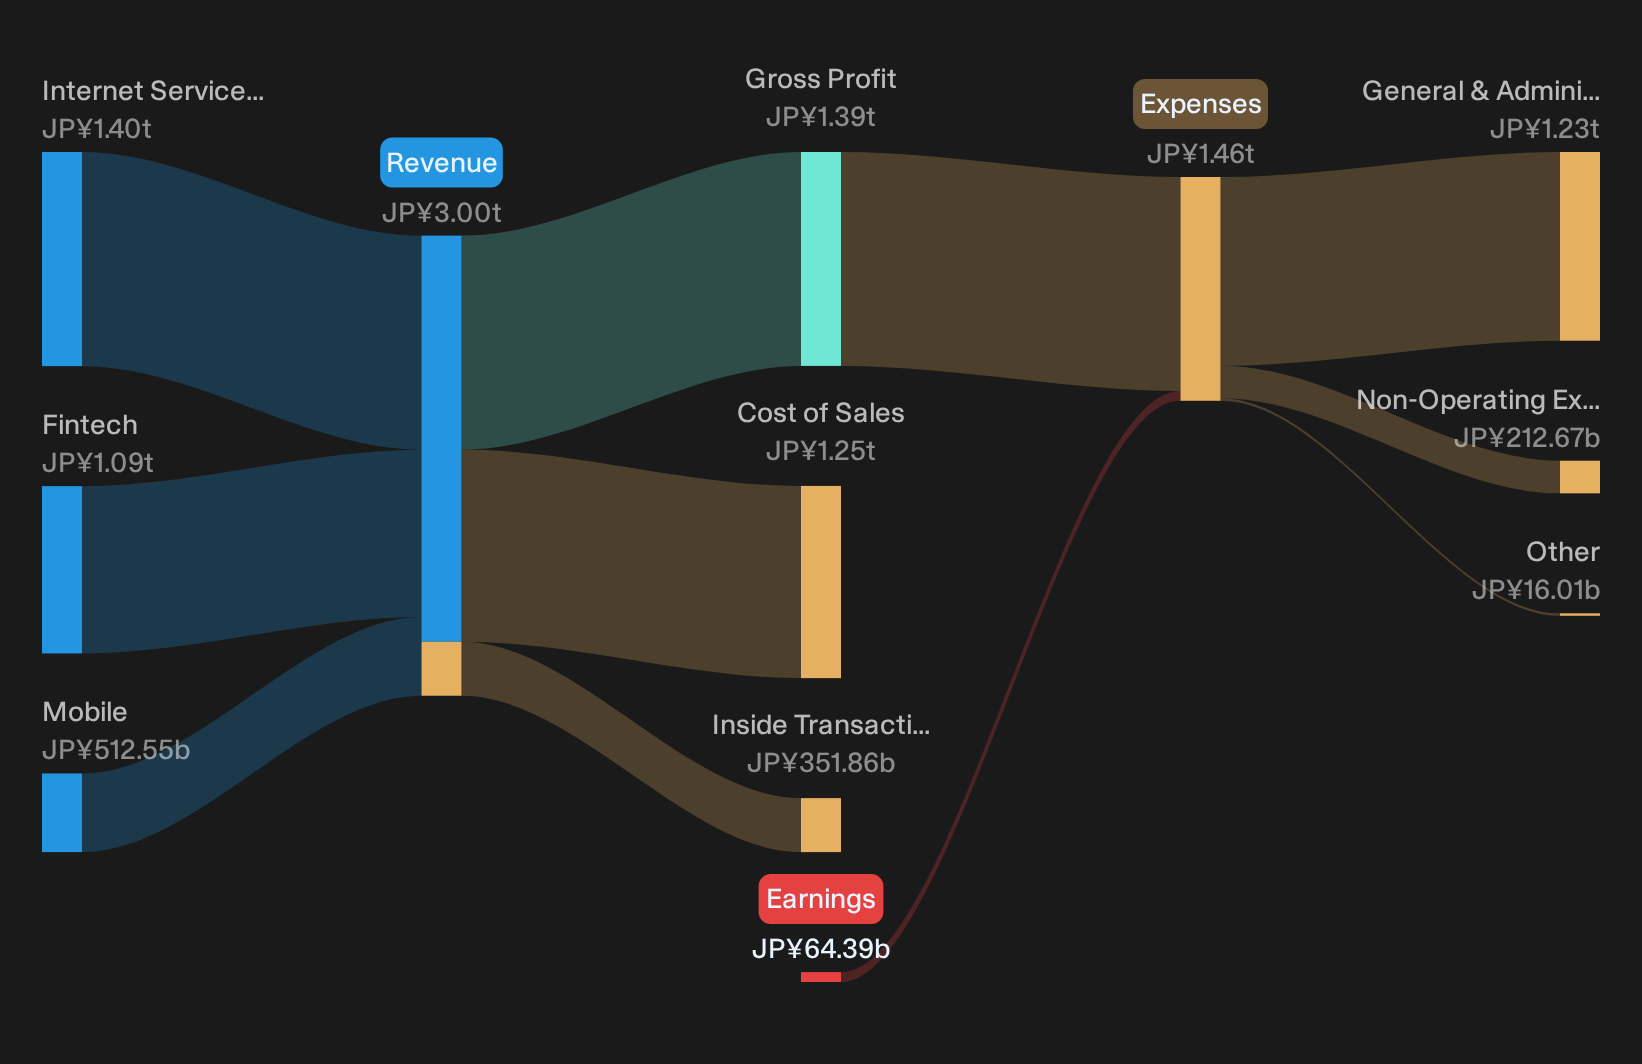
Rakuten Group (TSE:4755)
Overview: Rakuten Group runs founder-led e-commerce, payments and financial services platforms built around Rakuten Ichiba, Rakuten Card, Rakuten banking and Rakuten Pay.
Operations: Rakuten Group generates about ¥1.40t from Internet Services, ¥1.09t from FinTech and ¥513b from Mobile, with internal offsets of ¥352b.
Market Cap: ¥1.45t
Rakuten Group matters for this founder-led screen because Kazuo Mikitani still personally steers the marketplace and fintech engines that shape the wider ecosystem.
"AI-driven operational efficiencies, targeting a 31% reduction in customer support costs, are anticipated to improve net margins by boosting profitability across Rakuten's operational segments."
What really moves the dial for Rakuten Group now is how one unresolved capital allocation choice filters through to those improving margins.
That capital choice is the real hinge, and the full narrative for Rakuten Group shows how Rakuten Group’s ecosystem, funding needs and margin ambitions could be decoupling in ways the headline quote only hints at.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once the breakout stories are widely known, the easy entry points are gone. Scan new momentum while it matters and aim to get in early.
- Spot sturdy balance sheets backing real businesses before they get fully priced by using the curated list of solid balance sheet and fundamentals (23 results).
- Look for potential sector momentum at an early stage by checking the curated 19 nuclear energy infrastructure stocks while these infrastructure stories may still be under the radar.
- Track where cash generation meets metal exposure by reviewing the pre-filtered 36 elite gold producer stocks before those producers attract wider market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com