


Is Expanded Arcadis Partnership Altering The Investment Case For Autodesk (ADSK)?
- In September 2026, Arcadis N.V. announced an expanded collaboration with Autodesk to combine Arcadis' domain expertise with Autodesk's Design and Make platform and Autodesk AI across built and natural assets.
- A key focus is Arcadis feeding its own Model Context Protocol and project knowledge into Autodesk Assistant so AI outputs align tightly with real client standards, sustainability goals and project conditions.
- The discussion then turns to how Autodesk's investment narrative could be affected by this deeper Arcadis AI collaboration around connected project data.
Scan similar AI driven design and infrastructure plays by checking out our hand picked 90 AI infrastructure stocks, which are riding the same data heavy trends Autodesk is helping Arcadis harness.
Autodesk Investment Narrative Recap
To consider owning Autodesk, you need to believe its core AEC and design software continues to pull more work into cloud based, AI supported workflows that drive sticky subscriptions. The expanded Arcadis partnership supports that view by putting Autodesk tools deeper into real world infrastructure projects. In the near term, the key swing factor remains how quickly customers adopt these AI infused cloud platforms versus cheaper or open source options.
The biggest near term risk stays the same. Intense competition in AI design tools and lower cost rivals could pressure pricing if Autodesk slips on execution or product quality. The Arcadis news does not remove that risk. It mainly reinforces that Autodesk is trying to keep its technology embedded in complex customer workflows where switching is harder.
The Arcadis announcement is closely linked to one of Autodesk's main catalysts: wider use of its cloud and AI products across AEC. By wiring Arcadis' Model Context Protocol into Autodesk Assistant and running projects like See Through Walls on Autodesk's platform, the company is pushing more real project data and day to day decisions into its ecosystem.
For you, the operational question is whether partnerships like this translate into higher usage of subscriptions such as Autodesk Construction Cloud and related design tools, without triggering meaningful churn or pricing strain. If execution is solid, these kinds of embedded deployments can support the existing outlook for recurring revenue and earnings, while AI competition and regulatory demands remain key risks.
Autodesk's analyst narrative points to revenues of US$10.7b and earnings of US$2.6b by 2029, off current earnings of US$1.6b. This implies forecast revenue growth of 11.2% per year and an earnings increase of US$1.0b.
Uncover how Autodesk's fair value indicates a 46% potential upside to its current price before the market closes that gap.
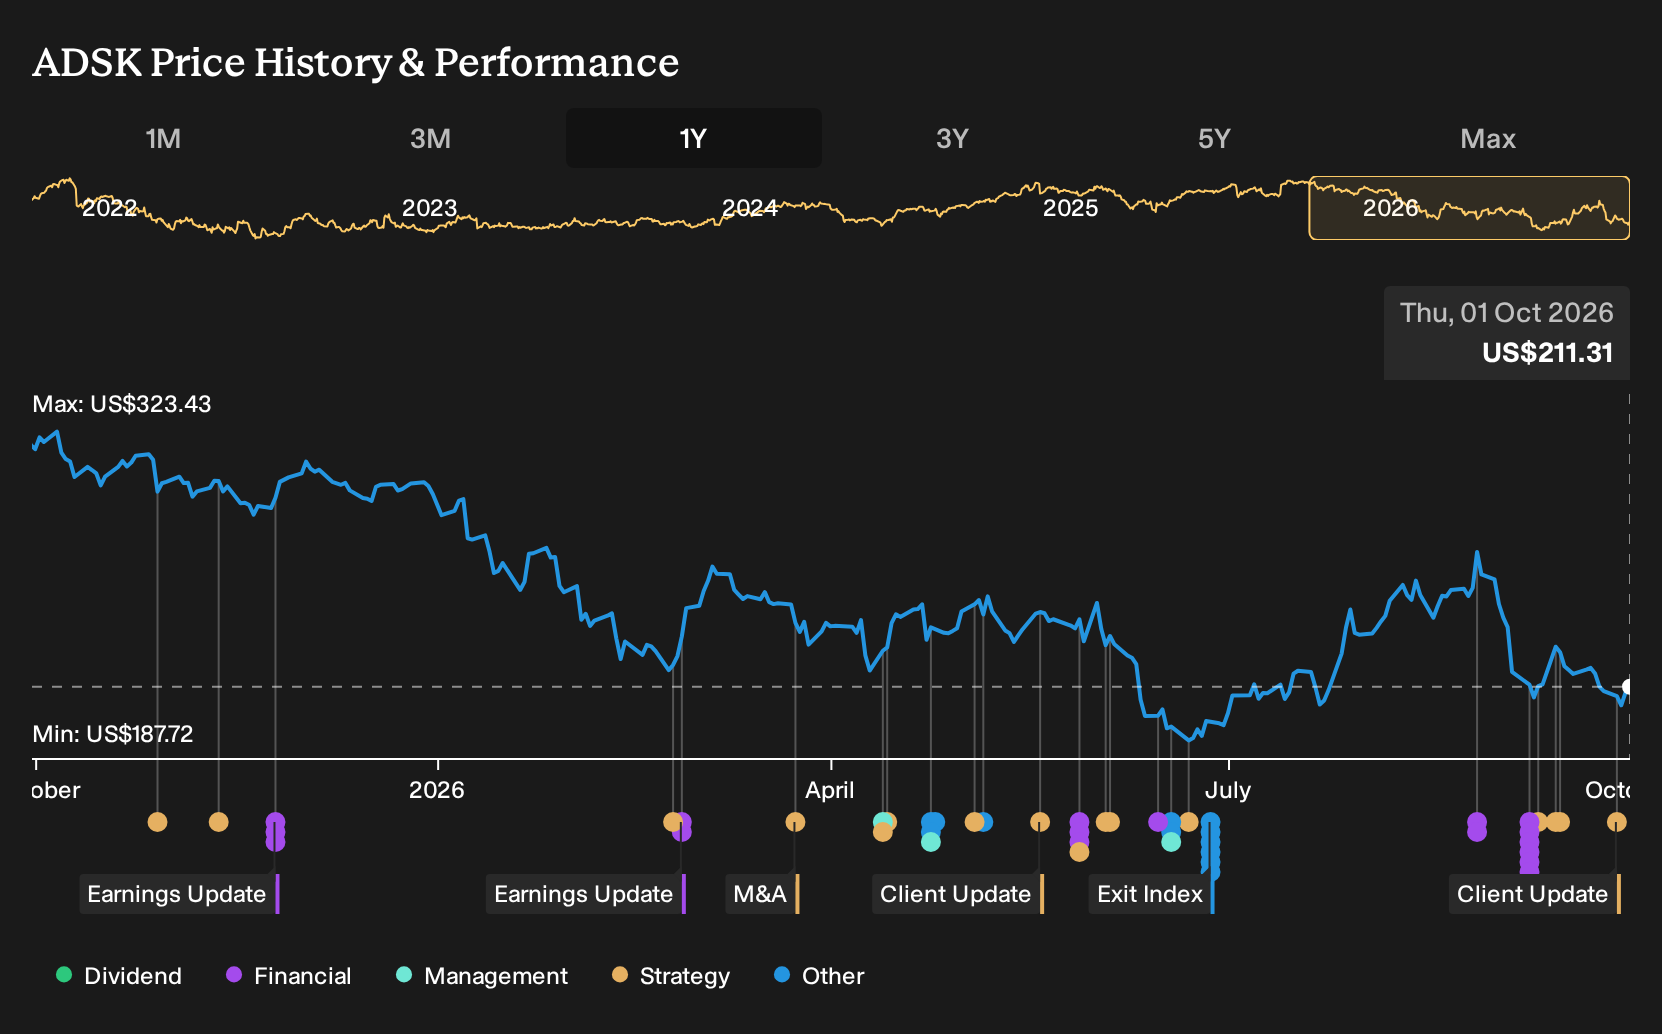
Exploring Other Perspectives
Some analysts view the Autodesk and Arcadis AI collaboration through a more optimistic lens. They had already pencilled in revenue of about US$11.2b and earnings of US$2.8b by 2029, with a P/E of 34.6x, before this update. You can treat this collaboration as a prompt to compare those bullish assumptions with your own view.
Explore 6 other Autodesk fair value estimates, including one that suggests as much as 75% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Autodesk research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Autodesk. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Autodesk's overall financial health at a glance.
Looking For More Ideas Beyond Autodesk?
If the Autodesk and Arcadis story has you thinking about where else AI, data, and solid fundamentals might intersect, the Simply Wall St Screener can help you scan the market quickly without losing sight of quality.
- For investors who want potential mispricing with quality behind it, start by reviewing our 28 high quality undervalued stocks and see which businesses align with your own return and risk expectations.
- If capital preservation and steadier profiles matter more to you than headline growth, filter for 31 resilient stocks with low risk scores to focus on companies with more resilient characteristics.
- When you want strong fundamentals and balance sheets that can support future plans without stretching finances, try the list of solid balance sheet and fundamentals (25 results) as a way to surface sturdier candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com