


Is Prysmian Stock Fully Priced For Grid And Electrification Growth
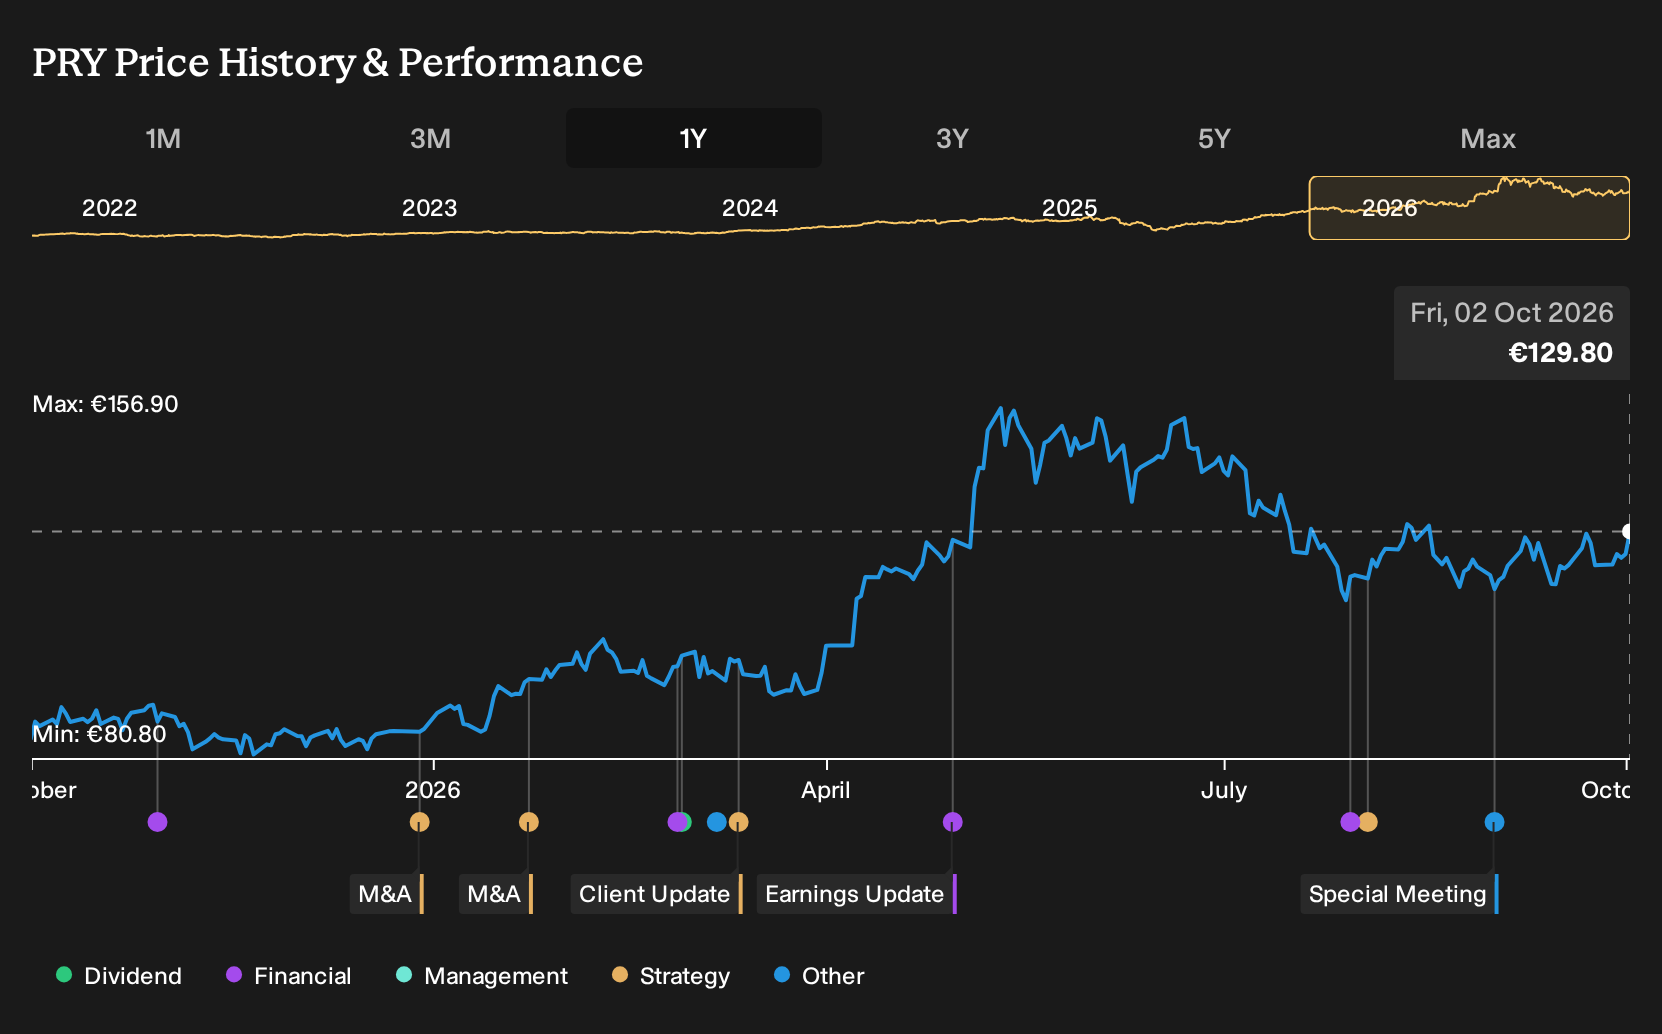
- Prysmian’s recent share price move has refocused attention on whether its valuation is supported by future cash flows and execution on large grid and digital infrastructure projects.
- The key question now is how much of Prysmian’s electrification, data center and tariff-supported demand story is already reflected in expectations.
- We will now look at how Prysmian’s investment narrative is affected by valuation debates tied to its electrification and grid exposure.
Scan how Prysmian’s electrification and grid story compares with other power grid and infrastructure plays in our hand picked 39 power grid technology and infrastructure stocks.
Prysmian Investment Narrative Recap
To own Prysmian, you really need to buy into a simple idea. Large scale spending on electrification, long distance transmission and data infrastructure keeps translating into healthy orders across Transmission, Power Grid, Electrification and Digital Solutions. The recent share price jump does not change that operational story on its own. It just raises the bar for what counts as “good enough” execution.
The near term swing factor is delivery on big U.S. and European grid and data center projects, where timing and pricing will drive cash generation. The biggest current risk sits in policy and project execution. Any reversal of supportive U.S. tariffs, or delays and cancellations on high profile transmission lines, would hit margins and backlog quality.
With no fresh company announcements tied directly to this latest price move, the most relevant reference point remains Prysmian’s ongoing capacity expansion and M&A integration push. Management is working to fold in Encore Wire and Channell and align them with the group’s electrification and digital infrastructure focus. That integration effort underpins much of the long term growth narrative investors are debating today.
This integration phase is also where execution risk lives. Synergies, capex discipline and product mix shifts toward higher margin premium and ESG linked cables are all operational levers that need to show up in earnings and cash flows. For you as a shareholder, the key question is whether Prysmian can translate supportive demand drivers, tariff protection and a larger footprint into consistently stronger returns without letting debt and project risk get ahead of it.
Prysmian Forecasts Behind The Valuation Debate
Prysmian's narrative projects €28.3b in revenue and €2.3b in earnings by 2029. This assumes 9.2% yearly revenue growth and an earnings increase of about €0.9b from €1.4b today.
Discover why Prysmian's fair value indicates a 25% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
You might see Prysmian very differently if you focus on the bullish catalyst of faster data center demand. The most optimistic analysts were already pencilling in €30.7b of revenue and €2.5b of earnings by 2029 before this price move. That is far above consensus, and today’s news could push those views to shift again.
Explore 6 other Prysmian fair value estimates, including one that suggests as much as 45% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Prysmian research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Prysmian. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Prysmian's overall financial health at a glance.
Looking for more Prysmian style investment ideas?
If the Prysmian story has you thinking about where else electrification, infrastructure and solid execution could matter, it can help to line it up against a broader watchlist. The Simply Wall St Screener lets you quickly filter for different qualities so you can focus on a small set of potential opportunities instead of a sea of tickers.
- If you want financially robust businesses that can better handle shocks, start with a list of solid balance sheet and fundamentals (207 results) and see which ones deserve a place on your radar.
- For investors who care most about quality at a sensible price, use the 191 high quality undervalued stocks and compare their earnings power with what the market is currently willing to pay.
- If you are hunting for new ideas away from the usual crowd, the 616 high quality undiscovered gems can surface lesser known stocks with fundamentals worth a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com