


3 Stocks Estimated To Be Up To 42.9% Below Intrinsic Value
Over the last 7 days, the United States market has experienced a slight drop of 1.0%, yet it remains up by 11% over the past year, with earnings projected to grow by 17% annually. In this environment, identifying stocks that are potentially undervalued can be a strategic move for investors seeking opportunities that align with these growth forecasts.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $62.65 | $125.17 | 49.9% |
| Provident Financial Services (PFS) | $22.35 | $43.01 | 48% |
| Old Republic International (ORI) | $37.49 | $72.35 | 48.2% |
| Northeast Bank (NBN) | $124.70 | $247.37 | 49.6% |
| M&T Bank (MTB) | $217.35 | $421.90 | 48.5% |
| KeyCorp (KEY) | $20.05 | $39.19 | 48.8% |
| Insteel Industries (IIIN) | $29.04 | $56.92 | 49% |
| Futu Holdings (FUTU) | $106.43 | $209.92 | 49.3% |
| Fulton Financial (FULT) | $22.59 | $44.83 | 49.6% |
| Baker Hughes (BKR) | $55.62 | $106.72 | 47.9% |
Below we spotlight a couple of our favorites from our exclusive screener.
Ameriprise Financial (AMP)
Overview: Ameriprise Financial, Inc. operates as a diversified financial services company both in the United States and internationally, with a market capitalization of approximately $43.49 billion.
Operations: The company's revenue is primarily derived from Advice & Wealth Management ($12.91 billion), Retirement and Protection Solution ($4.02 billion), and Asset Management ($3.80 billion).
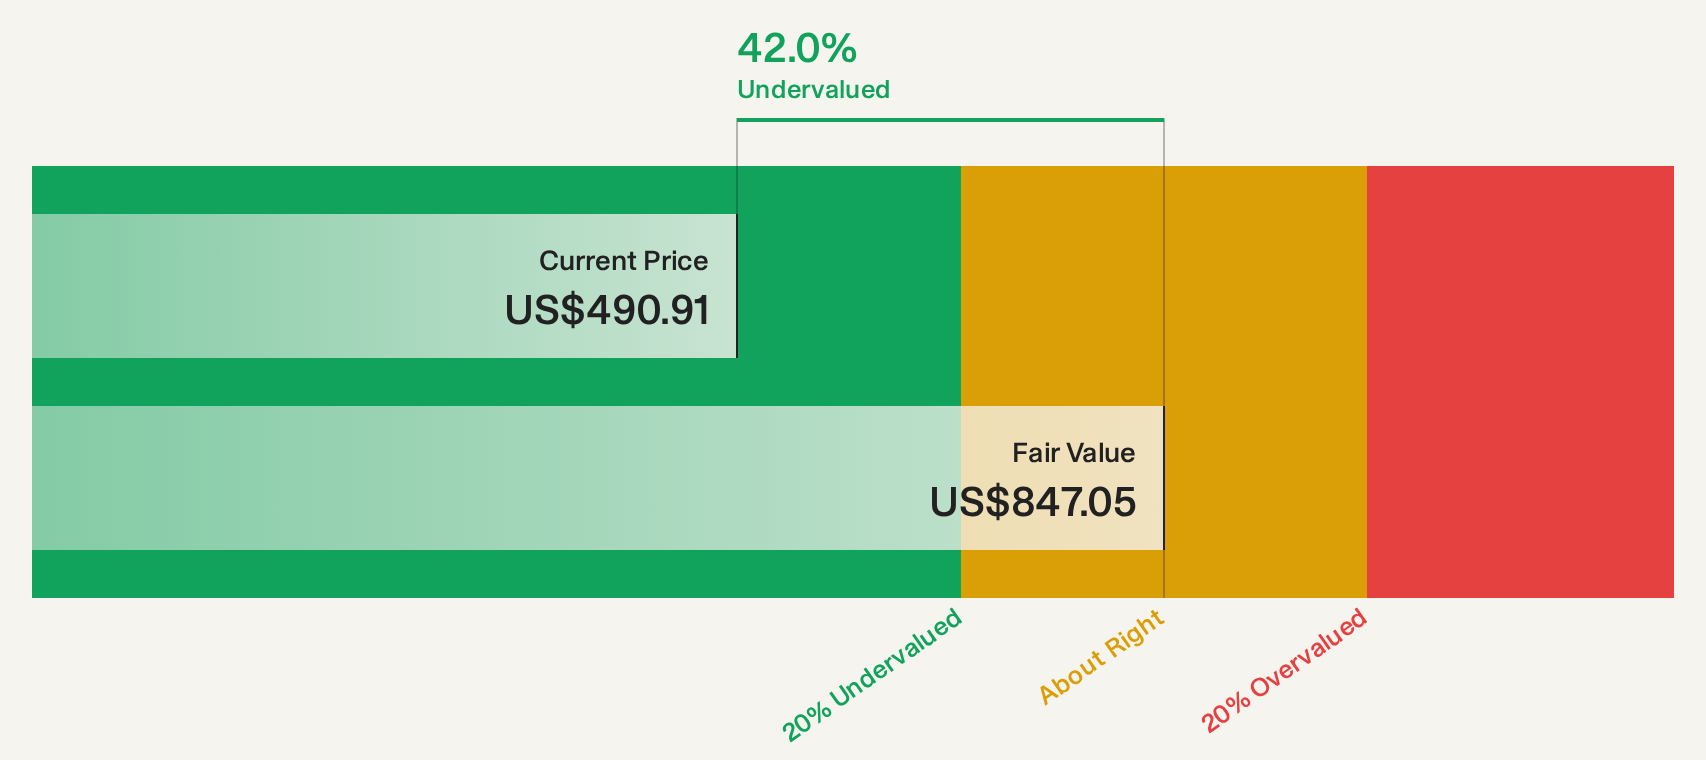
Estimated Discount To Fair Value: 41.6%
Ameriprise Financial is trading at 41.6% below its estimated fair value, with a stock price of US$494.82 against a future cash flow valuation of US$846.72. Despite slower revenue growth forecasts compared to the broader market, Ameriprise's earnings have grown annually by 8.3% over the past five years and are projected to continue growing at 6.47%. Recent buybacks totaling $3.44 billion enhance shareholder value, complementing strong earnings performance and high return on equity forecasts of 48.2%.
- In light of our recent growth report, it seems possible that Ameriprise Financial's financial performance will exceed current levels.
- Take a closer look at Ameriprise Financial's balance sheet health here in our report.
EMCOR Group (EME)
Overview: EMCOR Group, Inc. operates in the United States and the United Kingdom, offering electrical and mechanical construction as well as facilities, building, and industrial services, with a market cap of approximately $33.28 billion.
Operations: EMCOR Group's revenue segments include United States Mechanical Construction and Facilities Services at $8.17 billion, United States Electrical Construction and Facilities Services at $5.77 billion, United States Building Services at $3.25 billion, and United States Industrial Services at $1.38 billion.
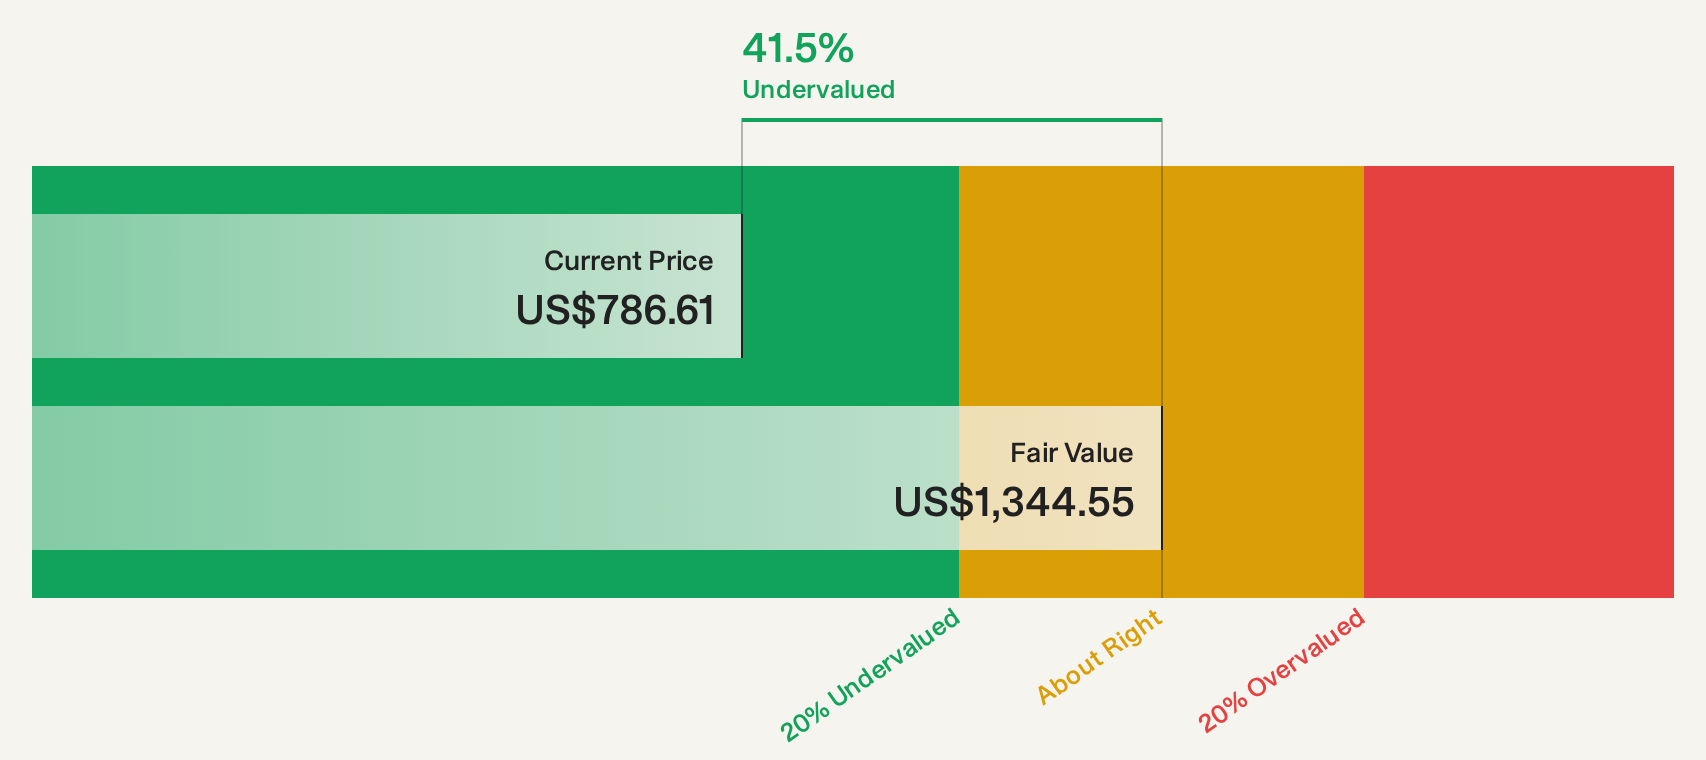
Estimated Discount To Fair Value: 42.9%
EMCOR Group is trading at 42.9% below its estimated fair value, with a stock price of US$769.03 against a future cash flow valuation of US$1,347.32. Despite slower revenue growth forecasts than the broader market, EMCOR's earnings have grown significantly by 31.5% annually over the past five years and are projected to continue growing at 12.8%. Recent earnings guidance upgrades and strategic acquisitions support robust cash flow generation and shareholder returns through dividends and investments in core competencies.
- Insights from our recent growth report point to a promising forecast for EMCOR Group's business outlook.
- Navigate through the intricacies of EMCOR Group with our comprehensive financial health report here.
Ferguson Enterprises (FERG)
Overview: Ferguson Enterprises Inc. distributes essential water and air solutions to specialized professionals in the United States and Canada, with a market cap of approximately $43.07 billion.
Operations: The company generates revenue of $31.45 billion from the distribution of plumbing and heating products across the United States and Canada.
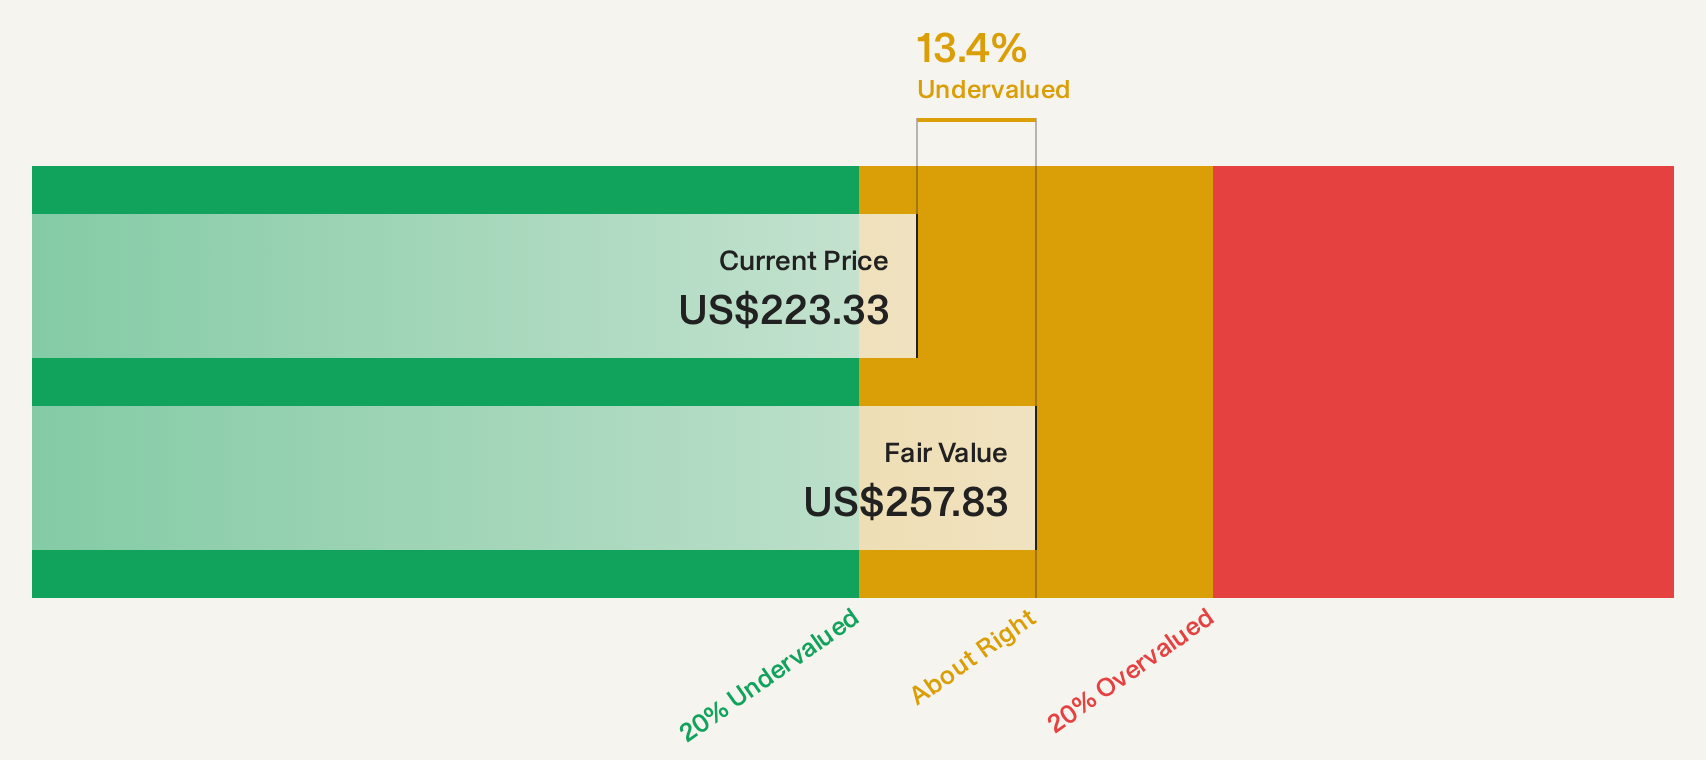
Estimated Discount To Fair Value: 14.5%
Ferguson Enterprises is trading at US$221.49, below its estimated future cash flow value of US$259.02, indicating potential undervaluation based on cash flows. Despite high debt levels and significant insider selling recently, the company has demonstrated earnings growth of 12.1% over the past year and forecasts an 8.4% annual increase in earnings, albeit slower than the broader market's growth rate. Recent strategic financing activities support its acquisition plans and financial stability amidst fluctuating market conditions.
- Our growth report here indicates Ferguson Enterprises may be poised for an improving outlook.
- Get an in-depth perspective on Ferguson Enterprises' balance sheet by reading our health report here.
Seize The Opportunity
- Unlock more gems! Our Undervalued US Stocks Based On Cash Flows screener has unearthed 102 more companies for you to explore.Click here to unveil our expertly curated list of 105 Undervalued US Stocks Based On Cash Flows.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com