


ERAMET (ENXTPA:ERA) Plans Lithium Expansion, Is The Discount Too Deep?
Eramet (ENXTPA:ERA) has flagged a potential US$350 million outlay to expand its Centenario Ratones lithium operation in Argentina, targeting an extra 11,000 tonnes of annual lithium carbonate capacity under the country’s RIGI incentive regime.
The lithium expansion news arrives against a weak price backdrop for ERAMET, with the share price down 28.9% year to date and 4.7% over the past three months, while the 1-year total shareholder return has declined 22.6%, indicating softer momentum despite the new growth push.
Scan ERAMET alongside other potential lithium beneficiaries by reviewing our hand picked 33 best rare earth metal stocks that could be positioned for the next demand upswing in battery materials.
Eramet now trades at a clear discount to both analyst targets and an estimated fair value, yet the group is loss making and sentiment is weak. Is that caution misplaced, or exactly what the balance sheet and earnings justify?
Preferred Price-to-Sales of 0.4x: Is it justified?
On simple sales-based metrics, ERAMET looks inexpensive. The share price closed at €43.78, while the stock trades on a P/S of 0.4x against both its direct peers and the wider European metals and mining group.
The P/S ratio compares the company’s market value to its annual revenue. For a diversified miner like ERAMET, which generates €3,006.0m of sales across manganese, nickel, lithium and mineral sands, this measure shows how much investors are paying for each euro of top line, even when earnings are in the red.
Relative to the sector, the gap is clear. The broader European metals and mining industry averages a P/S of 1.1x and the peer set sits nearer 1.3x, while an estimated fair P/S for ERAMET is 2.1x. The current 0.4x level implies the market is pricing in far weaker prospects than that fair ratio suggests, and indicates there could be significant room for sentiment to shift toward that higher mark if forecasts play out as expected.
Explore the SWS fair ratio for ERAMET.
Result: Price-to-Sales of 0.4x (UNDERVALUED)
Still, ERAMET carries clear risks, including ongoing losses of €520.0m and a share price that has already fallen sharply over both the 1-year and 5-year periods.
Find out about the key risks to this ERAMET narrative.
Another View on ERAMET’s Value
The earlier P/S work suggests ERAMET looks inexpensive relative to its sales. A different lens tells a similar story. Our DCF model indicates a future cash flow value of €75.08 per share compared with the current €43.78 price. This implies the stock is trading well below that estimate.
The gap between those two numbers highlights risk as much as potential. It raises a simple question for you as an investor: is the discount a warning about execution, balance sheet pressure and lithium project timing, or is the market overreacting to recent losses and weak sentiment?
Look into how the SWS DCF model arrives at its fair value.
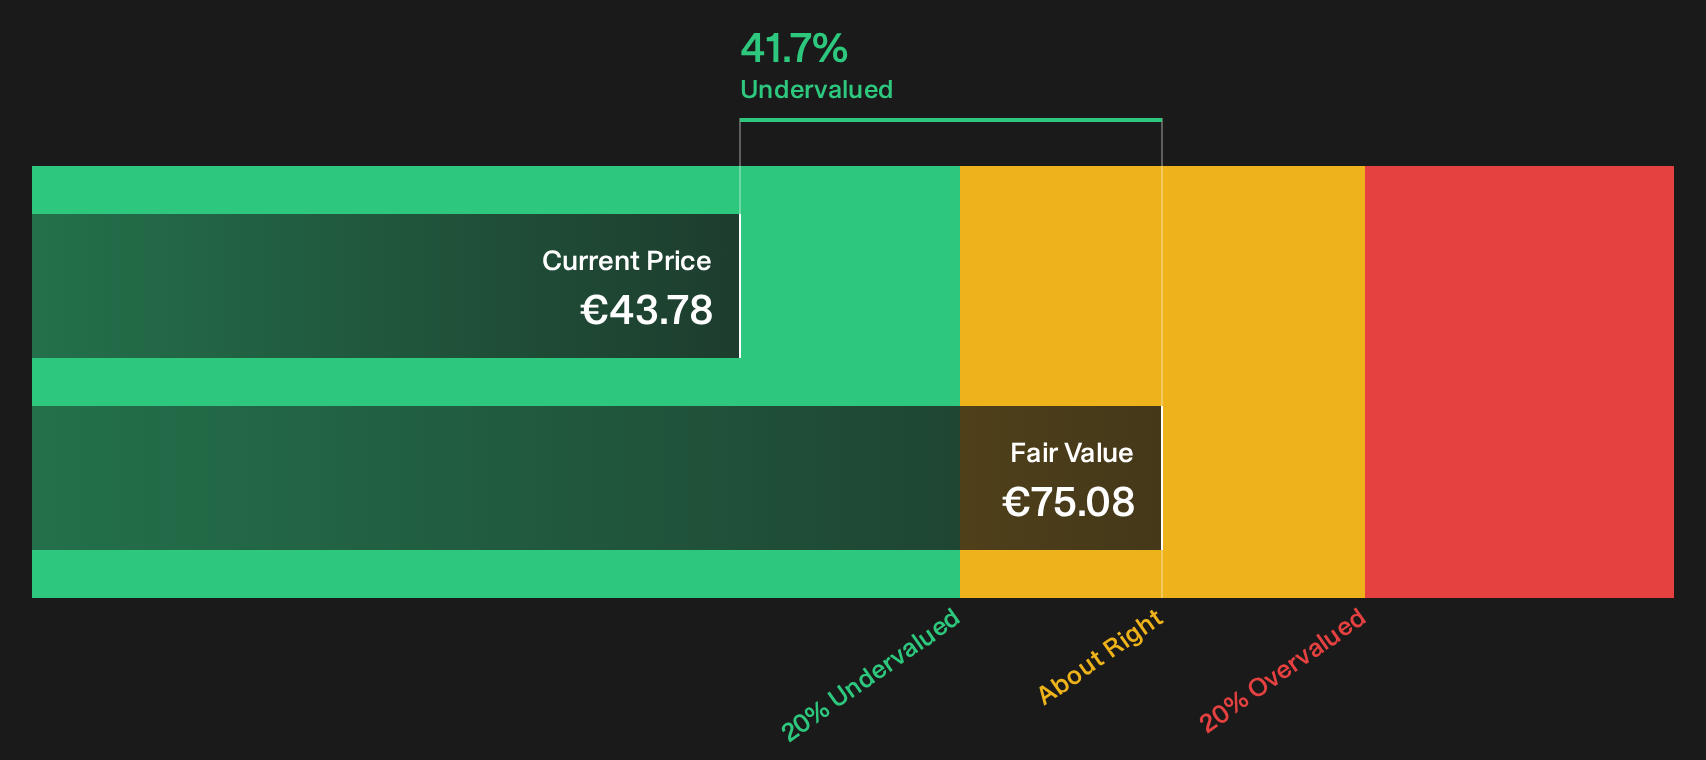
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ERAMET for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on ERAMET so far. Take a closer look at the data, weigh both the risks and potential upside, then decide where you stand with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond ERAMET?
If ERAMET has sharpened your focus on value, do not stop with a single ticker. Broaden your watchlist and pressure test your thesis across other opportunities.
- Target resilient returns by scanning companies with strong payout profiles through our curated 168 dividend fortresses that keep income at the centre of your portfolio.
- Hunt for quality at a discount by reviewing the 191 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect their strengths.
- Prioritise capital preservation by checking a 226 resilient stocks with low risk scores tailored to businesses with more resilient risk scores and steadier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com