


Is HP TV Plus Ad Tech Win Altering The Investment Case For Magnite (MGNI)?
- Magnite, Inc. reported that it became the primary video ad server and programmatic technology provider for HP TV+, supplying HP’s free, ad-supported PC streaming service with its SpringServe ad serving, programmatic activation, and ClearLine Curation tools.
- The HP TV+ agreement opens access for advertisers to consent-based audience segments built from usage insights across 1,200 PC apps and more than 300 behavioral attributes, deepening Magnite’s role in connecting demand to highly targeted, PC-centric streaming inventory.
- We will examine how Magnite's investment narrative is influenced by its HP TV+ role as primary video ad server for consent-based PC audiences.
Scan opportunities beyond Magnite by reviewing hand-picked 90 AI infrastructure stocks that could also benefit as advertisers pursue targeted streaming and AI-driven ad delivery at scale.
Magnite Investment Narrative Recap
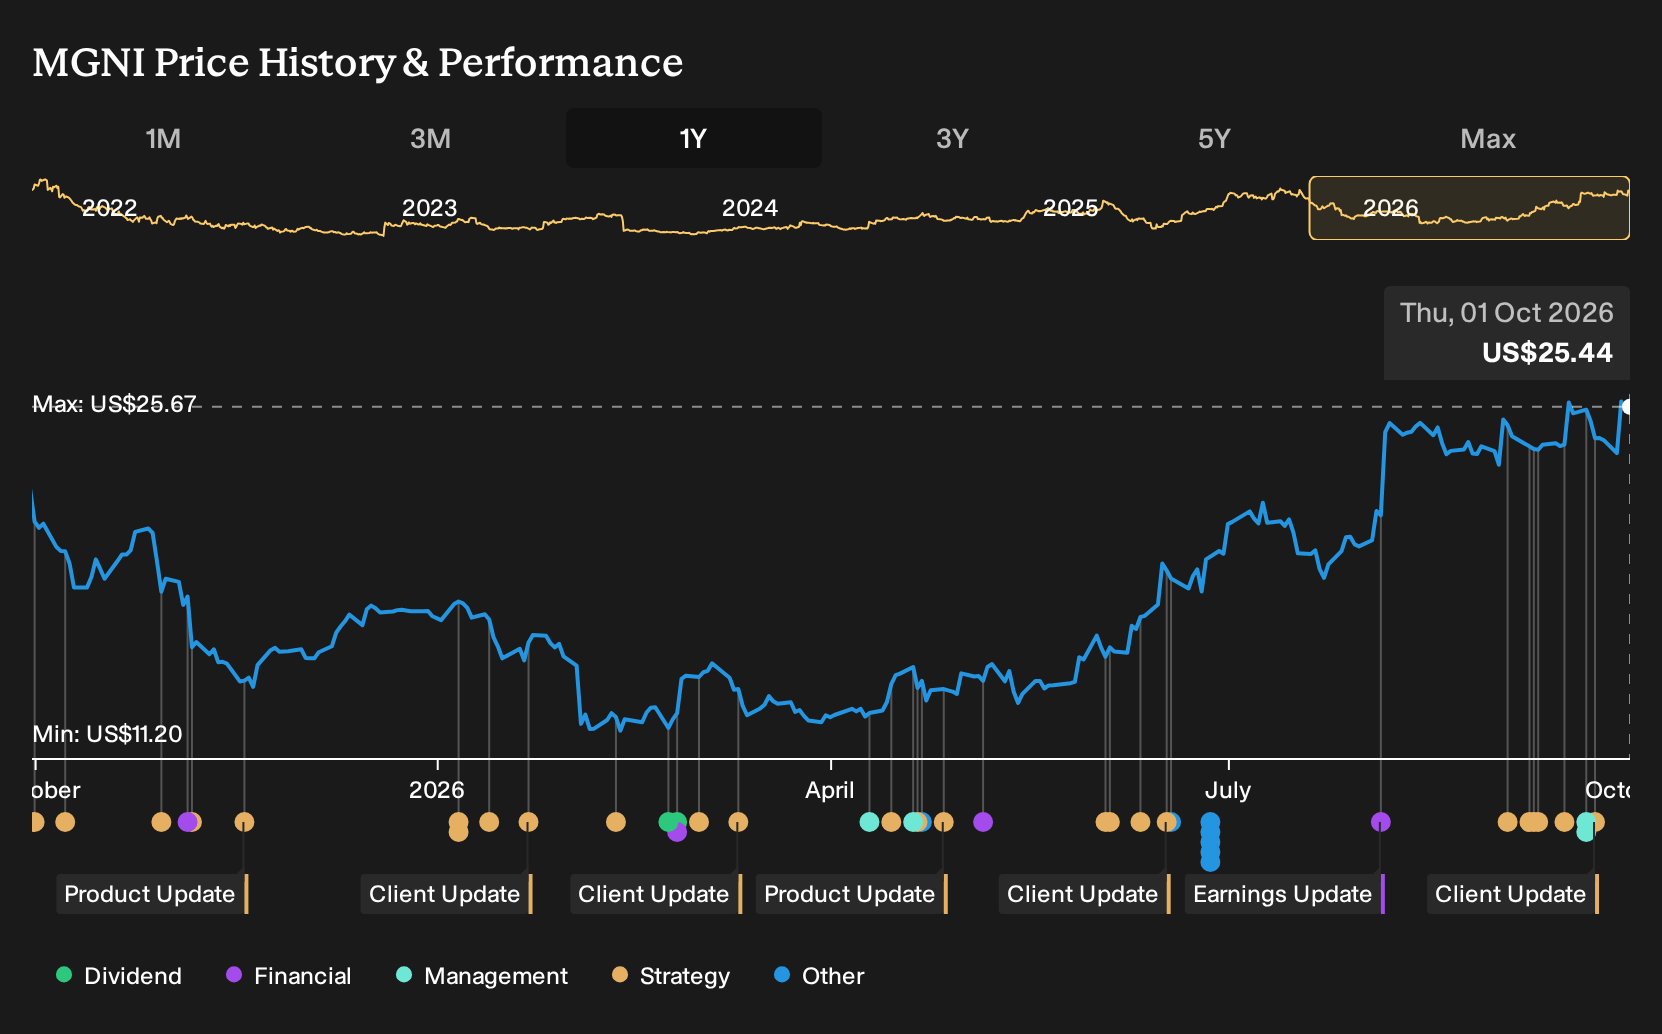
To own Magnite, you need to believe that independent ad tech can keep winning meaningful CTV and digital inventory while staying relevant to buyers that want transparent, programmatic access. The HP TV+ win fits that story but does not, on its own, change the short term picture. The sharper near term swing factor still sits in how ad spend trends and big streaming partners behave.
On risk, the same pressure points remain. Customer concentration with large CTV streamers and agency groups, plus heavy infrastructure and AI investment, can strain margins if spend softens. The HP TV+ agreement helps validate Magnite’s omni channel positioning, yet does not remove the exposure to shifts toward walled gardens or in house tools.
The CFO transition to Brian Gephart is the announcement that matters most for thinking about catalysts around the HP TV+ deal. Magnite is juggling CTV expansion, on prem tech spend, and potential regulatory tailwinds from the Google case, so execution from the finance side will influence how effectively fresh opportunities translate into earnings quality.
Gephart’s background in accounting, capital markets advisory, and prior CFO work suggests familiarity with complex reporting and funding decisions. That can matter if Magnite leans harder into AI driven products like SpringServe and ClearLine while managing CapEx and margin pressure. For an investor, the question becomes how consistently this finance team turns incremental partnerships into disciplined, cash generative growth.
Magnite's current earnings are reported at US$166.9 million, with analyst forecasts pointing to US$926.0 million in revenue and US$136.5 million in earnings by 2029. That profile assumes yearly revenue growth of 7.7% and an earnings decline of about US$30.4 million from earnings today.
Uncover why Magnite's fair value indicates a 17% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For a very different angle on Magnite, focus on the bullish view that AI and SMB adoption could reshape the story. Some of the most optimistic analysts were already modeling US$1.0b of revenue and US$172.5 million of earnings by 2029 before this HP TV+ news. That shows how far opinions can stretch. Use those varied forecasts as a prompt to explore multiple scenarios, then decide which version of the future seems most reasonable to you.
Explore 3 other Magnite fair value estimates, including one that suggests potential upside of as much as 17% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Magnite research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Magnite. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Magnite's overall financial health at a glance.
Looking for more investment ideas beyond Magnite?
Magnite is only one way to express a view on digital advertising and streaming. If you want to broaden your watchlist, the Simply Wall St Screener can surface other stocks that fit different risk and return profiles.
- For investors who want potential upside without ignoring quality, scan a focused group of 19 high quality undiscovered gems that pair solid fundamentals with under followed stories.
- If capital preservation matters as much as growth, filter for stability first by reviewing a 31 resilient stocks with low risk scores that screens for resilient balance sheets and lower risk scores.
- Income focused investors can zero in on reliable cash payouts by checking a curated 7 dividend fortresses built around higher yielding dividend payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com