


Why Trupanion (TRUP) Is Back In The Spotlight
Trupanion (TRUP) is back in focus after recent trading left the stock down about 15% over the past month and roughly 12% lower over the past 3 months, which has sharpened attention on its fundamentals.
Over the past year, Trupanion’s momentum has cooled, with the share price return down sharply year to date and the 1 year total shareholder return falling 45.21%. However, the latest US$23.70 level and a 7 day share price gain of 5.71% hint at a short term rebound in sentiment.
Compare Trupanion’s recent pullback with other potential rebound candidates by scanning our hand picked 28 high quality undervalued stocks that pair balance sheet strength with proven cash generation.
Trupanion now trades about 45% below the average analyst price target, and its share performance has been under pressure. Is that a pricing error or a fair reflection of the risks investors see?
Most Popular Narrative: 31% Undervalued
Against the last close at $23.70, the most followed valuation narrative puts Trupanion’s fair value closer to $34.25, which implies investors are weighing decent growth assumptions against execution and pricing risks.
Improved underwriting discipline, focus on higher lifetime value pets, and optimization of acquisition channels are driving higher-quality book growth and supporting strong free cash flow. This is described as setting up for scalable and more profitable expansion in coming years. The company's increased investment in marketing and pet acquisition, funded by stronger free cash flow and a healthy balance sheet, is expected to accelerate subscriber growth in the back half of 2025 and beyond, supporting faster top-line revenue growth.
See why 6 investors see Trupanion as 31% undervalued.
Result: Fair Value of $34.25 (UNDERVALUED)
Still, that story can crack if Trupanion continues to lean on price increases instead of subscriber growth, or if competition and churn intensify from here.
Find out about the key risks to this Trupanion narrative.
Another View on Trupanion’s Valuation
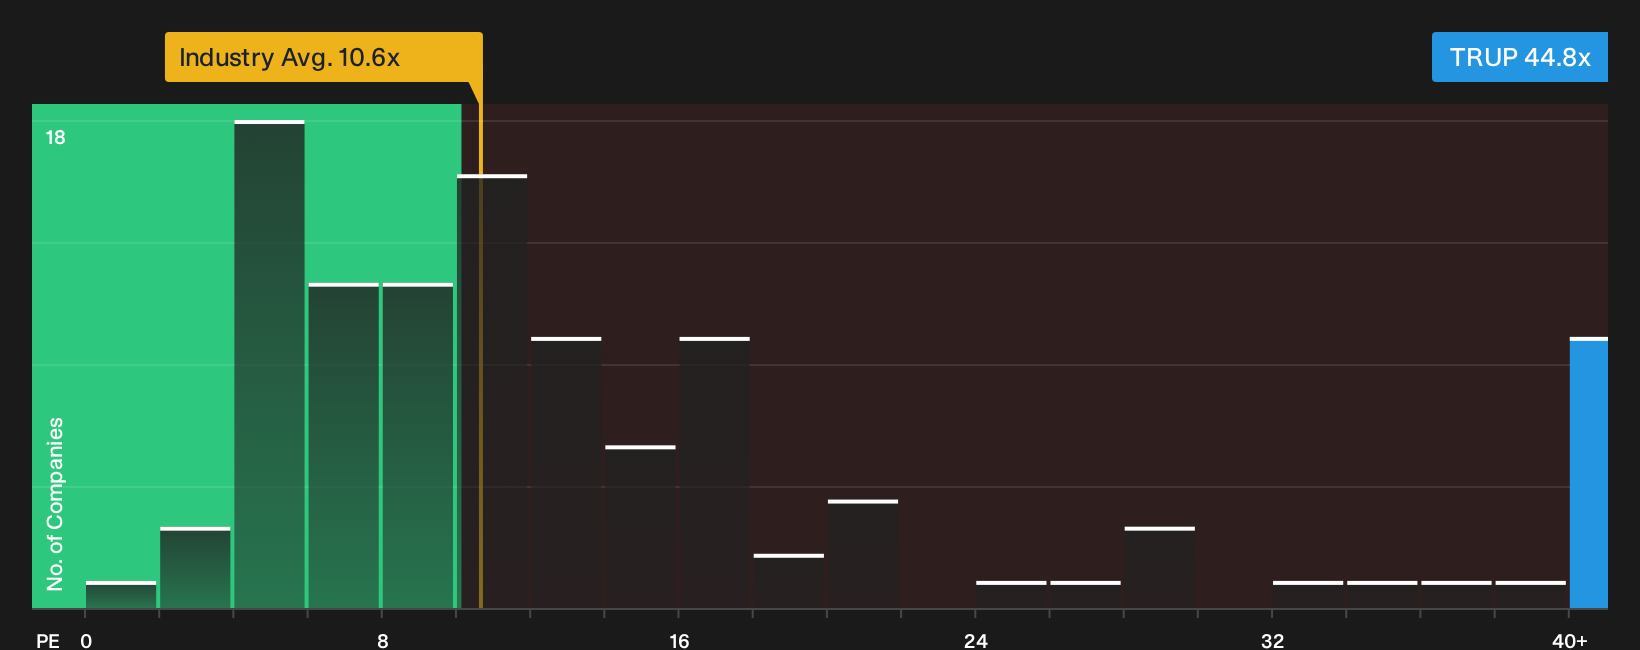
The first narrative argues Trupanion looks undervalued around $23.70 based on fair value of $34.25. A simple earnings multiple tells a very different story. Trupanion trades on a P/E of 44.8x, compared with 10.6x for the US Insurance industry and a fair ratio of 13.5x.
That gap is wide. It suggests investors currently pay more than 4x the sector average for each dollar of earnings, while the fair ratio implies a level closer to one third of the current multiple. This raises the question of whether the stock is priced for execution that leaves little room for disappointment.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Trupanion story so far. If you want to move quickly and judge the upside for yourself, start by reviewing the 3 key rewards.
Looking for more investment ideas beyond Trupanion?
If Trupanion has sharpened your focus, do not stop here. Put a few fresh watchlist candidates on your radar using the Simply Wall St Screener and keep your options open.
- Target potential mispricings by scanning a curated 28 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Protect your downside first by reviewing a 31 resilient stocks with low risk scores that screen strongly on financial resilience and lower overall risk scores.
- Hunt for less crowded opportunities through a 19 high quality undiscovered gems where quality fundamentals have not yet attracted broad market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com