


Berkshire Hathaway And 2 Cash Flow Stocks Worth Watching
Bond markets are sending a clear message. With 10 year and 30 year U.S. Treasury yields sitting at 24 year highs, investors are suddenly paying a lot more attention to cash today instead of distant profits. That shift can punish popular growth stories and leave solid cash generators mispriced. This article highlights three stocks that screen as undervalued on future cash flows, for investors hunting for potential bargains.
The three examples below are only a starting sample, with the full screen surfacing 102 more companies with similarly compelling cash flow stories that are not covered in this article.
If you want to identify and analyze potential high conviction ideas built on discounted cash flow signals, head straight to the Undervalued Stocks Based On Cash Flows screener.
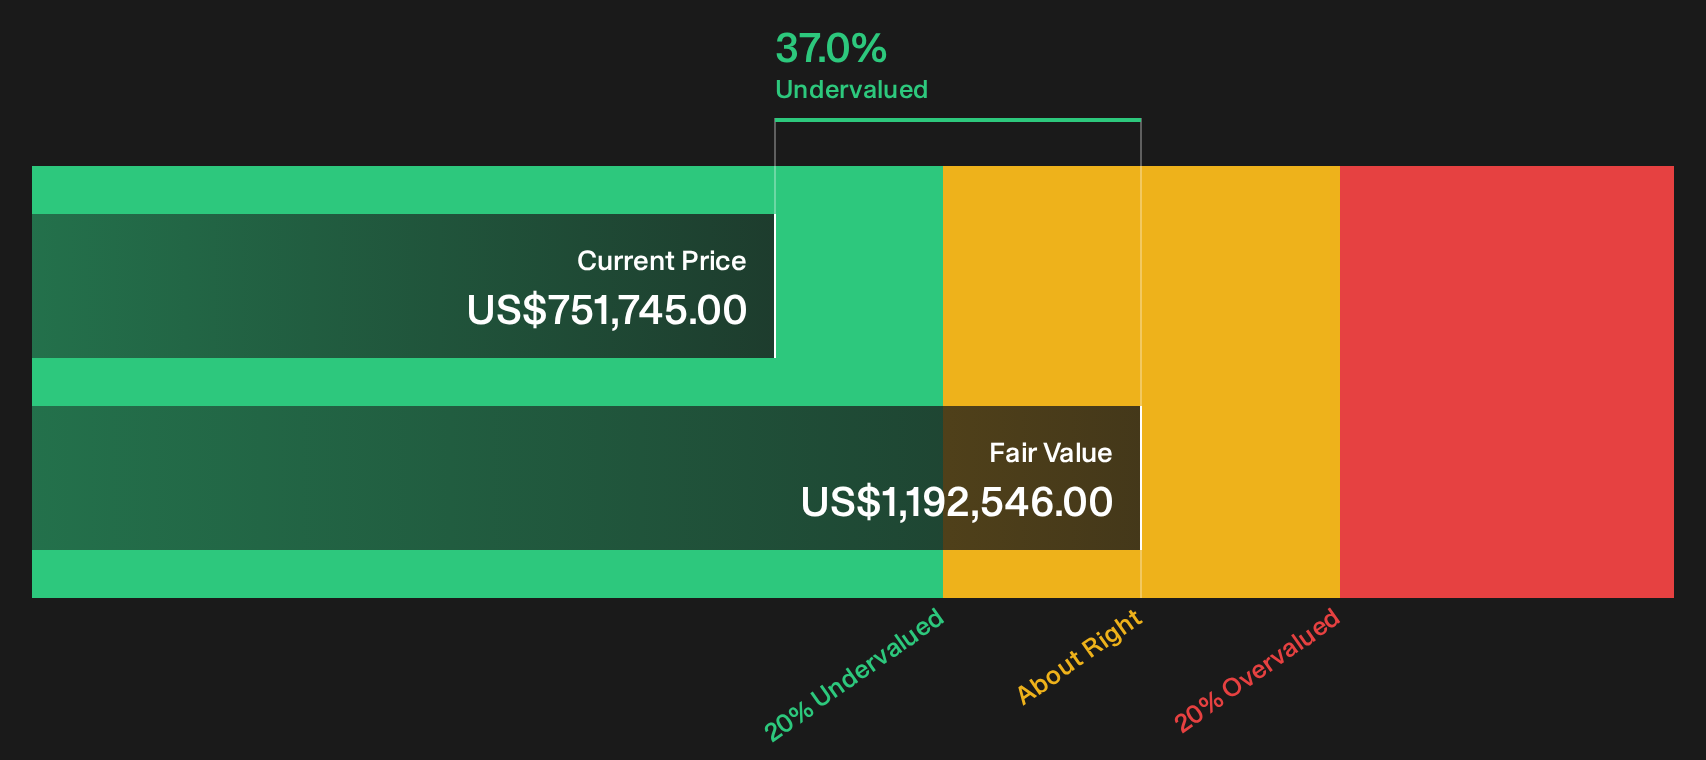
Berkshire Hathaway (BRK.A)
Overview: Berkshire Hathaway is a diversified Omaha based conglomerate spanning insurance, rail, manufacturing, retail and Berkshire Hathaway Energy’s regulated power assets.
Operations: The group generates most of its revenue from manufacturing at US$82.99b, BNSF rail at US$24.64b and Berkshire Hathaway Energy at US$26.92b, with sizable contributions from insurance, retail and distribution arms.
Market Cap: US$1.07t
Berkshire Hathaway matters for this cash flow focused screen because its regulated Berkshire Hathaway Energy arm delivers steady utility earnings that help support a large, flexible capital pool for future deployment.
"Berkshire is still generating massive, predictable free cash flow while sitting on an unprecedented mountain of dry powder. They may continue deploying capital into Treasury bills yielding high interest, while waiting to adjust positions in holdings such as Occidental Petroleum (OXY) and Chubb (CB), or to pursue a large energy infrastructure acquisition."
The real swing factor for Berkshire Hathaway’s cash flow story is how one evolving source of long term demand ultimately feeds through to pricing power.
That pricing power question sits at the center of the full narrative for Berkshire Hathaway, where Berkshire Hathaway’s dry powder, insurance engine and energy ambitions collide in unexpected ways.
Broadcom (AVGO)
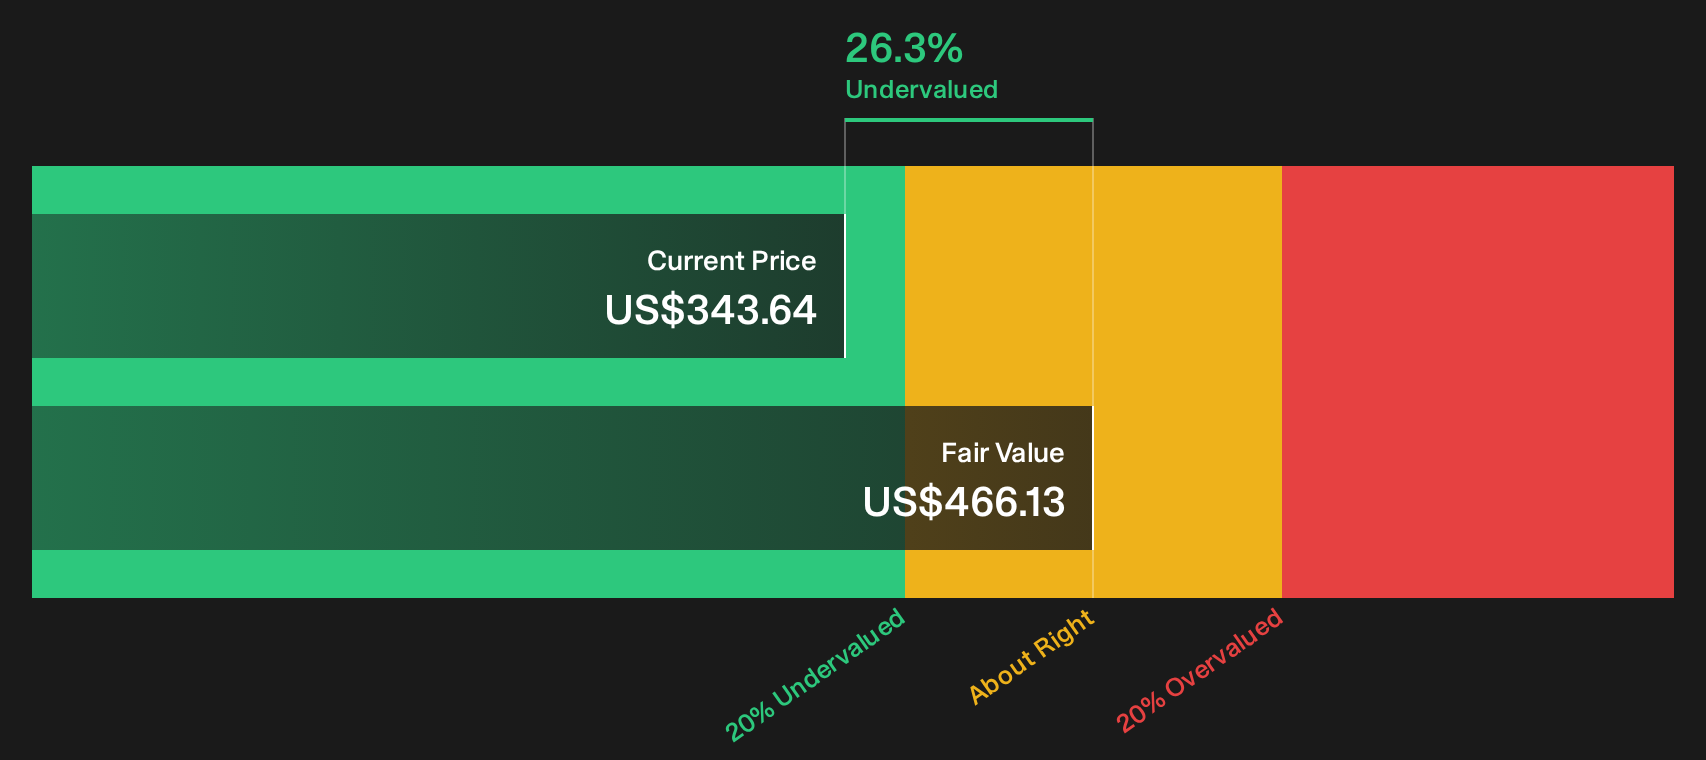
Overview: Broadcom is a digital infrastructure giant that designs semiconductor hardware and private cloud software, including VMware, that underpins recurring, contract-based cash flows.
Operations: Broadcom generates about US$59.44b from Semiconductor Solutions and US$29.67b from Infrastructure Software, giving it two sizeable, diversified revenue pillars.
Market Cap: US$1.68t
Broadcom matters for a cash flow focused screen because its VMware based private cloud and data center software add subscription style revenue on top of its chip business. This gives discounted cash flow models more visibility into future inflows.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
The key question is how one emerging pressure on those software driven cash streams ultimately filters through to pricing power and long term margins.
Those software margin pressures are only the start, with the full narrative for Broadcom mapping how Broadcom’s cash flows could accelerate or stall as contracts renew.
Oracle (ORCL)
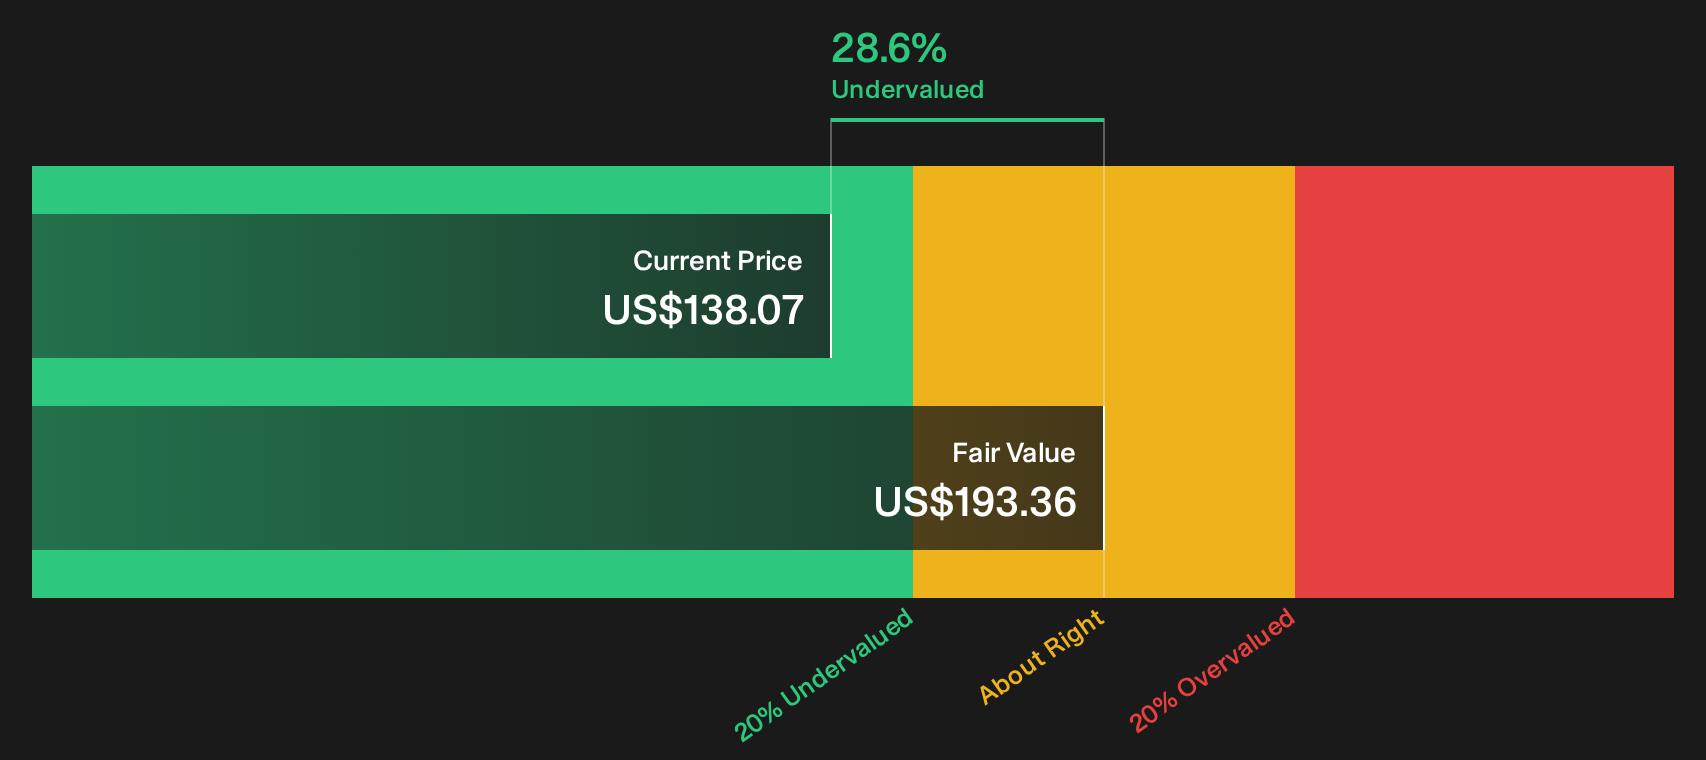
Overview: Oracle provides cloud software and database platforms, including Oracle Cloud applications and Autonomous Database, that support recurring enterprise IT and AI workloads.
Operations: Oracle generates about US$62.78b from cloud and software, US$5.81b from services, and US$3.19b from hardware offerings.
Market Cap: US$416.23b
Oracle matters for this cash flow focused screen because its Oracle Cloud SaaS and database platforms convert long-term software commitments into recurring cash that underpins the discounted cash flow undervaluation case.
"The foundation of Oracle’s AI narrative rests on its Gen2 AI infrastructure and the validation it received from the premier generative AI powerhouse, OpenAI."
The key issue for Oracle is whether one large wave of contracted AI demand ultimately supports cash margins as funding needs reach their peak.
As that funding squeeze builds, read the full narrative for Oracle to see how Oracle’s AI cash engine could accelerate while legacy concerns quietly fade.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. By the time momentum headlines hit, early entries are already flying. Scan these under the radar lists while it matters and get in early.
- Spot companies quietly building strength before a breakout by running the list of solid balance sheet and fundamentals (25 results) and filter for businesses with cash and fundamentals doing the heavy lifting.
- Ride long term income themes by checking the 7 dividend fortresses and focus on payouts that could steady a portfolio when prices start dropping.
- Track accelerating infrastructure demand by scanning the 39 power grid technology and infrastructure stocks and see which operators may benefit if grid upgrades keep gaining momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com