


Learn Why The Bull Case For Bouygues (ENXTPA:EN) Could Change Following AI Call Protection Launch
- Bouygues Telecom recently introduced a network-level nuisance call protection service using Hiya Protect Spam Analytics, offering AI-based real-time screening of unwanted calls for eligible consumer and business customers without requiring a separate app, with pricing from €2 per month per consumer line and €1 per month per business line.
- This move shifts Bouygues Telecom further toward trust-driven, value-added telecom services that rely on AI, call behavior data, and network integration rather than only on traditional connectivity and pricing.
- We will now assess how Bouygues Telecom's investment narrative could be influenced by this AI powered network level call protection push.
Scan for other telecoms and AI driven platforms that could ride the same trust and security trend as Bouygues Telecom by reviewing our curated 90 AI infrastructure stocks.
Bouygues Investment Narrative Recap
Bouygues presents itself as a diversified industrial group that can turn a large order book, a sizeable telecom base and energy services scale into steadier earnings, even when individual segments hit bumps. The new AI call protection fits that story only at the margin in the near term. It supports Bouygues Telecom’s positioning on quality and trust, but it does not change the group’s core earnings drivers today.
The more immediate swing factors still relate to pricing pressure in French telecom, execution at Equans and cyclical swings in construction and Colas. The biggest near term risk is that telecom ARPU remains under pressure in a very aggressive market while group leverage stays high. In that scenario, add on services such as call protection help reputation, yet do not fully offset margin stress.
The disclosure of 388,438,129 shares and 496,449,201 exercisable voting rights as of 30 September 2026 is the most relevant recent announcement alongside Bouygues Telecom’s product launch. It highlights that this is a mature, widely held issuer where capital structure and governance matter just as much as product headlines.
For catalysts, that share and voting base frames how any shift in earnings mix between construction, Equans and Bouygues Telecom affects each holder. It also matters for topics such as future share issuance, dividend decisions and potential balance sheet actions, which relate directly to the high debt flag in the risk profile. The AI trust push in telecom then sits on top of that capital structure, not instead of it.
Bouygues' narrative projects €60.3b revenue and €1.7b earnings by 2029. This scenario is based on 2.3% yearly revenue growth and an earnings increase of about €0.4b from €1.3b today.
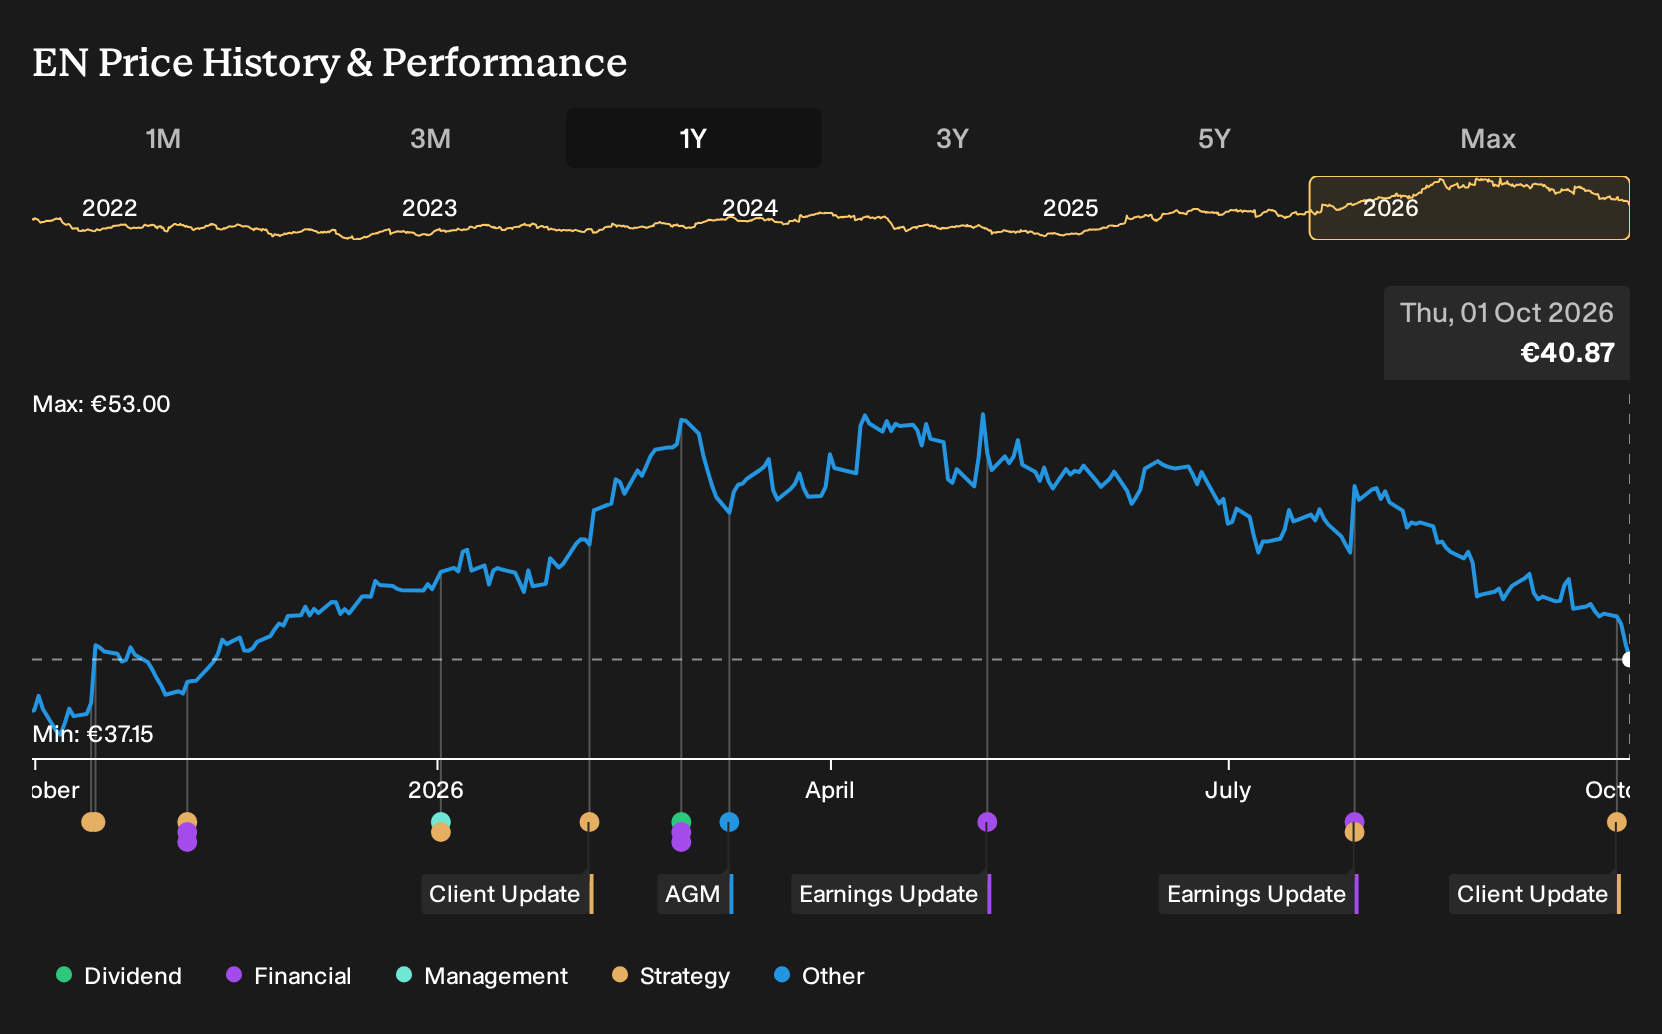
Uncover why Bouygues' fair value indicates a 48% potential upside to its current price before the gap between price and value compresses.
Exploring Other Perspectives
For a different angle, look at how the most cautious analysts focus on telecom pressure. They had Bouygues on a slower track, with revenue only reaching about €58.4b and earnings around €1.4b by 2029. You can ask whether this new AI based call protection nudges that gloomier story toward something more balanced.
Explore another Bouygues fair value estimate, including one that suggests it could be worth just €60.33!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Bouygues research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bouygues. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bouygues' overall financial health at a glance.
Looking for more Bouygues-style investment ideas?
If the Bouygues story has you thinking about where else dependable cash flows, solid balance sheets and differentiated services might line up, the Simply Wall St Screener can help surface other stocks that fit your checklist without spending hours trawling through data.
- If capital preservation comes first for you, start with a set of companies that score well on stability and resilience by reviewing our 226 resilient stocks with low risk scores.
- Income focused investors who care about consistency rather than just headline yield can scan a curated group of higher yielding payers through the 168 dividend fortresses.
- Those hunting for under the radar quality plays with robust fundamentals can work through the 616 high quality undiscovered gems and build a broader watchlist beyond Bouygues.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com