


Vicor (VICR) Stock Looks Stretched On Its 7x One Year Run
Vicor has turned into a headline stock after a rapid share price climb, which puts fresh focus on whether its current valuation stacks up against the earnings the business is actually producing. With such a fast move, the key issue for you is whether the market price reflects profit power or simply enthusiasm around the story.
- Over the past year, the stock has delivered a very large return of roughly 7x, which raises the question of how much of that move earnings can reasonably support.
- The recent contract win that sent Vicor shares sharply higher may support expectations for more durable revenue and potentially steadier profitability, which directly feeds into what investors are willing to pay for each dollar of earnings.
- Your read on Vicor is one view; the desks covering it have another. See what analysts think Vicor's shares could be worth.
The stock's next move may depend on whether Vicor's current earnings profile can justify the price investors are now paying for each share.
If you want context for Vicor's rapid move on earnings expectations, it can help to compare it with other companies in similar situations using the 28 high quality undervalued stocks
Does Vicor Look Pricey on Earnings?
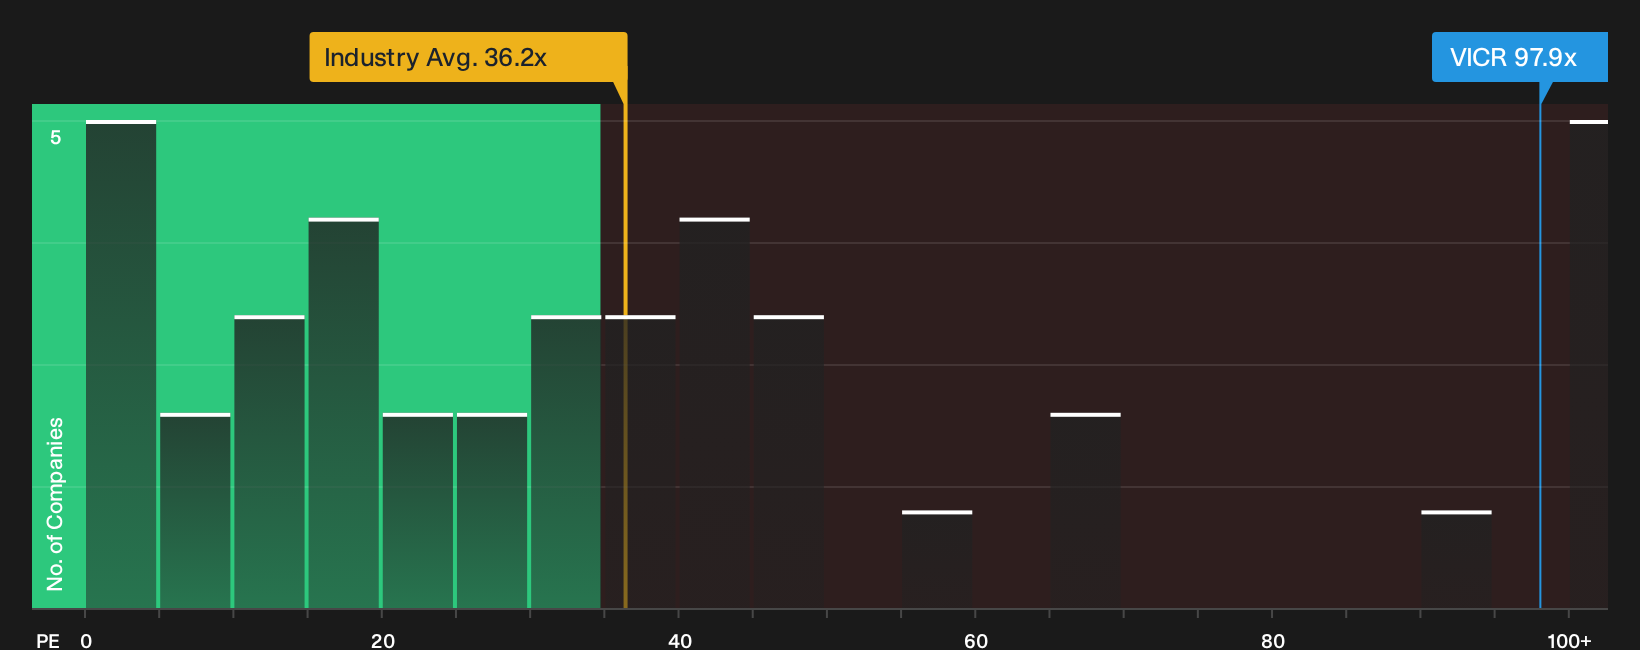
For Vicor, the P/E ratio is the cleanest way to see how much investors are paying for each dollar of profit. The stock currently trades on a P/E of 97.9x, which is far above both the Electrical industry average of 36.2x and the peer group average of 29.2x. That kind of gap indicates that buyers are assigning a heavy premium to the earnings stream.
The Fair Ratio model, which blends factors like growth assumptions, profitability profile, risk and size, points to a lower P/E than where Vicor is now, so the market price screens as overvalued on this framework. Because the recent contract win has lifted sentiment and expectations, the multiple now incorporates a lot of optimism compared with typical valuations in the sector. If you are considering Vicor at this level, the key question is whether the current earnings and contract visibility justify paying this much more for each dollar of profit than the model suggests. Explore the numbers behind Vicor's P/E valuation.
The Vicor Narrative: What Would Justify Today's Price?
Vicor's high P/E raises a simple question for you as an investor: which future path could make that valuation look reasonable or stretched? Simply Wall St Narratives on the Community page spell out those different paths by tying specific assumptions about growth, margins and earnings to the current share price. Each scenario links a fair value to a particular mix of potential catalysts and risks so you can watch over time which storyline appears to be unfolding.
One of the top community narratives on Vicor: 20% undervalued
"Advanced power delivery products and automotive modules position Vicor to benefit from AI computing, electric vehicle trends, and expanded customer engagements in critical markets..."
Discover why this Narrative puts Vicor at 20% undervalued.
One last Vicor check that sits outside the current price tag
All the multiples and peer comparisons only tell you what Vicor looks like today. Another lens comes from where professional forecasts see the business a few years from now, and how that squares with this valuation. Explore where analysts expect Vicor to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com