


Did Reford 2 Expansion Just Shift Cardinal Energy Stock's Investment Narrative?
- Cardinal Energy expanded its Reford 2 thermal project in a supportive crude-price backdrop, while continuing to fund its regular monthly dividend program. This reinforces attention on operational execution and capital allocation discipline.
- The combination of long-life thermal development at Reford 2 and an ongoing cash return policy gives investors a clearer view of how Cardinal Energy is balancing future production with near-term income.
- This article examines how Cardinal Energy's investment narrative is shaped by the Reford 2 expansion and its maintained monthly dividend.
Scan beyond Cardinal Energy and line up other producers offering a similar mix of income and project growth with the curated 1 dividend fortresses.
What Is Cardinal Energy's Investment Narrative?
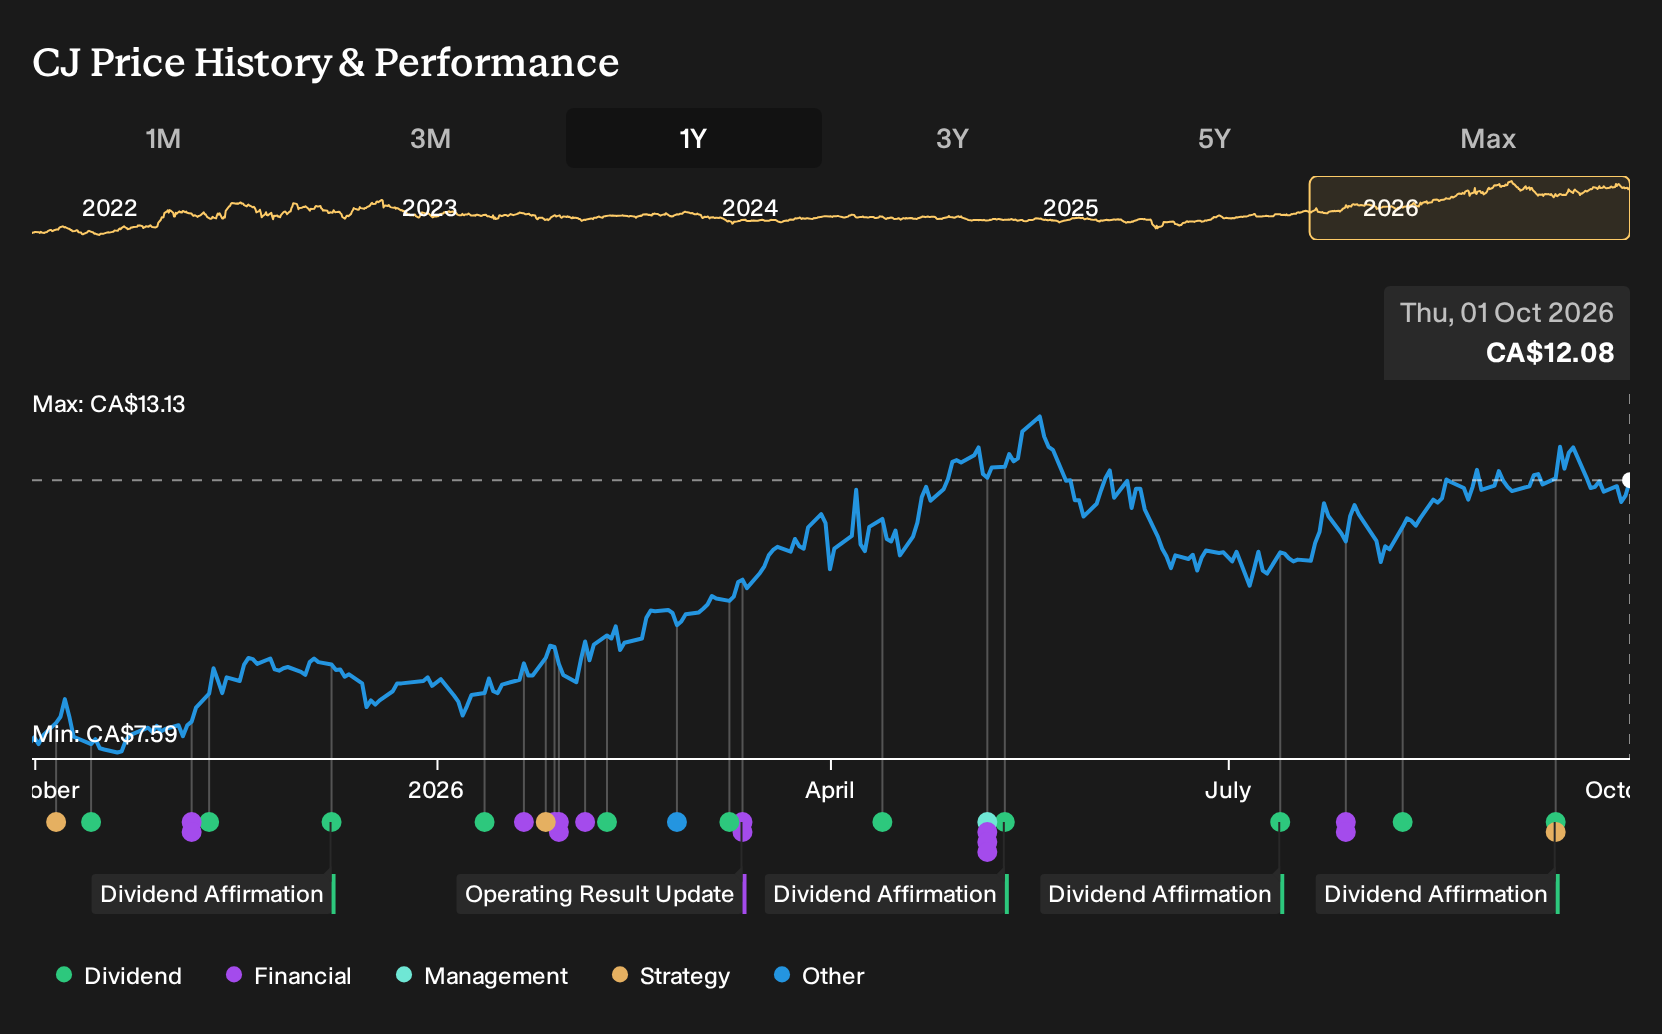
To own Cardinal Energy, you need to be comfortable with a simple idea. The entire pitch leans on long life Canadian oil and gas assets, relatively visible thermal volumes from projects like Reford 2, and a willingness to return cash through a monthly dividend even while funding development. The recent share move after the Reford 2 expansion news speaks to that story. The market is reacting to the prospect of more stable production, but also testing whether management can turn capital intensive projects into better earnings and cash flow than the last 12 months have shown.
Short term, the key swing factors remain execution on Reford 2, crude pricing, and how tightly Cardinal Energy manages spending while carrying a dividend that is not well covered by earnings or free cash flow. Net profit margins sit at 11.5%, below last year, and past results include large one off items, so cleaner performance will matter a lot. A P/E of 33.7x, higher than peers, also means investors are already paying up for that improvement, which raises the cost of any operational misstep.
Yet before treating this income plus growth pitch as a settled story, there is a lingering issue around...
There's only one way to know the right time to buy, sell or hold Cardinal Energy. Head to Simply Wall St's company report for the latest analysis of Cardinal Energy's Fair Value.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly C$13.82 to C$28.66, so retail opinions on Cardinal Energy already pull in very different directions. Those views were formed before the Reford 2 expansion news and the early October price reaction, so treat them as a baseline and explore several competing angles.
Explore 2 other Cardinal Energy fair value estimates, including one that suggests it could be worth just CA$13.82.
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Cardinal Energy research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cardinal Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cardinal Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cardinal Energy?
If the Cardinal Energy story has sharpened your focus on what you want from a portfolio, use that clarity to widen your opportunity set with targeted screeners that line up with your risk profile and income needs.
- If capital preservation is high on your list, start with a group of companies that score well on stability and resilience through the 9 resilient stocks with low risk scores.
- If you are hunting for value backed by strong fundamentals, scan for companies that combine quality balance sheets with attractive pricing using the 5 high quality undervalued stocks.
- If you prefer to cast a wider net and spot potential future leaders early, broaden your watchlist with the 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com