


Celsius (CELH) Stock Looks Overvalued Even After a 53% Fall
Celsius Holdings has seen its share price fall sharply over the past year, which puts a fresh spotlight on whether the current valuation still lines up with what the business is earning. For investors watching the pullback, the key issue is how the stock price now compares with the company’s profit power.
- The share price has fallen 53.5% over the past year, which raises a direct question about how much of Celsius Holdings’ earnings strength is already being discounted.
- The business model relies heavily on converting branded beverage sales into sustainable profitability. As a result, any shift in costs, pricing power, or cash generation can quickly change how its earnings support the current share price.
- The analysts covering Celsius Holdings have run their own numbers. See what analysts think Celsius Holdings's shares could be worth.
The stock’s next move may depend on whether today’s valuation can be explained by the earnings that Celsius Holdings is currently producing and is expected to generate over time.
For context on whether Celsius Holdings’ recent share slide lines up with its earnings profile, it can help to compare it with other businesses that screen on 28 high quality undervalued stocks.
Does Celsius Holdings Look Pricey on Earnings?
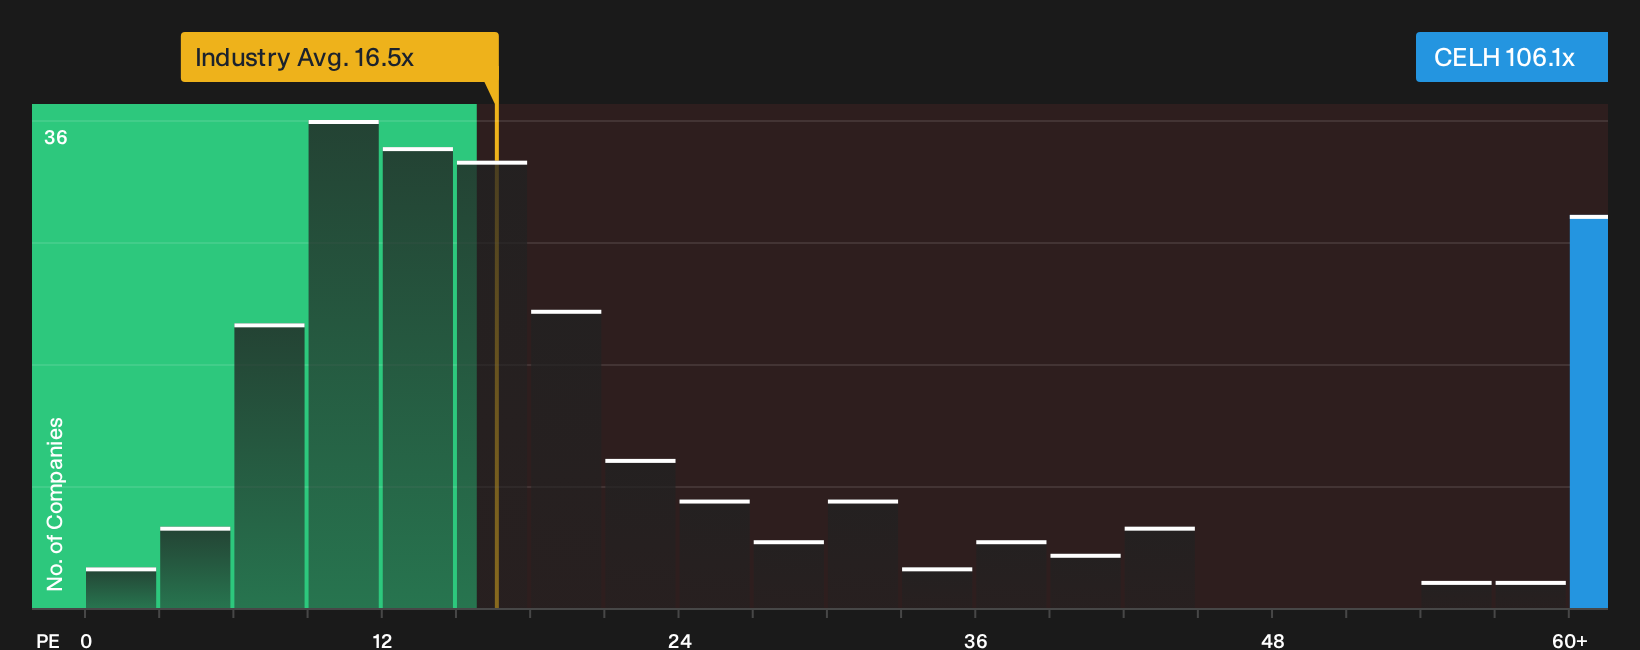
The P/E ratio is a straightforward way to see how much investors are paying for each dollar of Celsius Holdings earnings. On this basis, the stock trades at about 106.1x, which is far above the Beverage industry average of 16.5x and also well ahead of the broader peer group around 32.8x.
A more tailored fair-value model, which adjusts for Celsius Holdings margins, growth profile, size, and risk, points to a lower P/E level than where the shares change hands today. The gap is wide enough that the framework is effectively flagging the stock as overvalued on earnings, and the model heavily penalises the risk profile rather than offering a precise target. For anyone considering the recent pullback, the current multiple still prices Celsius Holdings at a very rich earnings premium on this measure. Explore the numbers behind Celsius Holdings's P/E valuation.
The Celsius Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Celsius Holdings pick up where the valuation puzzle leaves off and explain which combinations of future growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. Each scenario on the Community page links a fair-value view to a specific storyline about Celsius Holdings' possible catalysts and risks, allowing you to track over time which interpretation appears to be unfolding.
Community views on Celsius Holdings are split between those who see a misread inventory shock and those who think execution risk now dominates.
Bull case: 51% undervalued
"The ones who understood what actually happened in 2024 and why the crash was a channel inventory problem, not a brand problem…"
Discover why this Narrative puts Celsius Holdings at 51% undervalued.
Bear case: 5% overvalued
"Although Celsius Holdings highlights resilient retail scanner trends for the Celsius brand, the roughly 12% decline in Q2 2026 net sales…"
Explore why this Narrative puts Celsius Holdings at 5% overvalued.
An unresolved question around Celsius Holdings that valuation alone cannot answer
Celsius Holdings looks very different once you factor in the issues our broader checks have picked up, and those potential pressure points deserve a closer look before you rely only on the numbers. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com