


Ormat Technologies (ORA) Stock May Be Expensive After Its 38% Run
Ormat Technologies has seen its share price retreat in recent months, which puts fresh attention on whether the current valuation still lines up with what the business earns. With new geothermal projects progressing and policy support in play, the question is how much of that is already reflected in what you are paying for its earnings today.
- Over the past 3 years, Ormat Technologies has returned about 38.1%, which puts pressure on investors to ask if the earnings profile has kept pace with that gain.
- The company’s selection for up to approximately US$35 million in U.S. Department of Energy funding and its role in Sage Geosystems’ next commercial-scale Enhanced Geothermal Systems project may support expectations for longer term revenue and cash flow from geothermal assets, along with higher upfront capital needs.
- There is a second opinion on Ormat Technologies worth weighing. See what analysts think Ormat Technologies's shares could be worth.
The issue now is whether Ormat Technologies’ current share price is justified by its earnings when set against this mix of past returns and project news.
If you are weighing whether Ormat Technologies’ recent pullback leaves enough earnings power on the table, it can help to compare that same question across 28 high quality undervalued stocks.
Has Ormat Technologies Run Too Far on Earnings?
P/E fits Ormat Technologies because earnings still sit at the center of how investors frame a regulated, capital heavy geothermal operator.
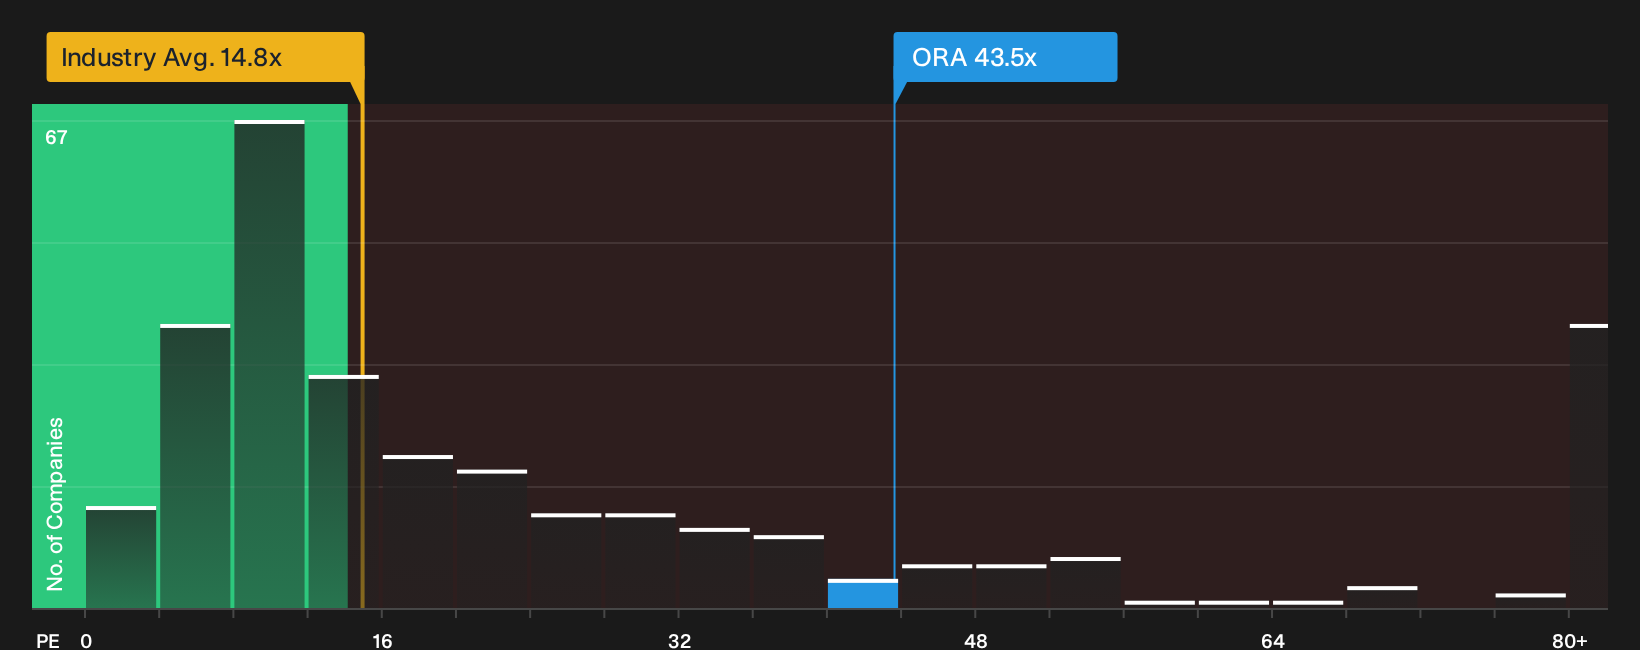
Right now the stock trades on a P/E of about 43.5x, well above the Renewable Energy sector average of roughly 14.8x and also above peers around 30.6x. That points to investors paying a clear premium for each dollar of profit. A tailored fair P/E that blends Ormat Technologies’ growth profile, margins, size and risk sits below the current multiple, which signals the shares screening as overvalued on this yardstick. Because the P/E is so far above broader sector levels, it leaves less margin for disappointment if earnings or project economics do not match what is implied.
Because the US$35 million Department of Energy funding and the Sage Geosystems project highlight future geothermal potential, the rich P/E looks like a bet that these projects will ultimately support stronger earnings than the current financials show. For anyone considering the stock today, the key question is whether that premium P/E still leaves enough upside if execution or timing proves slower than the market currently assumes. Explore the numbers behind Ormat Technologies's P/E valuation.
The Ormat Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ormat Technologies pick up where the P/E puzzle leaves off by spelling out which assumptions on future growth, profitability and earnings would need to hold for the shares to be worth meaningfully more or less than today’s price, and they sit on Simply Wall St’s Community page. Each one treats fair value as a thesis about Ormat Technologies' business you can track over time, not just a single snapshot.
A written, number driven view on Ormat Technologies now gives you a clear way to track whether the US$35 million Department of Energy funding and Sage Geosystems’ commercial scale project at Blue Mountain translate into the kind of earnings and cash flow profile the current P/E is implying. Putting those expectations into a concrete narrative makes it easier to revisit the thesis as drilling, testing and project timelines move ahead over the coming years.
Share your own Narrative for Ormat Technologies and set out the assumptions behind your valuation.
One more check for Ormat Technologies that sits beyond the share price
Before you stop at the P/E and project pipeline, it is worth asking who is steering Ormat Technologies and how their pay lines up with your interests as a shareholder. See who runs Ormat Technologies and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com