


Exploring October 2026's Undervalued Small Caps With Insider Action
Over the last 7 days, the United States market has experienced a slight decline of 1.0%, yet it remains up by 11% over the past year with an optimistic forecast of a 17% annual earnings growth. In this context, identifying small-cap stocks with insider activity can be crucial for investors seeking opportunities that may offer potential value amidst these dynamic market conditions.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Surgery Partners | NA | 0.5x | 29.80% | ★★★★★★ |
| Regional Management | 6.1x | 0.4x | 37.36% | ★★★★★☆ |
| Financial Institutions | 9.6x | 3.2x | 23.95% | ★★★★★☆ |
| Cardinal Infrastructure Group | NA | 0.9x | 38.40% | ★★★★★☆ |
| Enovis | NA | 0.5x | 44.74% | ★★★★★☆ |
| Bank of the James Financial Group | 10.8x | 2.4x | 27.43% | ★★★★☆☆ |
| German American Bancorp | 12.9x | 4.8x | 28.86% | ★★★☆☆☆ |
| Bank of Marin Bancorp | NA | 7.2x | 32.62% | ★★★☆☆☆ |
| Franklin Financial Services | 11.4x | 3.1x | -38.48% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 10.19% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
German American Bancorp (GABC)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: German American Bancorp operates as a financial holding company providing core banking and wealth management services, with a market capitalization of approximately $1.06 billion.
Operations: Core Banking is the primary revenue stream, contributing significantly to the overall income. Wealth Management Services and Unallocated Other Revenues also add to the revenue mix. The net income margin has shown variability, with a recent figure of 36.56%. Operating expenses are primarily driven by General & Administrative Expenses, which stood at $158.57 million in Q2 2026.
PE: 12.9x
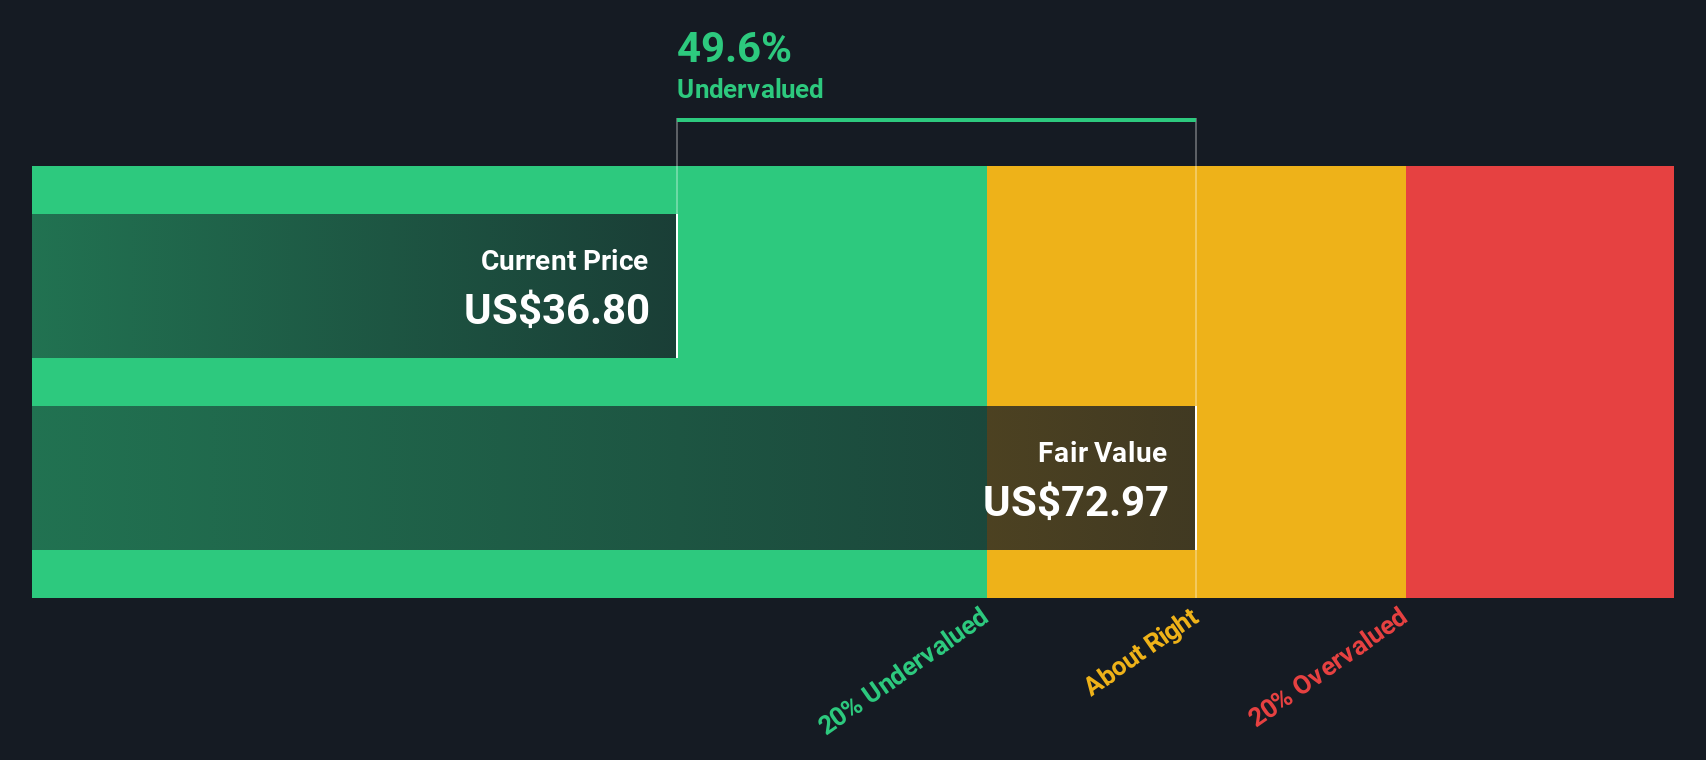
German American Bancorp shows potential as a smaller U.S. company with its earnings forecasted to grow 7.01% annually. Recent financials highlight a rise in net interest income to US$81 million from US$73 million year-over-year for the second quarter, and net income increased to US$38 million from US$31 million. Despite no recent share repurchases, insider confidence is evident through consistent dividend payouts, such as the declared quarterly cash dividend of $0.31 per share payable in August 2026.
Hawthorn Bancshares (HWBK)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Hawthorn Bancshares operates as a financial holding company primarily through its subsidiary, Hawthorn Bank, and offers wealth management services with a market capitalization of approximately $0.14 billion.
Operations: Hawthorn Bancshares generates most of its revenue from Hawthorn Bank, with a smaller contribution from Wealth Management. The company has consistently achieved a gross profit margin of 100%, indicating that all reported revenue is retained as gross profit. Operating expenses are primarily composed of general and administrative costs, followed by sales and marketing expenses. Net income margins have shown variability over time, reaching as high as 30.30% in recent periods but also experiencing fluctuations in earlier years.
PE: 10.4x
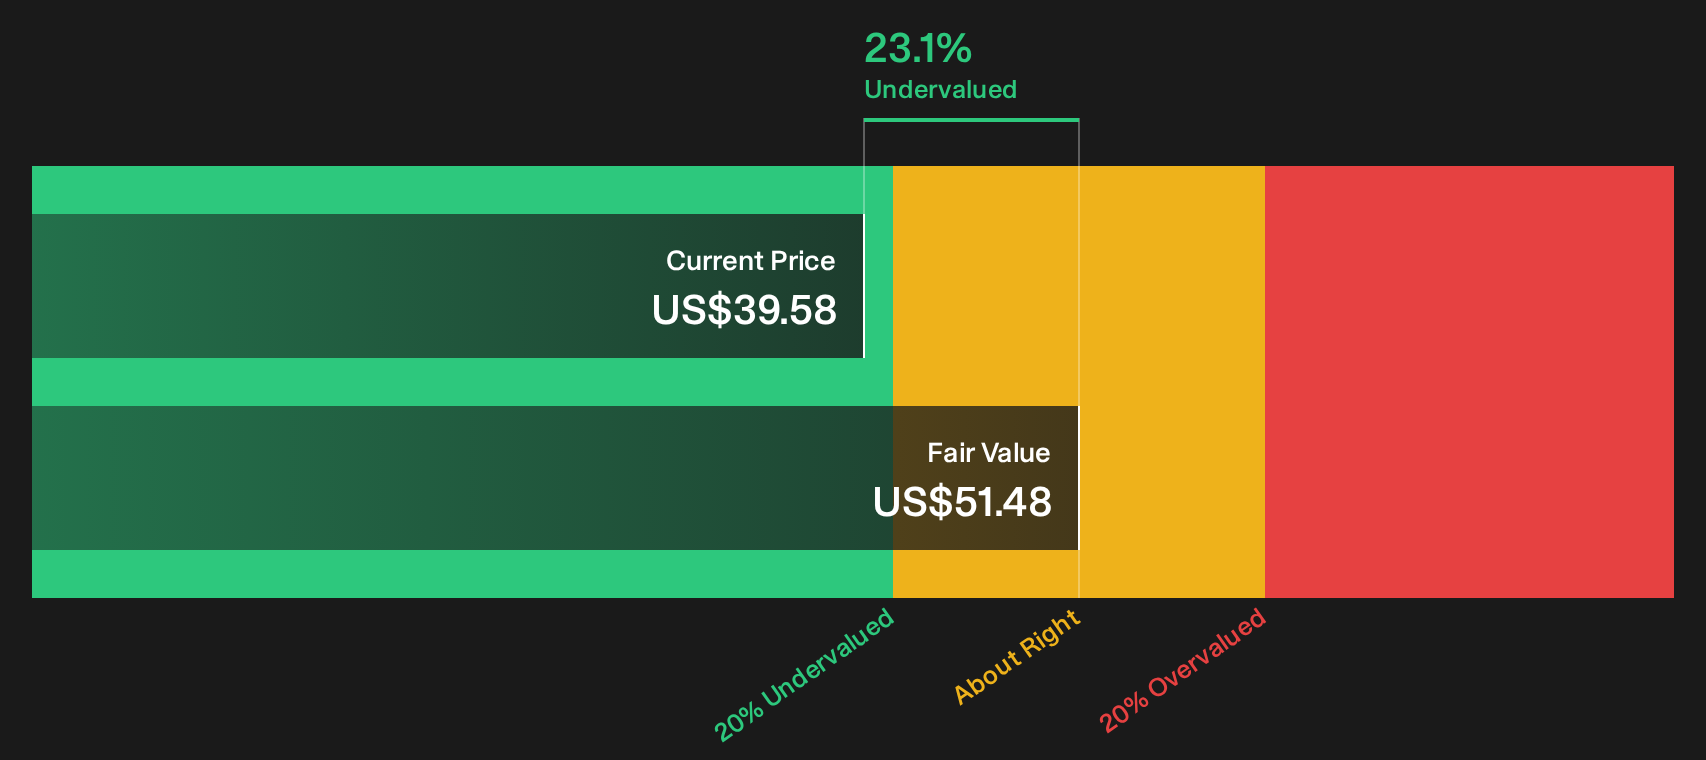
Hawthorn Bancshares, a smaller player in the U.S. financial sector, has shown resilience despite a 1% annual earnings decline over the past five years. Recently, they reported Q2 net income of US$7.33 million, up from US$6.1 million last year, indicating potential for recovery amidst challenges like increased loan charge-offs reaching US$138,000 this quarter. Insider confidence is evident with recent share purchases by executives and board members during 2026. The company continues to distribute dividends consistently at US$0.21 per share as of October 2026.
- Unlock comprehensive insights into our analysis of Hawthorn Bancshares stock in this valuation report.
Assess Hawthorn Bancshares' past performance with our detailed historical performance reports.
Under Armour (UAA)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Under Armour is a global sports apparel and footwear company known for its innovative performance products, with operations spanning across North America, EMEA, Asia-Pacific, and Latin America.
Operations: Under Armour's revenue is primarily driven by its North America segment, contributing significantly alongside EMEA and Asia-Pacific regions. The company's gross profit margin has shown fluctuations, reaching 50.34% in late 2021 before declining to 45.62% by mid-2026. Operating expenses are largely comprised of general and administrative costs, with sales and marketing also representing a significant portion.
PE: -4.0x
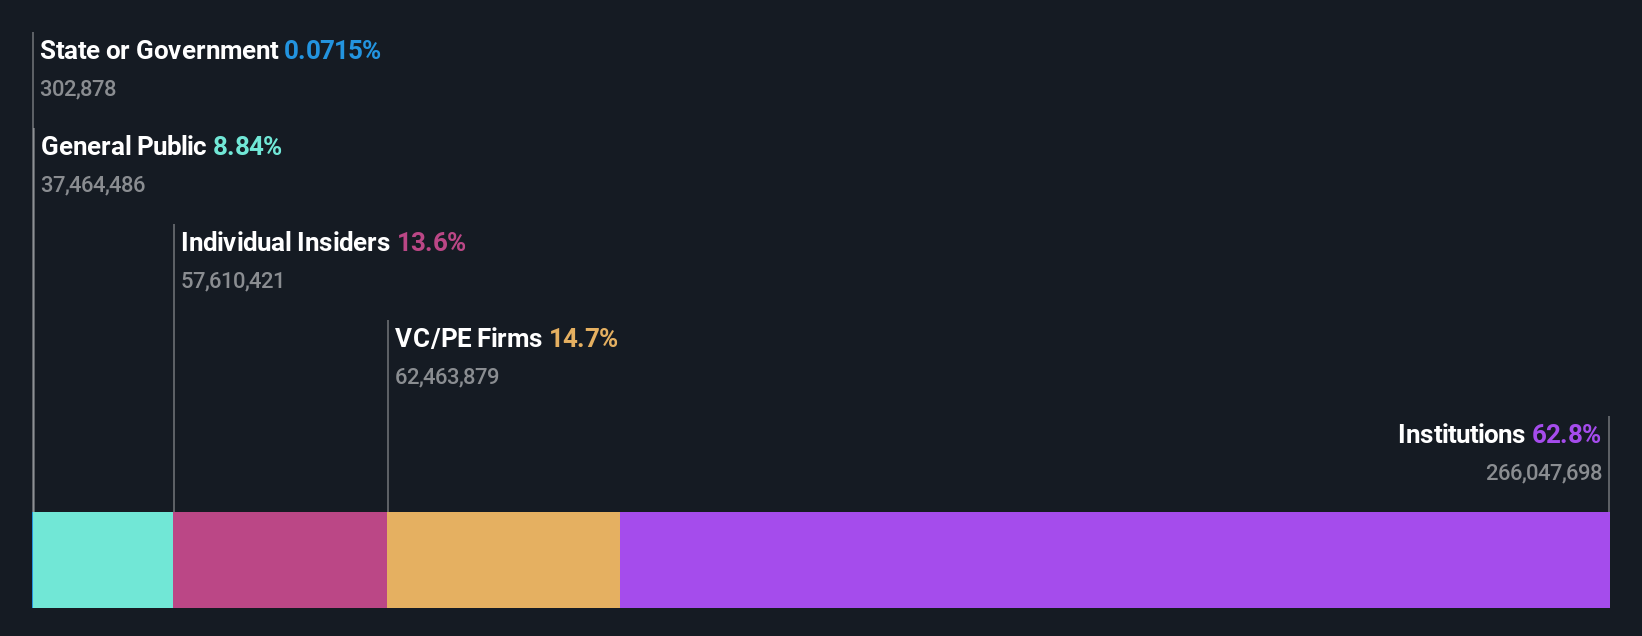
Under Armour, a smaller player in the athletic apparel industry, has recently shown signs of financial improvement. For Q1 ending June 2026, they reported a net income of US$0.545 million compared to a loss the previous year, despite slightly lower sales at US$1.10 billion. However, their revised guidance for 2027 indicates challenges ahead with expected revenue declines due to softer demand in North America and Asia-Pacific. The company emphasizes long-term brand health through disciplined market management and full-price selling strategies.
- Take a closer look at Under Armour's potential here in our valuation report.
Explore historical data to track Under Armour's performance over time in our Past section.
Summing It All Up
- Reveal the 65 hidden gems among our Undervalued US Small Caps With Insider Buying screener with a single click here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com