


Repsol (BME:REP) Looks Fully Valued As Diesel Supply Risks Shift The Story
Repsol (BME:REP) is back in focus as diesel moves into the political spotlight, with potential US export limits and Strait of Hormuz supply risks reshaping the outlook for European refiners and distributors.
The recent pullback, with a 1-day share price return of 0.40% lower and a 7-day share price return down 5.49% to €29.81, comes after a sharp 30-day share price gain of 6.50% and a 90-day share price move of 33.50%. The 1-year total shareholder return of 107.68% and 5-year total shareholder return of 230.41% indicate that Repsol has been in a strong upswing that investors are now reassessing as diesel policy risks and the company’s renewable build-out reshape expectations.
Scan how Repsol compares with other fuel and energy players reacting to diesel policy shocks by reviewing the hand-picked 39 power grid technology and infrastructure stocks in the sector.
Repsol now appears to be a solid multi-energy business following a powerful run in its share price. The key question is whether that strength is already fully reflected in today’s valuation.
Most Popular Narrative: 4% Overvalued
Repsol’s most followed valuation storyline puts fair value at €28.67, slightly below the latest close of €29.81. This tilts the balance toward a modestly rich price tag while still hinging on how its energy transition plans play out.
Repsol's continued expansion and asset rotations in renewable energy (notably wind, solar, and renewable fuels) are poised to diversify revenue streams, lessen earnings volatility, and capture higher-margin growth in low-carbon markets. This is strengthened by increasing policy support for renewables and rising demand in both the U.S. and Spain, directly impacting future revenue and net margins.
See why 78 investors see Repsol as 4% overvalued.
Result: Fair Value of €28.67 (OVERVALUED)
Still, higher regulatory costs on hydrocarbons and heavy capital spending needs could pressure Repsol’s cash generation and weaken support for the current valuation story.
Find out about the key risks to this Repsol narrative.
Another View on Repsol’s Value
The SWS DCF model paints a very different picture for Repsol. On that framework, the share price of €29.81 sits well below an estimated future cash flow value of €49.01, which points to Repsol trading at a sizeable discount instead of looking 4% overvalued.
The gap between the analyst fair value of €28.67 and the DCF output raises a simple question for you: Are analyst forecasts too cautious on long term cash generation, or is the model assuming more than Repsol can realistically deliver?
Look into how the SWS DCF model arrives at its fair value.
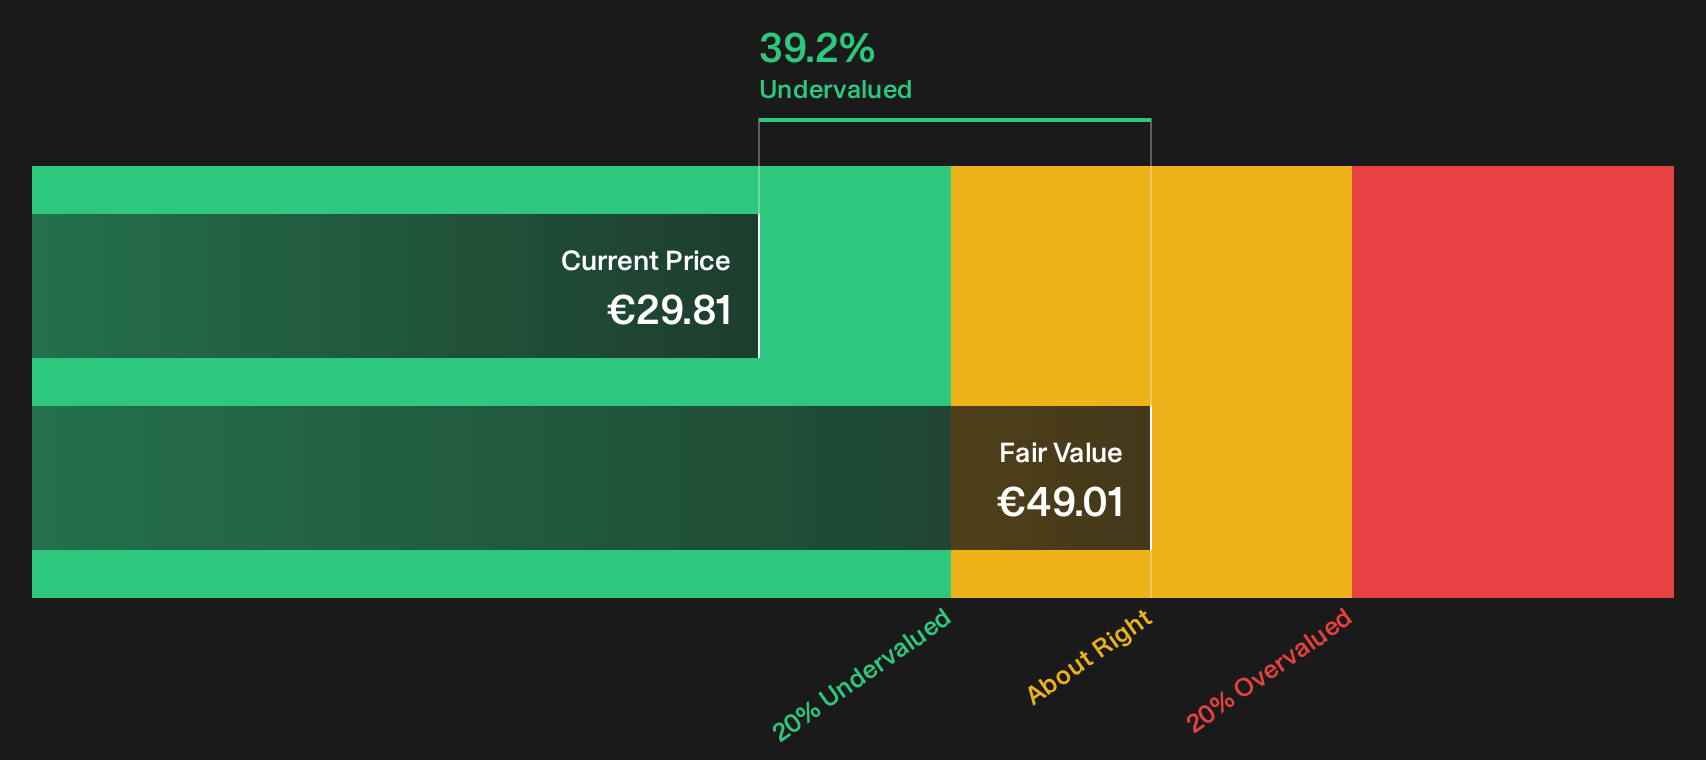
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Repsol for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Repsol is clearly split, which is exactly when it pays to move quickly, examine the full data set yourself and decide how comfortable you are with both the upside and the downside. To help frame that view, start with the balance between its 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Repsol?
If the split views on Repsol have sharpened your thinking, now is the moment to broaden your watchlist and line up your next potential moves.
- Target potential mispricing by scanning a curated set of companies with resilient cash flows that still look attractively valued through the 191 high quality undervalued stocks.
- Build your income stream with businesses that pair higher yields with durability by reviewing the carefully assembled 168 dividend fortresses.
- Lower the chance of nasty surprises by focusing on financially robust operators using the focused list of solid balance sheet and fundamentals (207 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com