


Is RUM Group (RUM) Cheap Following Texas Capital's AI Infrastructure Call?
Texas Capital’s coverage initiation of RUM Group (RUM) put fresh attention on its shift into AI infrastructure, highlighting the Northern Data acquisition, the Quake AI business, and a long-term US$13.7b Anthropic agreement.
RUM Group’s recent coverage has landed after a choppy few weeks, with a 7-day share price return down 11.16% and a 30-day move down 10.43%, even though the 90-day share price return of 24.03% and three-year total shareholder return of 48.93% point to momentum that has been building over a longer stretch.
Compare RUM Group’s AI push with other potential breakouts by scanning 90 AI infrastructure stocks that are already wired into the same high-compute, data center theme.
RUM Group has slid over the past month while its AI infrastructure story has only just hit the spotlight. Do you lean into the weakness now, or wait for the valuation work to argue for patience?
Most Popular Narrative: 65% Undervalued
RUM Group’s most followed narrative pegs fair value at $22 per share, far above the recent $7.64 close, so the gap between price and story is wide.
The upcoming launch of Rumble Wallet, with integrated crypto tipping and international payments, is described as a potential driver of global user acquisition and engagement by tapping new markets where decentralized, creator-driven monetization is highly valued. The narrative states that this could influence top-line revenue and expand the platform's total addressable market. Expanding commercial partnerships (e.g., with Tether, Cumulus Media, leading AI players, and MoonPay) is presented as a way to create diversified revenue streams and unlock new ad inventory and creator monetization opportunities, which the narrative links to potential revenue and ARPU growth while reducing reliance on a niche user base.
See why 23 investors see RUM Group as 65% undervalued.
The narrative leans on a discount rate of 8.6% and incorporates aggressive revenue and earnings forecasts, then compares that to today’s share price to arrive at a fair value of $22. It assumes very fast top-line expansion, a swing into profitability, and a small positive profit margin in the future, which together are used to back into that figure.
To align with this view, you would need to be comfortable with the implied P/E on those future earnings and with the idea that RUM Group’s AI infrastructure, creator platform, and crypto monetization efforts can support those levels of revenue and profit. You would also need to weigh the outlined risks around cash burn, regulation, and integration of Northern Data against that upside case.
Result: Fair Value of $22 (UNDERVALUED)
Still, RUM Group faces real pressure if the Northern Data integration stumbles, or if ongoing losses, debt and the fraud investigation further strain investor confidence.
Find out about the key risks to this RUM Group narrative.
Another View on RUM Group’s Valuation
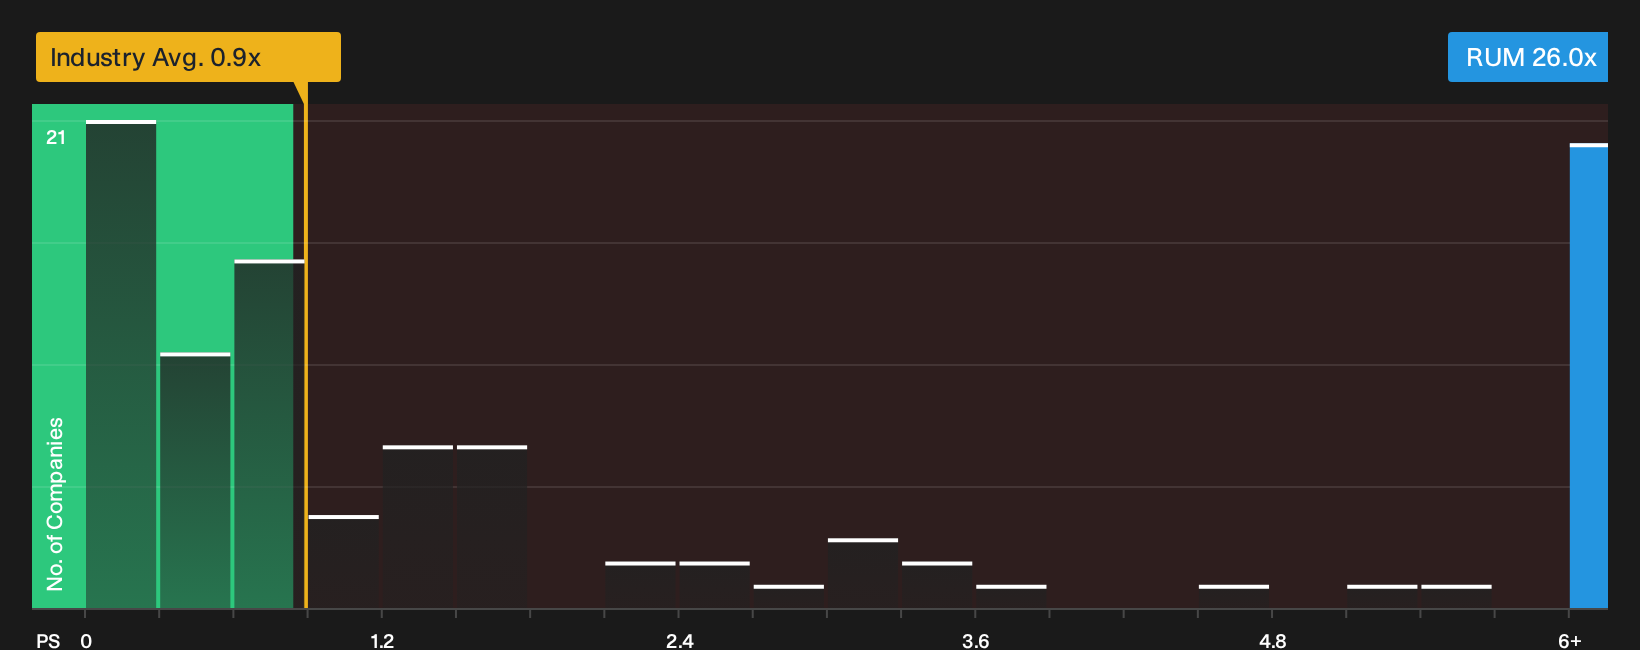
Those bullish narratives lean heavily on future earnings and a fair value of $22, but the current P/S of 26x tells a different story. That multiple is far above the US Interactive Media and Services average of 0.9x and a fair ratio of 20.1x, which points to meaningful valuation risk if expectations cool.
To see how that premium stacks up against the numbers, and what it could mean if the share price drifts toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling mixed on RUM Group after all this, or leaning one way? Act while the data is fresh and weigh both sides by checking the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond RUM Group?
Do not let your research stop with RUM Group. Broaden your watchlist now by scanning focused stock ideas that match different goals on Simply Wall Street.
- Target potential mispricing by reviewing companies that screen as high quality yet out of favor using the 28 high quality undervalued stocks.
- Strengthen your income stream by hunting for payout-focused businesses that pass the yield and stability checks in the 7 dividend fortresses.
- Dial back portfolio risk by zeroing in on financially resilient businesses through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com