


How Investors May Respond To adidas (XTRA:ADS) Limited Edition Brand Tie Ups
- Adidas' partners announced two limited-edition collaborations in September 2026, pairing SNICKERS branding with ADIZERO ELECTRIC + II cleats and a Tim Hortons themed Tims Run Club collection across footwear, apparel and accessories.
- These collaborations plug adidas directly into seasonal rituals like Halloween, football viewing and the everyday coffee run, giving the brand fresh ways to test themed product demand and consumer engagement at premium price points.
- We will now examine how adidas' investment narrative could be influenced by the Tim Hortons coffee themed Tims Run Club collaboration.
adidas Investment Narrative Recap
To own adidas, you need to believe the brand can keep turning strong product pipelines and collaborations into healthier earnings, despite cost and competitive pressure. In the short term, the focus is still on rebuilding margin quality while managing tariffs and promotions, especially in the U.S., where pricing power looks more constrained.
The recent SNICKERS and Tim Hortons collaborations are helpful for brand heat and for testing premium, ritual based collections, but they do not change the main near term swing factors. Tariff driven cost headwinds, fashion cycle risk on key franchises and intense North American competition remain the biggest issues to watch.
The Tim Hortons Tims Run Club drop is the most relevant piece of news here because it directly links adidas to an everyday habit, the coffee run, rather than just big game moments. That fits the thesis that the group wants more recurring, lifestyle driven demand on top of performance categories such as Running and Training.
For catalysts, this type of collaboration only really matters if it supports higher full price sell through, stronger D2C traffic in Canada and adjacent markets, and more consistent demand between big seasonal releases. If it misfires, it would mainly reinforce the risk that fashion and collaboration cycles can stall, leading to higher markdowns and weaker margins.
Adidas' current analyst narrative points to revenues of €31.9 billion and earnings of €2.4 billion by 2029. That projection builds on an assumed 7.0% yearly revenue growth rate and implies earnings rising by about €1.0 billion from €1.4 billion today.
Uncover why adidas' fair value indicates a 42% potential upside to its current price, which could narrow quickly.
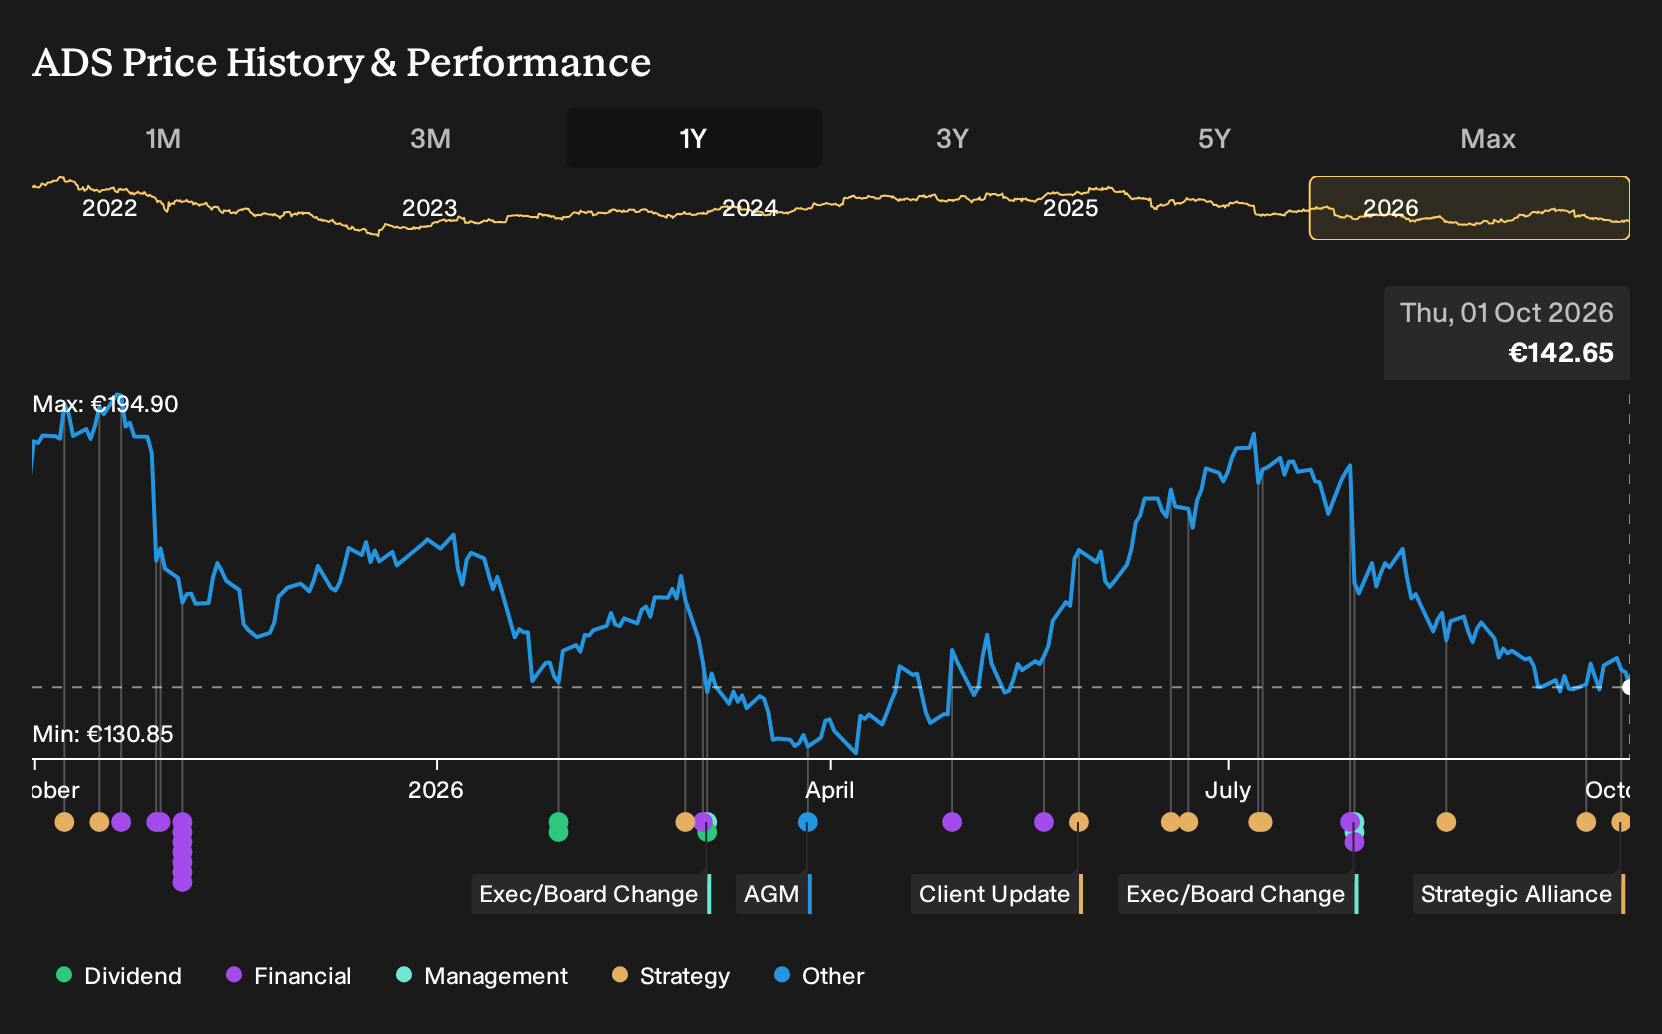
Exploring Other Perspectives
Some of the most optimistic adidas analysts lean hard into collaborations as a catalyst. Before this Tims Run Club news, they were already pencilling in €33.5b of revenue and €2.7b of earnings by 2029. You can see how views can stretch well beyond consensus, so treat this drop as a chance to compare several narratives, not just one.
Explore 7 other adidas fair value estimates, including one that suggests as much as 143% difference from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your adidas research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for adidas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate adidas' overall financial health at a glance.
Looking for more adidas-sized investment ideas?
If the adidas story has sparked a few questions about what else might fit your portfolio, it can help to scan a broader set of stocks that share strong fundamentals, income potential or overlooked quality. The Simply Wall St Screener lets you filter for traits that matter to you and then compare companies on the same footing.
- For investors who care most about quality and valuation discipline, start with a curated group of businesses that combine robust fundamentals with attractive pricing through our 191 high quality undervalued stocks.
- If portfolio resilience is your priority, you can focus on companies that score well on financial strength and risk metrics by reviewing a 226 resilient stocks with low risk scores.
- Those hunting for under-the-radar opportunities can scan a 616 high quality undiscovered gems that pair solid financial profiles with limited current attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com