


Vulcan Materials (VMC) Slides On Valuation Debate, Is The Stock Still Undervalued?
Vulcan Materials (VMC) is back in focus after a recent share price slide, with the stock down about 6% over the past month and almost 20% in the past 3 months.
That pullback comes after a weaker patch for Vulcan Materials over 2024, with the share price now at US$243.98 and the year to date share price return down 16.6%, even though total shareholder returns over three and five years remain positive.
Compare Vulcan Materials' recent pullback with a curated set of construction and infrastructure peers by scanning the 39 power grid technology and infrastructure stocks that is powering long-term projects across grids, roads, and heavy materials.
Analyst targets now sit well above Vulcan Materials' share price, while one valuation model suggests a modest premium. Does the recent slide reflect market caution, or a genuine gap to fair value?
Most Popular Narrative: 24% Undervalued
On the most followed narrative, Vulcan Materials screens as undervalued, with a fair value of about $321.78 versus the recent close near $243.98. The question becomes whether the projects and pricing behind that view can realistically support the gap.
The company's footprint in growing Sunbelt metros continues to line up with a visible pipeline of large public and private projects, including a large volume of data centers and related power and LNG work. About 60% of all large projects are within 50 miles of a Vulcan facility, which can support future aggregates shipments and earnings as those projects move from award to steady production.
See why 13 investors see Vulcan Materials as 24% undervalued.
Result: Fair Value of $321.78 (UNDERVALUED)
Still, higher diesel costs and the weaker 2027 volume outlook flagged in the September 2026 Underweight call could quickly challenge this Vulcan Materials undervaluation story.
Find out about the key risks to this Vulcan Materials narrative.
Another View: Vulcan Materials Looks Expensive On Earnings
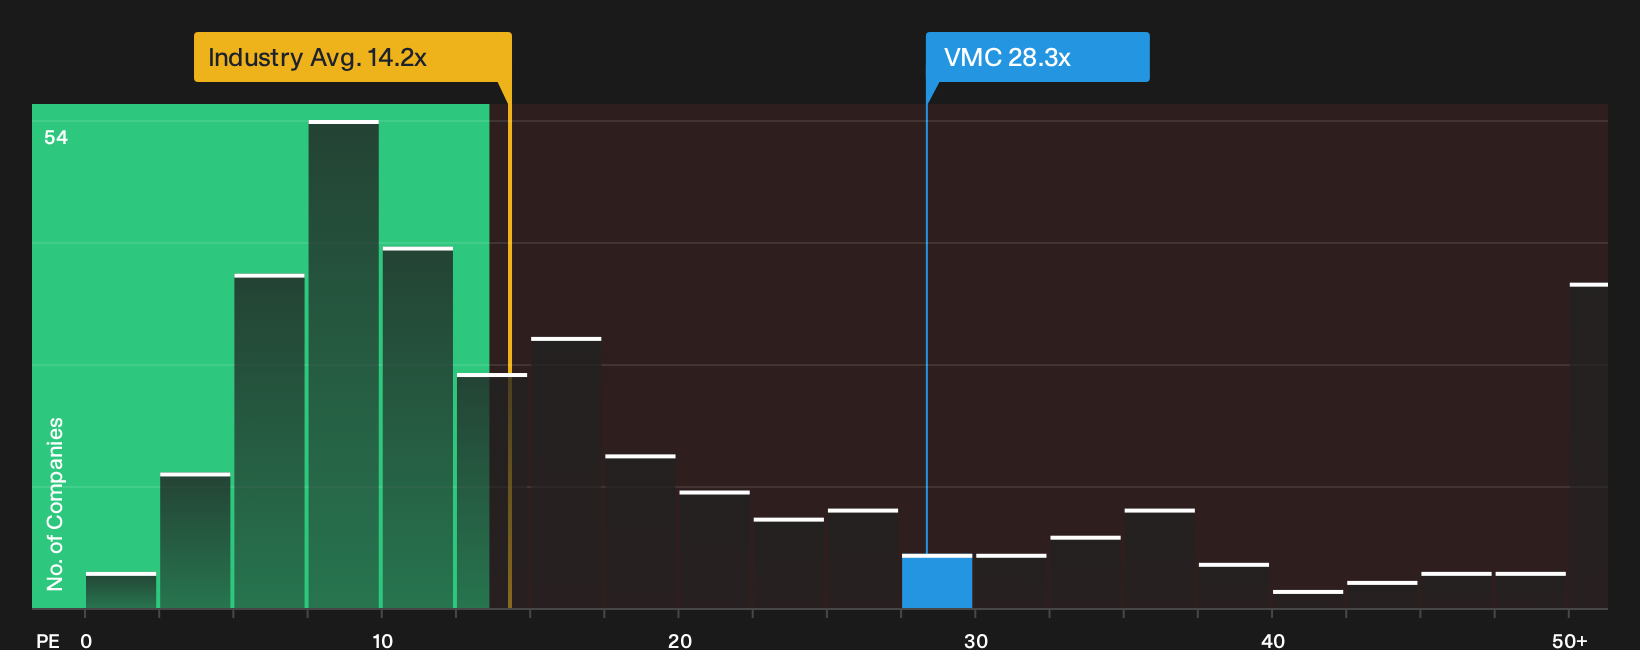
The fair value narrative for Vulcan Materials leans on future cash generation and analyst forecasts. On a simple P/E check today, the picture looks very different. VMC trades at 28.3x earnings, compared with 14.3x for the global Basic Materials group and 21.1x for its peer set.
That premium also sits well above an estimated fair ratio of 20.4x. For investors, this means paying a higher price for each dollar of current profit, which can increase the risk of a valuation reset if growth or margins fall short of expectations.
To see how this earnings multiple stacks up against detailed valuation work, including where the fair ratio suggests the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Vulcan Materials valuation can be confusing, so look at the data yourself and decide quickly where you stand. To weigh both sides of the story in one place, review the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Vulcan Materials?
If Vulcan Materials has sharpened your focus on valuation and risk, do not stop here. Use curated screeners to surface new opportunities that match your checklist.
- Target resilient balance sheets and cash flows by reviewing the list of solid balance sheet and fundamentals (25 results) that can help you steer clear of fragile businesses.
- Zero in on potential mispricings by scanning the 28 high quality undervalued stocks that filter for quality companies trading below their assessed worth.
- Prioritize income and staying power by checking the 7 dividend fortresses designed to highlight higher yielding options with robust profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com