


BAWAG Group (WBAG:BG) Completes Green Notes Offering, Is The 10% Upside Still Compelling?
BAWAG Group (WBAG:BG) recently completed a €499.245 million fixed income offering of fixed to floating rate preferred notes maturing in 2031, a funding move that highlights its capital structure and long term financing approach.
Recent trading shows some cooling in momentum, with the share price down about 1.8% over the past week and roughly 0.8% over the last month. At the same time, BAWAG Group’s year-to-date share price return of 35.15% and very large 3-year total shareholder return of about 3.8x point to strong longer term gains. This frames this green bond issue as another potential catalyst in an already active period for the bank.
See how BAWAG Group’s green bond move compares with other banks’ funding for growth by reviewing our curated list of list of solid balance sheet and fundamentals (207 results)
Bulls point to BAWAG Group’s strong multi year shareholder returns and fresh green funding, while bears flag recent price softness and cycle risk. Which side do the current valuation signals support next?
Most Popular Narrative: 10% Undervalued
BAWAG Group’s most followed valuation narrative puts fair value at about €195.37 per share, above the last close of €175.70. This frames the recent green bond issue against a wider rerating story anchored on earnings power and disciplined capital deployment.
Ongoing integration of Knab and Barclays Consumer Bank Europe, with expected completion by year-end (including exit from transitional service agreements and rebranding), should unlock operational synergies and drive further cost efficiency, supporting higher net margins over time.
Increasing digital engagement, evidenced by BAWAG's disciplined digital transformation and lowered cost/income ratio, positions the company to benefit from rising digital adoption in Europe, reducing cost-to-serve and boosting long-term operating margins.
See why 10 investors see BAWAG Group as 10% undervalued.
This storyline assumes analysts’ cash flow forecasts are discounted at 6.91%, with revenue growth around 17% a year, margins near 43%, and a future P/E of 12.9x on earnings of €1.4b by 2029. The result is a fair value of €195.37, which implies the narrative views BAWAG Group as meaningfully undervalued at current levels.
Result: Fair Value of €195.37 (UNDERVALUED)
Still, the BAWAG Group story could change quickly if interest rates in Europe fall faster than expected or if regional credit losses rise from current levels.
Find out about the key risks to this BAWAG Group narrative.
Another View: BAWAG Group Through The P/E Lens
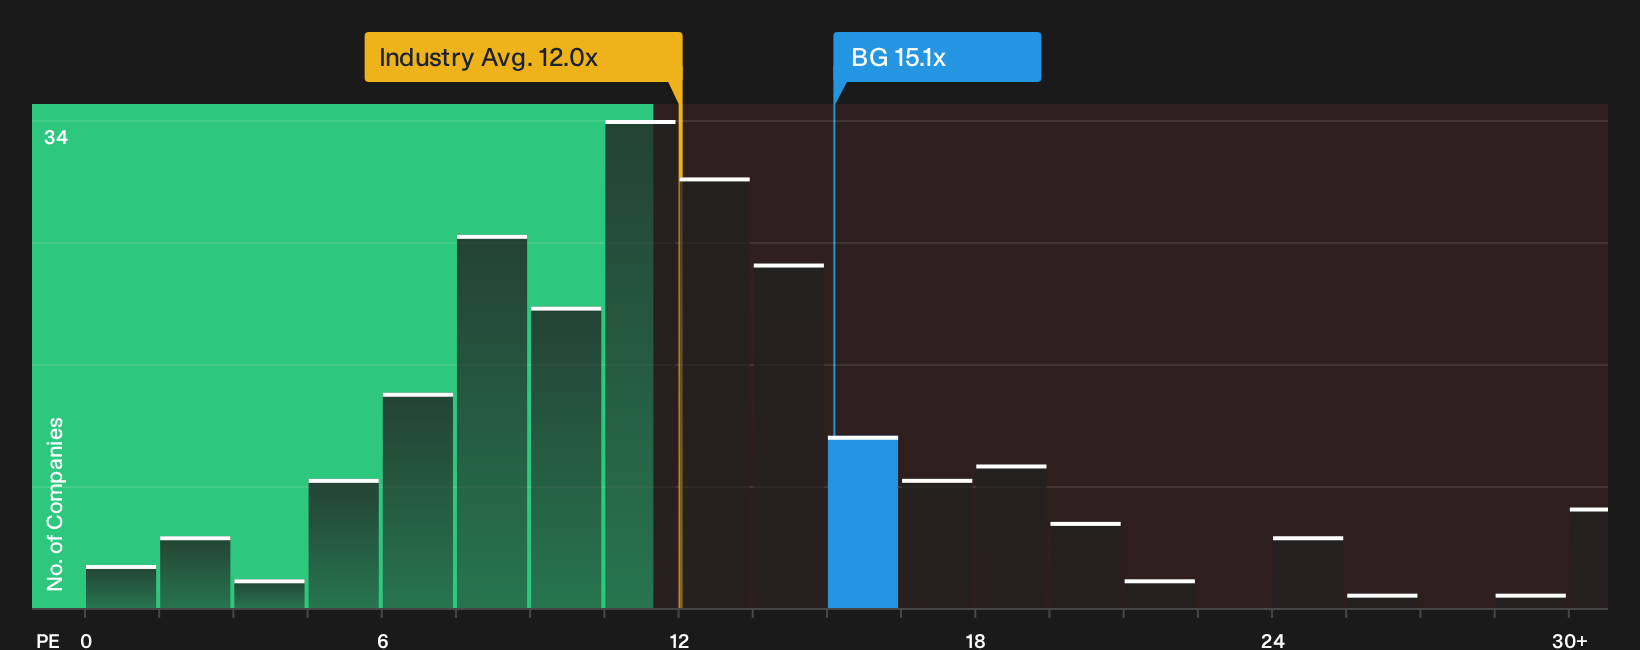
DCF fans might see BAWAG Group as cheap, yet the market’s simple P/E check tells a tougher story. The shares trade on about 15.1x earnings, compared with 12.2x for the wider European banks and a fair ratio estimate of 12.4x. That richer tag points to less margin for error if growth or returns disappoint. Which signal do you trust when the narrative is this split?
For investors weighing this valuation gap against their own expectations, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on BAWAG Group is clearly mixed, with solid past returns alongside fresh questions on valuation and risk. Act quickly, review the underlying data for yourself, and weigh up the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond BAWAG Group?
If the BAWAG Group story has sharpened your thinking, do not stop here. Broaden your watchlist now, because sitting still risks missing the next opportunity.
- Target durable balance sheets and resilient cash generation by scanning the list of solid balance sheet and fundamentals (207 results) that already clear strict financial health checks.
- Hunt for mispriced quality by reviewing the 191 high quality undervalued stocks that combine strong fundamentals with prices that still lag their underlying metrics.
- Prioritise stability and income by checking out the 166 dividend fortresses that pair robust payouts with balance sheets built to support them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com