


Hansoh Pharmaceutical Group (SEHK:3692) Could Be 30% Undervalued On Late Stage Drug Progress
Hansoh Pharmaceutical Group (SEHK:3692) just reported a cluster of late stage drug milestones, including NMPA acceptance of its biologics license application for osteosarcoma therapy HS-20093 and positive Phase III data for psoriasis candidate HS-10374.
Those drug updates arrive alongside a sharp move in Hansoh Pharmaceutical Group’s shares, with a 1-day share price return of 5.31% at HK$35.3 and gains over the past week and quarter. However, the year-to-date share price return has declined 3.13%, while the 3-year total shareholder return is very strong, which suggests momentum has picked up recently even though long term holders have already seen substantial value creation.
Capitalize on Hansoh Pharmaceutical Group’s late stage pipeline momentum by scanning a curated set of resilient healthcare names in the 226 resilient stocks with low risk scores.The question now is simple. After Hansoh Pharmaceutical Group’s sharp move on fresh trial and NMPA headlines, does it make more sense to step in at HK$35.3, or to wait for a calmer entry as valuation comes into focus next?
Price-to-Earnings of 27.4x: Is it justified for Hansoh Pharmaceutical Group?
Hansoh Pharmaceutical Group trades on a P/E of 27.4x, which puts a rich tag on the HK$35.3 share price compared with peers and its own fair multiple estimates.
The P/E ratio compares what investors pay today for each unit of current earnings. For a profitable drug maker like Hansoh Pharmaceutical Group, it is a quick read on how the market is weighing its earnings power against prospective developments in oncology, autoimmune diseases, and other specialty areas.
The 27.4x P/E is materially higher than the Hong Kong pharmaceuticals industry average of 13.9x, which means investors are paying roughly double the sector multiple for 3692. It also sits above the estimated fair P/E ratio of 24.6x. This indicates that the current tag includes a premium that the market could eventually compress toward that lower level if expectations change.
Explore the SWS fair ratio for Hansoh Pharmaceutical Group.
Result: Price-to-Earnings of 27.4x (OVERVALUED)
Still, the narrative around Hansoh Pharmaceutical Group can shift quickly if late stage assets hit regulatory delays or if revenue growth of 11.89% in China focused operations cools.
Find out about the key risks to this Hansoh Pharmaceutical Group narrative.
Another View on Hansoh Pharmaceutical Group’s Valuation
The P/E premium paints Hansoh Pharmaceutical Group as expensive, yet the SWS DCF model points the other way. At HK$35.3, the stock is described as trading about 30% below an estimated future cash flow value of HK$50.43. This frames it as undervalued on that lens. Which story do you give more weight to when earnings quality and pipeline risk are both in play?
Look into how the SWS DCF model arrives at its fair value.
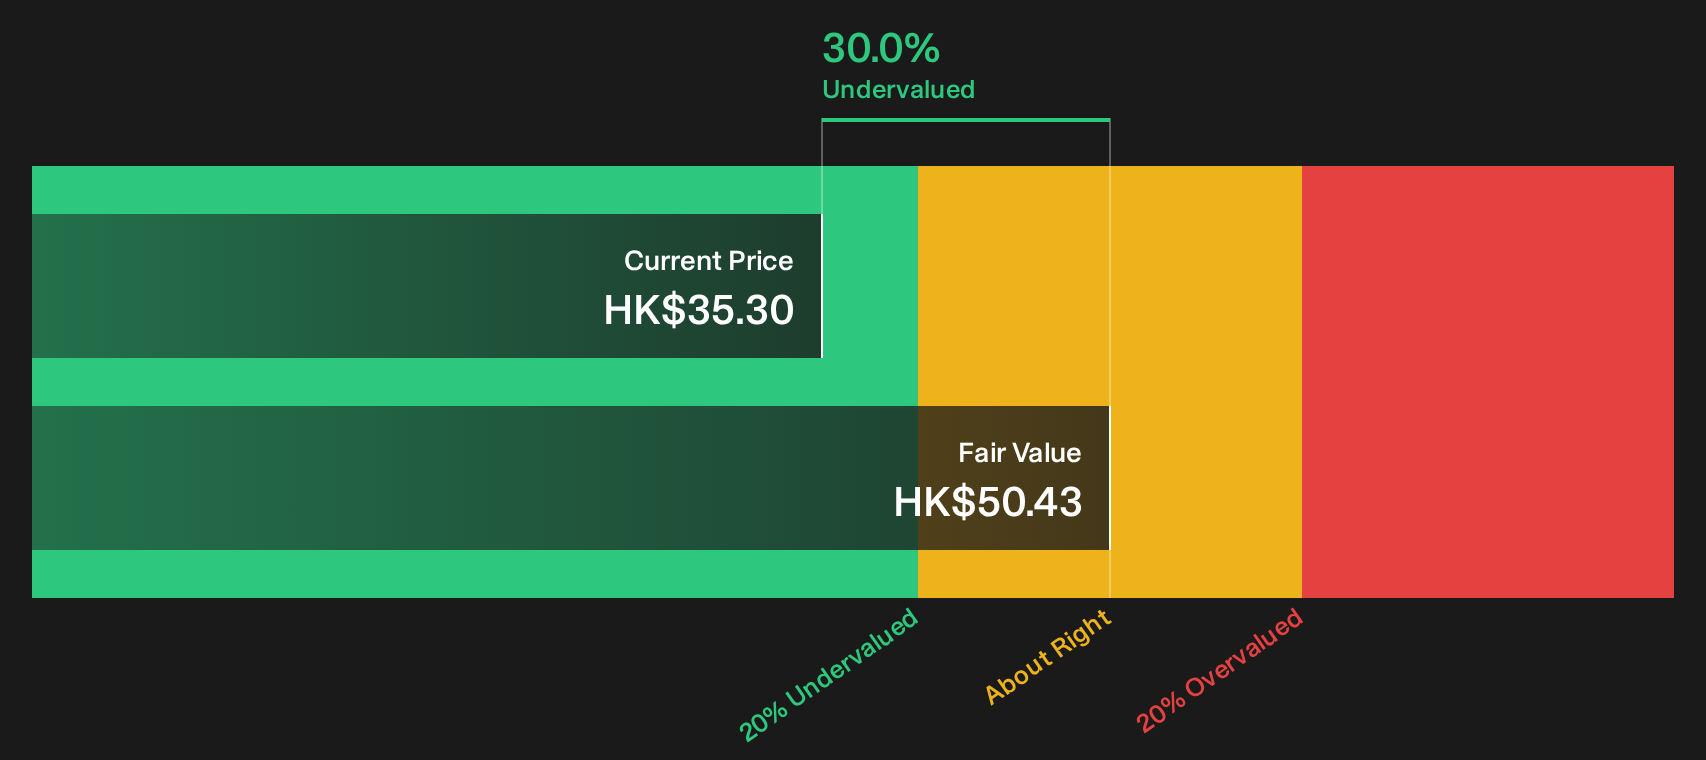
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hansoh Pharmaceutical Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hansoh Pharmaceutical Group so far. If you want to move quickly yet stay grounded in facts, start by weighing the 4 key rewards and 1 important warning sign.
Want more ideas beyond Hansoh Pharmaceutical Group?
If Hansoh Pharmaceutical Group has sharpened your focus on opportunities, broaden your watchlist with data driven stock ideas that match different goals and risk levels.
- Target long term value by scanning companies that combine quality fundamentals with attractive pricing using the 190 high quality undervalued stocks.
- Strengthen your income stream by reviewing potential high yield payers through the 164 dividend fortresses.
- Protect your capital by focusing on financially resilient businesses in the list of solid balance sheet and fundamentals (207 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com