


Earnings Upgrade Could Change The Bull Case For Nordea Stock
- Nordea Bank Abp recently received an analyst upgrade that was tied to higher earnings estimates, reflecting more optimistic expectations for its profit outlook based on available forecasts.
- The upgrade highlights how earnings expectations are being recalibrated in relation to Nordea Bank’s cost efficiency efforts, digital investments and fee-based income ambitions across its Nordic banking franchise.
- We will now examine how Nordea Bank’s investment narrative could be affected by rising earnings estimates and the recent analyst rating upgrade.
Scan how Nordea Bank Abp’s upgrade compares to peers by lining it up against 190 high quality undervalued stocks with similar earnings stories and re-rated expectations.
Nordea Bank Abp Investment Narrative Recap
To own Nordea Bank Abp, you need to be comfortable with a Nordic focused lender that leans on digital banking, fee income and relatively steady credit quality rather than fast top line expansion. The short term catalyst is still execution on cost efficiency and digital usage, which can support earnings even if lending volumes stay subdued. The recent earnings led upgrade simply reinforces that this operating focus remains central.
The biggest near term risk is pressure on net interest income if rate cuts or competition squeeze loan margins while deposit pricing stays sensitive. Regulatory demands and a relatively low allowance for bad loans at 62% add another layer of uncertainty. The latest upgrade does not materially change those risk factors; it simply reflects more confidence in how Nordea is handling them.
With no fresh corporate announcements tied directly to this rating move, the most relevant context comes from how Nordea Bank Abp has been positioning itself. Heavy investment in digital, data and AI, combined with strong take up of mobile channels, is intended to keep servicing costs down while keeping customers engaged. That operational push is where higher earnings expectations are most aligned.
For you as a shareholder, the key question is whether those digital and efficiency efforts can offset slower forecast revenue growth of 4.4% per year and modest expected earnings growth of 4.68% per year. Analyst optimism around earnings sits next to flagged issues such as a 5.65% dividend that is not fully covered and relatively low forecast return on equity at 15.7%. The upgrade connects most closely to execution on these operational levers rather than any single headline announcement.
Nordea Bank Abp is currently expected to move from earnings of €4.7b today to consensus earnings of €5.4b by 2029, a rise of about €0.7b. This is based on revenue that analysts project will reach €13.2b by that same year, implying 4.4% yearly top line growth over the next few years.
Uncover how Nordea Bank Abp's fair value indicates a 7% potential upside to its current price, before enthusiasm around the discount narrows that gap.
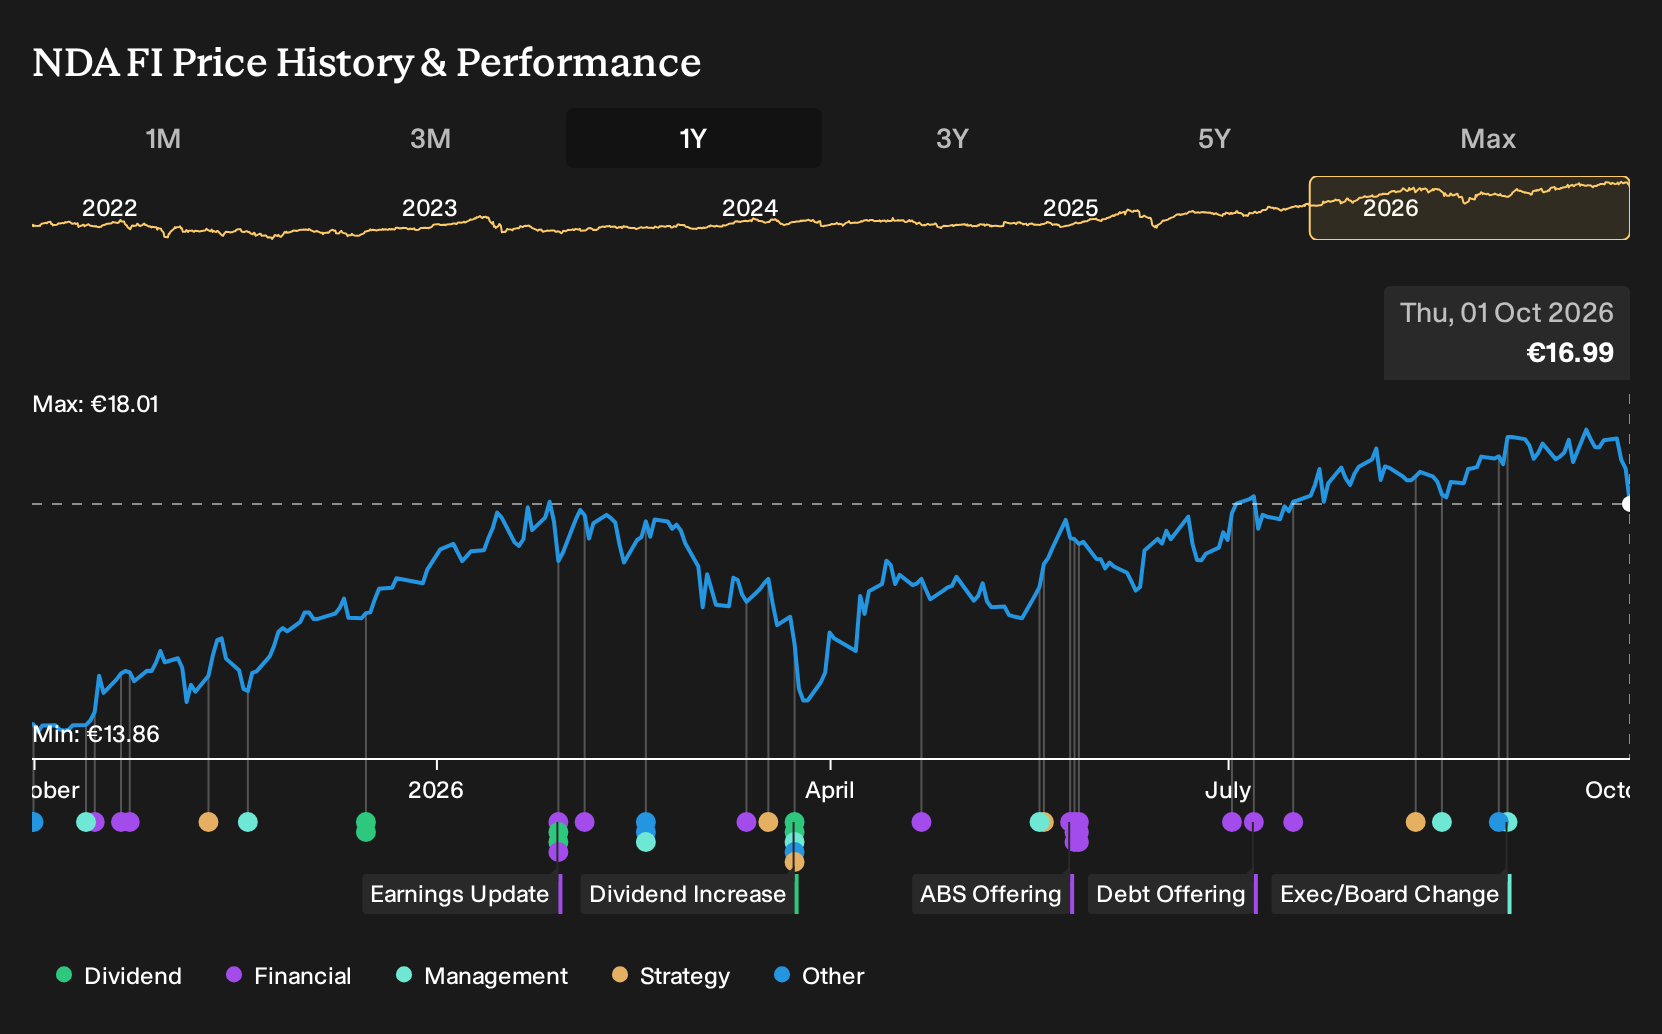
Exploring Other Perspectives
Across three fair value views from the Simply Wall St Community, estimates span roughly €18.26 to €31.38, so private investors are not aligned on where Nordea Bank Abp should trade. When you pair that spread with risks around policy rates, regulation and Nordic housing, you get a wide set of scenarios to consider.
Explore 2 other Nordea Bank Abp fair value estimates, including one that suggests it could be worth just €18.26.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nordea Bank Abp research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nordea Bank Abp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordea Bank Abp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nordea Bank Abp?
If you want to apply the same kind of structured thinking used here on Nordea Bank Abp to a wider watchlist, the Simply Wall St screener can help you filter for very specific traits instead of scrolling through tickers at random.
- For income that aims to pair higher yields with balance sheet resilience, review a set of potential dividend payers screened as 164 dividend fortresses.
- If capital preservation and steadier profiles matter most to you, narrow your focus to companies flagged as 226 resilient stocks with low risk scores and see which ones fit your comfort level.
- When you want quality but would rather not compete in the most crowded ideas, scan through 616 high quality undiscovered gems that the market may not be paying full attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com