


Franklin Templeton (BEN) Could Be 21% Below Fair Value Following Bybit Tokenized Collateral Deal
Franklin Templeton (BEN) is moving deeper into on chain finance after Bybit introduced a collaboration that lets eligible traders post tokenized money market fund shares as off exchange collateral through the Benji and ByCustody platforms.
Franklin Templeton’s move into tokenized collateral comes after a strong run in the share price this year, with a year-to-date share price return of 36.55% and a one-year total shareholder return of 48.88%, even as the 90-day share price return of 4.72% and recent 30-day softness suggest momentum has cooled slightly in the short term.
Scan other asset managers leaning into on chain finance by reviewing the curated 18 cryptocurrency and blockchain stocks, which ties regulated platforms like Franklin Templeton’s Benji to listed digital asset opportunities.
Franklin Templeton has already logged a strong run, and now this on-chain move pulls a fresh group of investors into the story. Is most of the easy upside already realised, or do the current valuation markers still leave meaningful room ahead?
Most Popular Narrative: 21% Undervalued
Franklin Templeton closed at $32.50 while the most widely followed narrative anchors fair value at $41.00, which implies a sizeable valuation gap that bullish analysts justify with higher margins and steadier flows over time.
Analysts broadly see alternatives expansion as a driver of long-term growth. However, Franklin's rapid and globally integrated buildout with the Apera acquisition pushing private credit AUM to $90 billion, strong wealth channel distribution, and first-mover advantages in democratizing access position the firm to outpace market share forecasts, potentially boosting net margins and earnings through higher fee structures.
See why 2 investors see Franklin Templeton as 21% undervalued.
Result: Fair Value of $41.00 (UNDERVALUED)
Still, fee pressure on active products and ongoing integration costs at Franklin Templeton could quickly weaken margins and undercut the bullish thesis that the stock is 21% undervalued.
Find out about the key risks to this Franklin Templeton narrative.
Another View: SWS DCF Flags Caution On Franklin Templeton
Where the bullish narrative pegs Franklin Templeton at a fair value of $41.00, the Simply Wall St DCF model paints a very different picture. On that framework, the estimated future cash flow value sits at $12.90, which screens the shares as expensive rather than undervalued. Which story do you lean toward?
For a closer look at how that cash flow based estimate is built, including the moving parts behind the discount rate and earnings assumptions, Look into how the SWS DCF model arrives at its fair value.
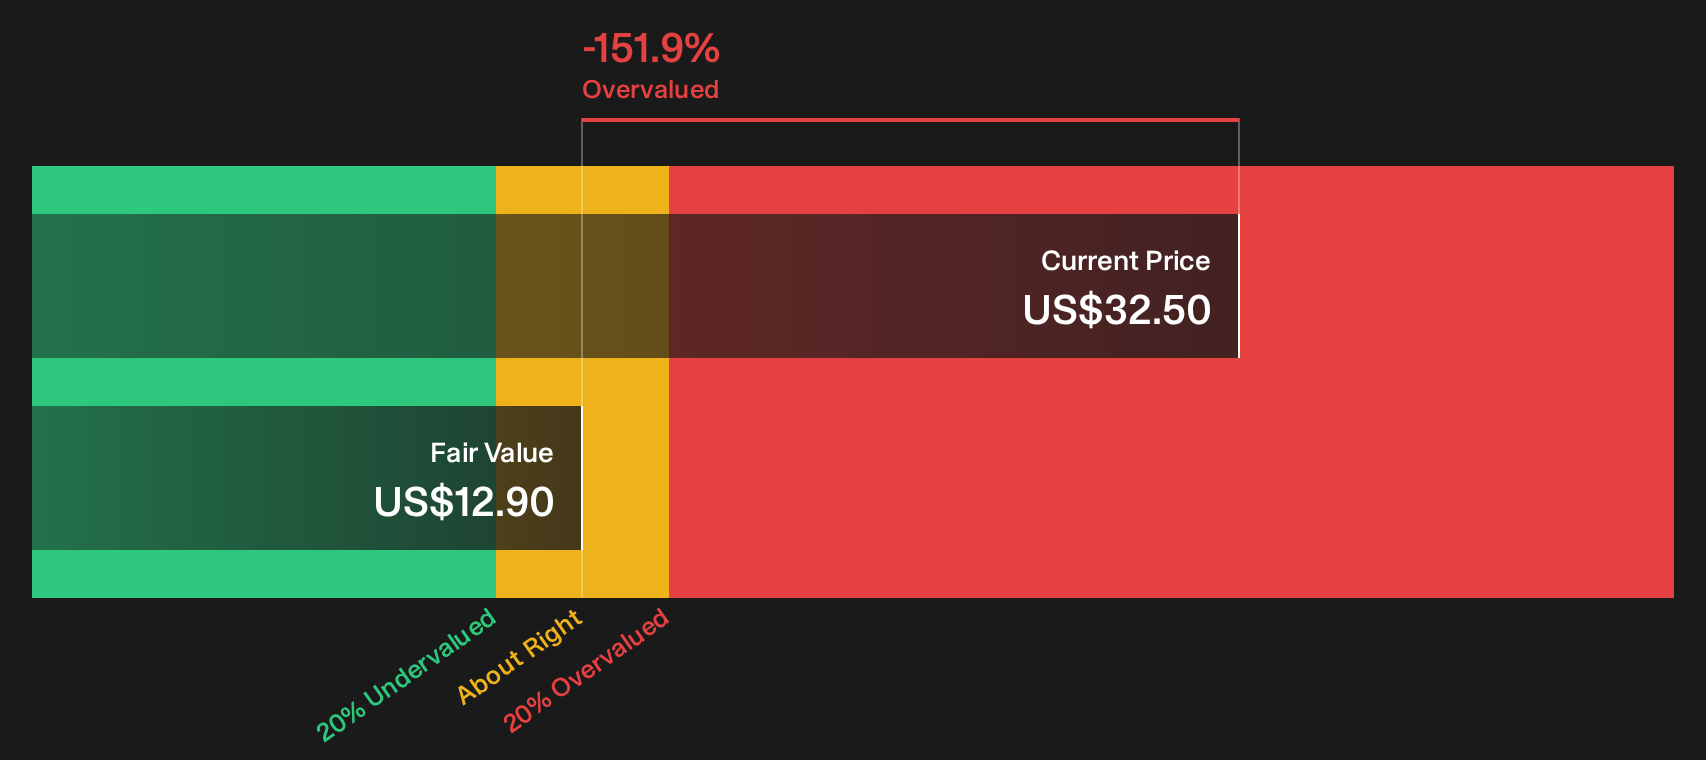
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Franklin Templeton for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of enthusiasm and caution around Franklin Templeton leaves you undecided, review the data that matters for your own portfolio right away and consider both sides through the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Franklin Templeton?
If Franklin Templeton has sharpened your focus on where capital can work harder, do not stop here. The next move you make could matter more than this one.
- Target potential mispricing by scanning a focused list of quality companies that look cheap on fundamentals through the 28 high quality undervalued stocks.
- Prioritise resilience by checking companies with cleaner balance sheets and sturdier financial footing via the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by reviewing the 19 high quality undiscovered gems before these quieter opportunities attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com